
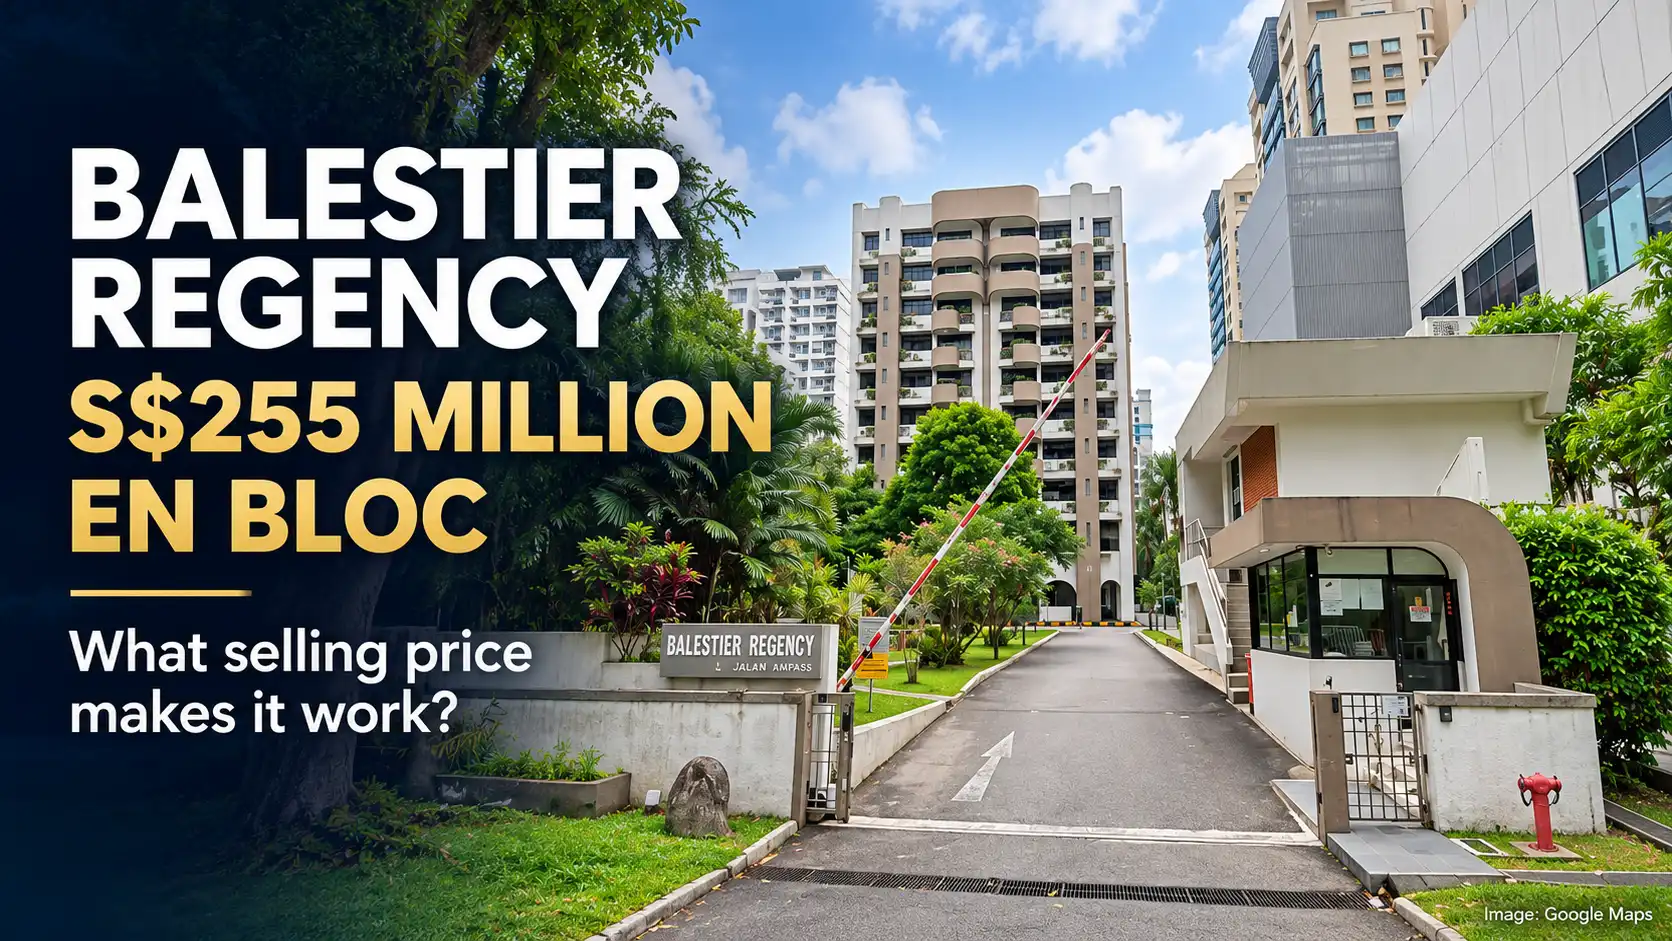
Balestier Regency has returned to the collective sale market at S$255 million, marking its fifth attempt to secure a buyer. The asking price is unchanged from its May exercise.
For a developer, the decision comes down to the price future homebuyers will pay. A freehold address provides a selling point, but the acquisition must leave enough room for construction, taxes, financing and a return that compensates for development risk.
Our illustrative feasibility model suggests that a redevelopment could need average selling prices of approximately S$2,700–S$2,900 psf, with a central case near S$2,800 psf. These are scenario estimates, not a valuation or a forecast of an eventual launch price.
The question is whether a future project at Jalan Ampas can achieve those prices across its entire unit mix, at a sales pace that makes the investment worthwhile.
What the asking price buys
The 72-unit freehold development occupies approximately 61,931 sq ft at 4 Jalan Ampas. Its plot ratio of 2.8 allows about 173,407 sq ft of gross floor area, with potential for up to 161 apartments, subject to approvals.
The guide price equates to about S$1,473 psf per plot ratio, including an estimated S$381,181 land betterment charge. With bonus balcony GFA included, the reported effective land rate falls to approximately S$1,437 psf ppr.
The tender closes 12 November 2026.
The land commitment approaches S$283 million before construction
At a S$255 million purchase price, residential buyer’s stamp duty would be approximately S$15.24 million, assuming that price is also the relevant dutiable value and applying the rates on an aggregated basis. The non-remittable 5% developer ABSD adds S$12.75 million.
Including the reported land betterment charge, the initial acquisition and tax allowance reaches approximately S$283.37 million.
The model assumes the developer qualifies for and retains remission of the separate 35% ABSD component. A clawback would significantly change the economics.
A transparent test of the selling price
The following scenarios assume 173,407 sq ft of saleable area equal to the published base GFA. Actual saleable area requires an approved design and could differ. No separate bonus balcony area is added to the model.
Construction allowances cover demolition, building works, common facilities and external works. Other allowances cover professional and statutory fees, financing, holding costs and contingency. They are analytical assumptions, not contractor quotations.
| Lower cost case | Central case | Higher cost case | |
|---|---|---|---|
| Acquisition, stamp duties and LBC | S$283.37m | S$283.37m | S$283.37m |
| Construction allowance | S$75m | S$85m | S$95m |
| Other development costs | S$25m | S$30m | S$35m |
| Total before selling costs | S$383.37m | S$398.37m | S$413.37m |
| Break-even average psf including selling costs | S$2,279 | S$2,368 | S$2,458 |
| Average psf for a 15% pre-tax margin on revenue | S$2,696 | S$2,802 | S$2,907 |
Selling expenses are assumed at 3% of revenue. Break-even revenue equals costs before selling expenses divided by 97%. Revenue needed for the illustrative 15% pre-tax profit margin equals those costs divided by 82%. This illustration assumes a 15% margin; individual developers may target different returns.
Under the central case, required sales revenue is about S$486 million. A handful of premium apartments selling above S$3,000 psf would not establish viability on their own: the weighted average across all saleable space matters.
Area efficiency also makes a substantial difference. If saleable area were 5% below the model’s assumption, with costs unchanged, the central target would rise from approximately S$2,802 to S$2,949 psf.
A nearby freehold benchmark gives the estimate context
The Arcady at Boon Keng provides a useful District 12 reference, although its location, access and product differ. The portal includes 112 sales, with the latest transaction in October 2026, ranging from approximately S$2,588 to S$2,784 psf, with an average price of S$ 2,601 psf*.
Our central Balestier Regency estimate is roughly 7.7% above the benchmark at The Arcady. A later selling period or a differentiated product could support such a gap. Neither is assured.
The comparison also raises a buyer-facing question: what would justify paying more? Efficient layouts, privacy, attractive outlooks and useful facilities would have to support the price alongside freehold tenure.
A developer buying today would therefore need a view on both future market conditions and the product it could deliver at this particular site.
*Prices extracted from PropNex Investment Suite. Accurate as of 14th October 2026. Contact us to understand the pricing band of various unit types.
Total prices could be the more demanding test
At S$2,800 psf, the purchase amounts would look like this:
| Illustrative apartment size | Price at S$2,800 psf |
|---|---|
| 700 sq ft | S$1.96 million |
| 900 sq ft | S$2.52 million |
| 1,100 sq ft | S$3.08 million |
| 1,300 sq ft | S$3.64 million |
These are size illustrations, not a proposed unit mix, and exclude buyers’ taxes and other expenses.
The implications become more demanding as apartments grow. A 1,100 sq ft home crosses S$3 million, where buyers may compare a wider selection of locations and larger resale alternatives.
Smaller apartments can reduce entry prices, but the scheme still needs a workable mix within planning requirements. Larger homes need enough functional space and quality to justify their total price.
The developer’s task is to align the site’s achievable density, apartment sizes and buyer budgets.
An unchanged price needs a stronger business case
A relaunch at the same asking price could succeed if achievable selling prices have improved, financing or construction costs are more favourable, or a developer identifies a better design and unit mix.
The relaunch itself does not establish that any of these improvements have occurred.
Nor should the fifth attempt be read as five identical developer rejections. The reported history includes attempts that did not secure the required owner consent. Those failures differ from a tender attracting no acceptable bid.
For the current exercise, the decisive issue is whether a purchaser can underwrite the future sales revenue with enough confidence.
At S$255 million, Balestier Regency offers a freehold redevelopment opportunity whose economics appear sensitive to both selling prices and saleable area. Our central scenario points to an average near S$2,800 psf; less efficient area delivery could move that closer to S$3,000 psf.
The owners’ asking price becomes workable when a developer can connect that required revenue to a credible product and a sufficiently deep pool of buyers.
Disclaimer: This article is for general information and discussion only and does not constitute investment, financial, legal or property valuation advice. The feasibility calculations use illustrative assumptions for construction costs, financing, saleable area, selling expenses and profit margins. They do not represent any developer’s actual costs, required returns or future launch prices. Actual outcomes will depend on the acquisition terms, approved development plans, prevailing taxes, market conditions and other factors. Reported redevelopment potential remains subject to regulatory approval. Readers should independently verify the information and seek appropriate professional advice before making any property decision.
Article contributed by Jerry Wong.

Jerry Wong is a realtor at Propnex Realty, bringing a rich background in interior and lighting design to his work. He loves exploring diverse spaces and observing the transformative power of real estate. Beyond his professional role, Jerry finds his greatest fulfillment in connecting people with the right properties, gaining immense satisfaction from helping clients achieve their dreams.

Let’s Discuss Your Property Plans
Interested in This Property?
Buying, selling or renting? Get a free consultation with realtors with a background in interior and lighting design. We’ll discuss your goals and help you assess your options—from pricing and timelines to layout practicality and space potential.
Share your contact details below, and we will get in touch to understand your needs and suggest the next steps. No pressure. No obligation to proceed.
Other Topics That May Interest You
Enquire About This Property
Check current availability and rental terms, arrange a viewing, or discuss whether the space could meet your business needs.
Share your requirements and we will get in touch. No obligation to proceed.