
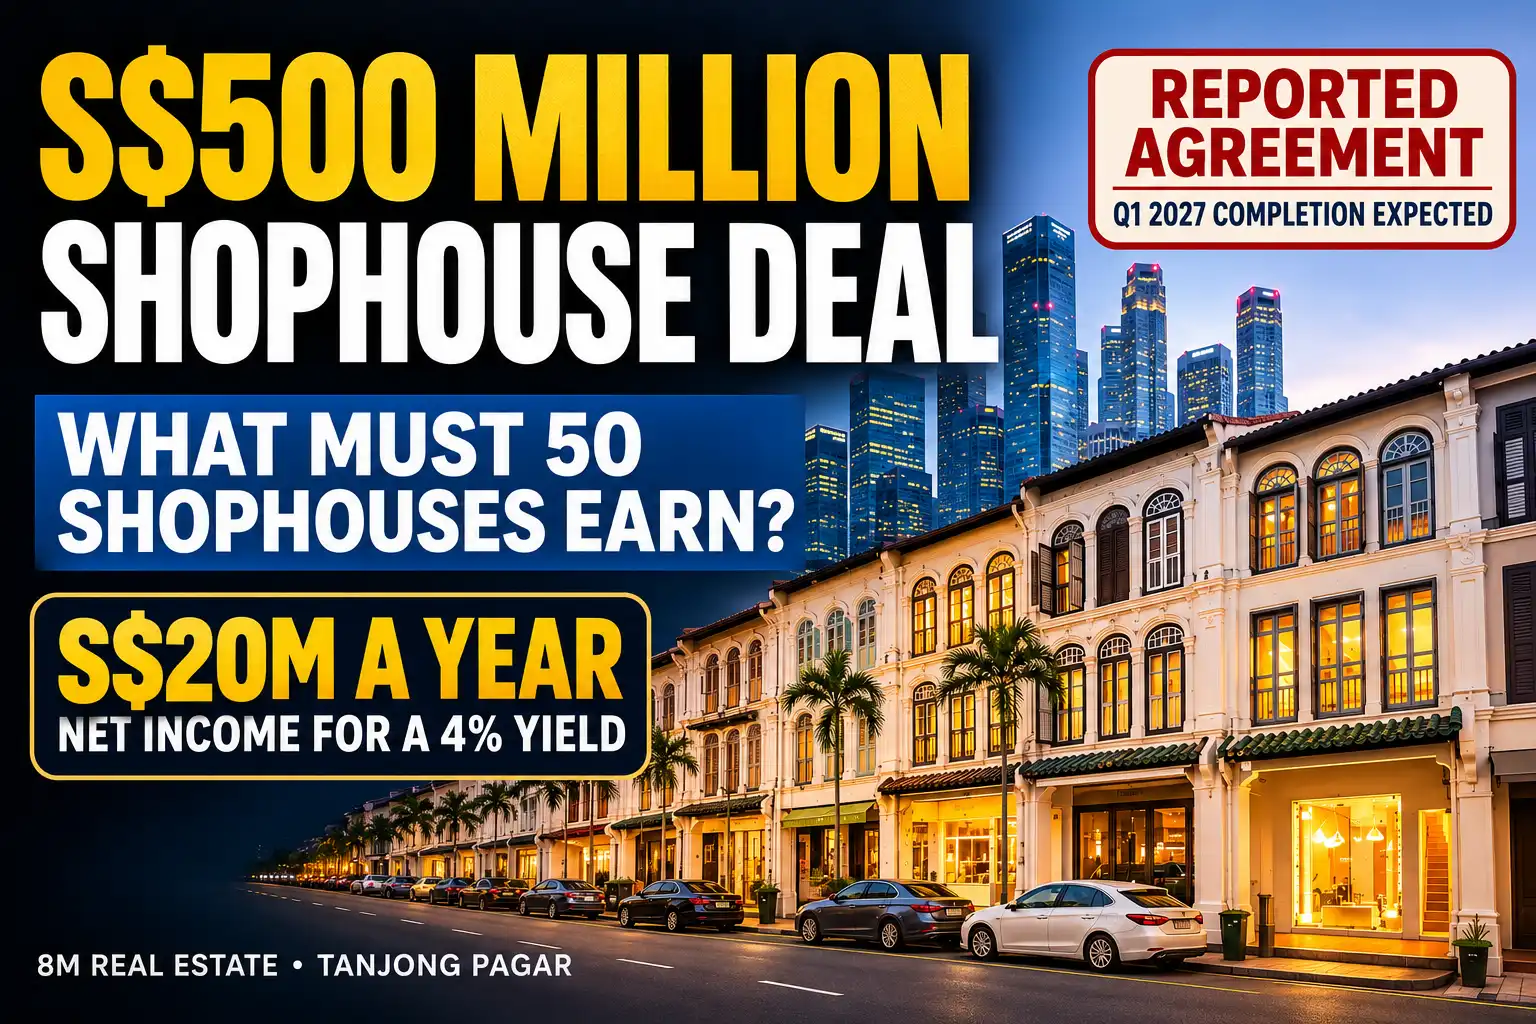
Seven shophouses in a row on Duxton Road give a landlord a say in what happens along a stretch of the street. They also leave that landlord with seven sets of upper floors to fill. For 8M Real Estate, what tenants will pay for the space upstairs could matter as much to its reported S$500 million acquisition as the restaurants it can attract at street level.
In August, we examined why 8M, owned by Crane Capital and backed through it by the Washington State Investment Board, might buy a portfolio of leasehold shophouses linked to veteran property investor Tony Chen. At the time, the parties were in talks. On 11 November, The Business Times reported that 8M was understood to have signed an agreement to acquire about 50 properties. Completion is expected in the first quarter of 2027.
The November report gives us a figure that takes the analysis further. The buildings contain about 180,000 sq ft of built-up area, putting the reported price at roughly S$2,778 psf, or S$10 million per shophouse on average. The question for 8M is how much of that space can earn rent, and what tenants will pay.
What would a 4% yield require?
A 4% net property yield on S$500 million requires S$20 million in annual net property income. Across 50 shophouses, that averages S$400,000 per building each year after property operating expenses. A corner restaurant with prominent frontage and a smaller mid-terrace property could contribute very different amounts towards that average.
To translate that figure into rent, suppose 85% of the built-up area is lettable, giving 153,000 sq ft. Assume the landlord keeps 80 cents of each rental dollar after recurring expenses such as property tax, insurance, maintenance, and management. The table shows the average monthly rent each occupied square foot must earn.
| Net yield on S$500m | Annual net property income needed | Rent at 85% occupancy | Rent at 90% occupancy | Rent at 95% occupancy |
|---|---|---|---|---|
| 3% | S$15 million | S$12.01 | S$11.35 | S$10.75 |
| 4% | S$20 million | S$16.02 | S$15.13 | S$14.33 |
| 5% | S$25 million | S$20.02 | S$18.91 | S$17.92 |
Rents are in Singapore dollars per occupied sq ft per month, averaged across all floors. These are illustrative scenarios. The reporting does not disclose 8M’s target yield, the rent roll, occupancy, lettable area or operating costs. The model excludes acquisition costs, financing and major refurbishment.
At 95% occupancy, tenants would need to pay S$25 million a year between them to leave S$20 million after expenses. That works out to S$14.33 psf per month across 145,350 occupied sq ft. If occupancy falls to 85%, the rent required rises to S$16.02 psf. That difference matters for a buyer planning improvements. Taking several neighbouring buildings out of use for refurbishment reduces the area earning rent while work is underway.
Can the upper floors carry their share?
A recent Commercialguru listing on Tras Street illustrates the challenge. The asking rent for a 1,150 sq ft second-floor café space was S$8.35 psf per month. The achieved rent and any connection to the sale portfolio are unverified, but the listing gives us a reference point to test our estimates.
Suppose half the occupied area earned S$8.35 psf upstairs. To reach the S$14.33 average in our 4% scenario, the other half would have to earn about S$20.32 psf per month. If the best street-front premises make up less than half the occupied space, they would have to command an even higher rent, assuming the same rate upstairs.
This is why a floor-by-floor rent roll would tell us more than the rent achieved by the best restaurant on Duxton Road. How long does the floor above it sit empty between tenants? What rent does the incoming tenant actually pay after a fit-out period? Across 50 buildings, the answers could move annual income by millions.
What is a row of shophouses worth to one landlord?
The portfolio spans Duxton Road, Duxton Hill, Tras Street, Craig Road and Neil Road. The sellers include investor groups associated with Chen, with much of the portfolio reportedly held through Hillington International, which indirectly owns Arcc Holdings. Two clusters stand out: seven adjoining shophouses at 73–79 Duxton Road and five at 56–64 Tras Street.
A telling detail sits at 69 and 71 Neil Road. As we recounted in August, 8M sold 71 Neil Road to Chen in 2019, when he already owned the neighbouring property. Both addresses are now in the reported portfolio. If the deal completes, 8M will have the opportunity to manage the pair together.
A landlord controlling a row can stagger repairs and choose tenants whose trading hours complement each other. It might accept a slightly lower offer from a daytime café if the café brings customers to a stretch otherwise active only at dinner. The financial benefit shows up when neighbouring tenants renew, vacant units fill sooner, or the buildings cost less to run. Concentration also cuts the other way. Several restaurants along one street can feel the same slowdown in spending.
For every extra S$10 million paid to secure the buildings together, 8M would need S$400,000 in additional recurring annual net income to preserve a 4% yield. That gives us a way to judge a portfolio premium. Establishing whether 8M actually paid one would require credible standalone values for the properties. Judging whether it was worthwhile would also require the cost of the works and the additional income they produce.
The leases put a time limit on the strategy
Most of these properties have roughly 61–62 years remaining on their land leases. The Tras Street properties have about 67 years. After a ten-year hold, the next buyer of most of the portfolio would be purchasing roughly 51–52 years of remaining income. A refurbishment that lifts rents quickly therefore has a different value from one that takes years to repay its cost, even if both eventually achieve the same rent.
The strongest reason to buy these shophouses together is the chance to earn more from an entire row than separate landlords could earn building by building. At S$500 million, every percentage point of net yield takes S$5 million a year. Better tenant selection, fuller upper floors and fewer months lost between leases would have to add up to meaningful sums.
If the purchase completes in Q1 2027, the figure we would most like to see is the annual net income 8M inherits on day one. That would show how much of the S$20 million in our 4% scenario existing tenants already support, and how much 8M would still need to earn.
Disclaimer: This article is for general information only. The proposed acquisition by 8M Real Estate, its approximate S$500 million price and the expected Q1 2027 completion are based on media reporting available at the time of publication.
The rental and yield scenarios are illustrative and use assumptions about lettable area, occupancy and operating expenses. The scenarios exclude acquisition costs, financing and major refurbishment. Actual income and returns may differ materially depending on the portfolio’s rent roll, lease terms, operating costs and final transaction terms. Readers should conduct their own due diligence and seek independent professional advice before making any investment decision.
Article contributed by Jerry Wong.
 Jerry Wong is a realtor at Propnex Realty, bringing a rich background in interior and lighting design to his work. He loves exploring diverse spaces and observing the transformative power of real estate. Beyond his professional role, Jerry finds his greatest fulfillment in connecting people with the right properties, gaining immense satisfaction from helping clients achieve their dreams.
Articles You May Also Like
Let’s Discuss Your Property Plans
Interested in This Property?
Buying, selling or renting? Get a free consultation with realtors with a background in interior and lighting design. We’ll discuss your goals and help you assess your options—from pricing and timelines to layout practicality and space potential.
Share your contact details below, and we will get in touch to understand your needs and suggest the next steps. No pressure. No obligation to proceed.