In Part 1 of our Lucerne Grand analysis, we looked at the rental market around Lakeside MRT and Jurong Lake to estimate how the different unit types could perform from an income perspective.
Part 2 looks at the other half of the investment equation:
How much of a premium are buyers paying for Lucerne Grand today, once we properly account for both GFA harmonisation and the remaining lease of the surrounding 99-year leasehold developments?
This second adjustment is important. A direct comparison between a brand-new 99-year leasehold project and a condominium with only 68, 75 or 83 years remaining can make the newer project look more expensive than it really is. Conversely, ignoring the lease age can make an older resale project look artificially cheap.
For this analysis, we will therefore make two separate adjustments to the surrounding projects:
- A GFA adjustment, because Lucerne Grand is GFA-harmonised while all the surrounding developments used in our comparison are non-GFA-harmonised.
- A lease adjustment using Bala’s Table, to estimate what each comparable’s PSF might look like if it had approximately the same remaining lease as Lucerne Grand.
These are analytical normalisations, not formal valuations. Their purpose is to make the comparison more like-for-like before we decide whether Lucerne Grand’s launch pricing looks reasonable.
The same three clusters will be used:
| Cluster | Developments | Main comparison |
| Near MRT / track-side | The Lakefront Residences, Caspian, Lakeholmz, Parc Vista | Lakeside MRT convenience with MRT-track exposure |
| MRT + lake | The Lakeshore, Lake Grande, Lakeville | MRT accessibility together with stronger Jurong Lake orientation |
| Lake / farther from MRT | The LakeGarden Residences, Sora, Lake Life | Lake-oriented living with weaker MRT proximity |
The latest market evidence shows a particularly wide pricing spectrum—from around $1,100 psf at the older Parc Vista to above $2,300 psf at Sora. But those headline PSFs aren’t directly comparable until we account for what buyers are actually receiving in usable floor area and remaining lease.
Lucerne Grand’s Starting Prices Set the Benchmark
Lucerne Grand is a 570-unit mixed-use development by City Developments Limited, directly connected to Lakeside MRT. Its first-storey commercial component, Lucerne Galleria, is planned to include a supermarket together with retail and F&B uses. The development is on a 99-year leasehold tenure commencing in September 2025.
The floor plans indicate that Lucerne Grand ranges from a 624 sq ft two-bedroom to a 1,432 sq ft four-bedroom Premium + Entertainment configuration.
The official starting prices are as follows:
| Lucerne Grand unit type | Size | Starting price | Starting PSF |
| 2 Bedroom | 624 sq ft | $1.498M | $2,401 |
| 2 Bedroom + Study | 667 sq ft | $1.598M | $2,396 |
| 3 Bedroom | 883 sq ft | $1.988M | $2,251 |
| 3 Bedroom Premium + Study | 1,001 sq ft | $2.328M | $2,326 |
| 4 Bedroom Premium | 1,152 sq ft | $2.788M | $2,420 |
| 4 Bedroom Premium + Study | 1,345 sq ft | $3.228M | $2,400 |
| 4 Bedroom Premium + Entertainment | 1,432 sq ft | $3.398M | $2,373 |
One number continues to stand out: the 883 sq ft three-bedroom has the lowest starting PSF in the project at $2,251 psf.
The two-bedroom protects the buyer’s absolute purchase quantum, but the three-bedroom gives the buyer substantially more space while entering at approximately $150 psf less.
That becomes important once we normalise the surrounding resale market.
Why Both GFA and Remaining Lease Need to Be Normalised
Two reasons make simply comparing Lucerne Grand’s $2,251 to $2,420 psf against the headline PSF of an older Lakeside condominium misleading.
The GFA difference
Lucerne Grand falls under Singapore’s harmonised floor-area regime. URA’s revised definitions apply to GLS sites launched for sale on or after 1 September 2022, and the new regime requires all strata areas to be counted as GFA while floor areas are measured using a common framework across agencies.
One practical consequence is how air-conditioning ledges are treated. Under the current rules, an A/C ledge included within the strata boundary counts as GFA, while qualifying non-strata A/C ledges may be excluded from GFA.
All of the surrounding developments used in this comparison—including The LakeGarden Residences and Sora—are non-GFA-harmonised projects. Lucerne Grand is the only GFA-harmonised development in this comparison set.
That means the stated floor areas of the older projects are not directly comparable with Lucerne Grand’s stated floor areas.
As in Part 1, we will use an illustrative 5% usable-area adjustment:
GFA-adjusted PSF = Reported PSF ÷ 0.95
For example, a non-harmonised project transacting at $1,900 psf becomes approximately $2,000 psf when expressed against an illustrative 5%-smaller comparable floor-area denominator.
This 5% assumption is deliberately a standardisation tool, not an official URA conversion factor. The actual difference varies by project and individual floor plan.
The lease difference
The second adjustment is equally important.
All of the surrounding developments in our comparison are also 99-year leasehold projects, but they started their leases at very different times.
Parc Vista‘s lease commenced in 1995, Lakeholmz‘s in 2001, The Lakeshore‘s in 2002, Caspian‘s in 2008 and The Lakefront Residences‘ in 2010.
The newer completed projects have significantly more lease remaining: Lakeville and Lake Life commenced their leases in 2013, while Lake Grande commenced in 2015.
Among the newer developments, both The LakeGarden Residences and Sora have 99-year leases commencing in 2023, placing them much closer to Lucerne Grand in terms of remaining lease.
Lucerne Grand’s lease commenced on 8 September 2025, leaving it with approximately 98 years at the time of this analysis.
This is where Bala’s Table becomes useful.
Bala’s Table expresses the value of a remaining lease as a percentage of an equivalent freehold land value. Academic research notes that the table has historically been used in Singapore’s state valuation framework for leasehold land, although its underlying assumptions should not be confused with actual condominium market pricing.
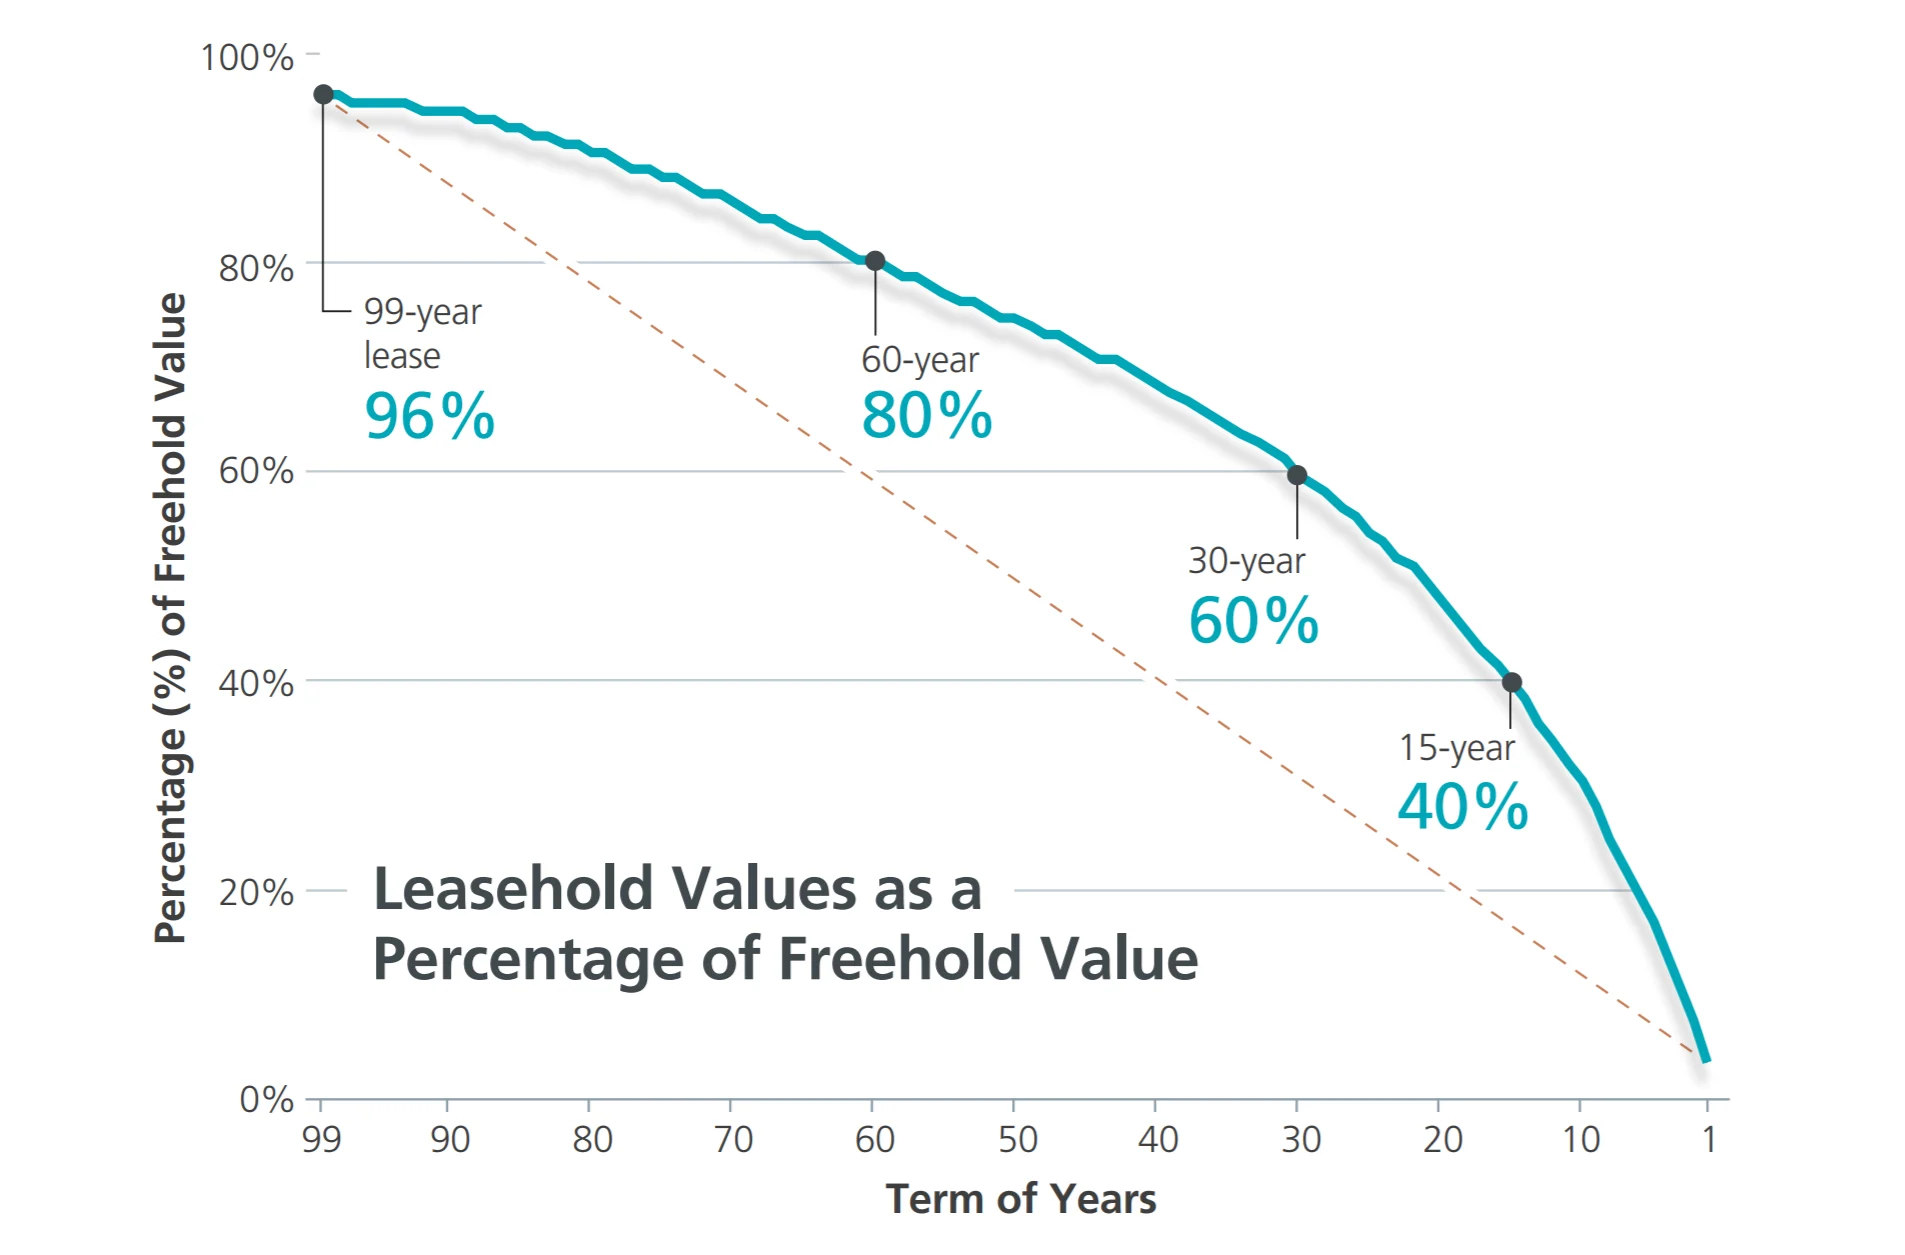
Some relevant Bala Table values are:
| Remaining lease | Bala value as % of freehold |
| 68 years | 84.5% |
| 74 years | 88.0% |
| 75 years | 88.5% |
| 81 years | 91.4% |
| 83 years | 92.2% |
| 86 years | 93.3% |
| 88 years | 94.0% |
| 96 years | 95.7% |
| 98 years | 95.9% |
| 99 years | 96.0% |
The values are derived from the leasehold table reproduced from the SLA framework; importantly, the relationship is not linear.
Because Lucerne Grand has approximately 98 years remaining, this analysis normalises each comparable to the 95.9% Bala value associated with 98 years.
The lease adjustment is:
Lease-normalised PSF = Current PSF × (95.9% ÷ Comparable’s Bala percentage)
We then apply the GFA adjustment:
Combined adjusted PSF = Lease-normalised PSF ÷ 0.95
Consider The Lakefront Residences as an example.
With about 83 years remaining, its Bala relativity is approximately 92.2%. A market PSF of $1,761 therefore becomes:
$1,761 × 95.9 ÷ 92.2 ≈ $1,832 psf
After the illustrative 5% GFA adjustment:
$1,832 ÷ 0.95 ≈ $1,928 psf
That provides a considerably more useful comparison with Lucerne Grand than simply putting $1,761 psf beside $2,401 psf.
There is an important limitation: Bala’s Table adjusts for land-lease tenure, not building age, maintenance condition, design quality or buyer preferences. A 25-year-old condominium with a hypothetically refreshed lease would still be a 25-year-old building. The adjusted figures below should therefore be read as comparison tools rather than estimates of what these developments would actually transact at with a fresh lease.
What the Adjusted Sale-Price Comparison Looks Like
To keep the market comparison current, the following table mainly uses 12-month transaction medians available through August 2026. The remaining leases are rounded to the nearest whole-year band to apply Bala’s Table.
| Cluster / Project | Current PSF | Approx. lease remaining | Bala % | Lease-normalised PSF | Lease + GFA-adjusted PSF | Market status |
| Cluster 1 | ||||||
| The Lakefront Residences | $1,761 | 83 yrs | 92.2% | $1,832 | $1,928 | Resale |
| Caspian | $1,620 | 81 yrs | 91.4% | $1,700 | $1,789 | Resale |
| Lakeholmz | $1,328 | 74 yrs | 88.0% | $1,447 | $1,523 | Resale |
| Parc Vista | $1,147 | 68 yrs | 84.5% | $1,302 | $1,370 | Resale |
| Cluster 2 | ||||||
| The Lakeshore | $1,499 | 75 yrs | 88.5% | $1,624 | $1,710 | Resale |
| Lake Grande | $1,919 | 88 yrs | 94.0% | $1,958 | $2,061 | Resale |
| Lakeville | $1,819 | 86 yrs | 93.3% | $1,870 | $1,968 | Resale |
| Cluster 3 | ||||||
| Lake Life | $1,481 | 86 yrs | 93.3% | $1,522 | $1,602 | Resale |
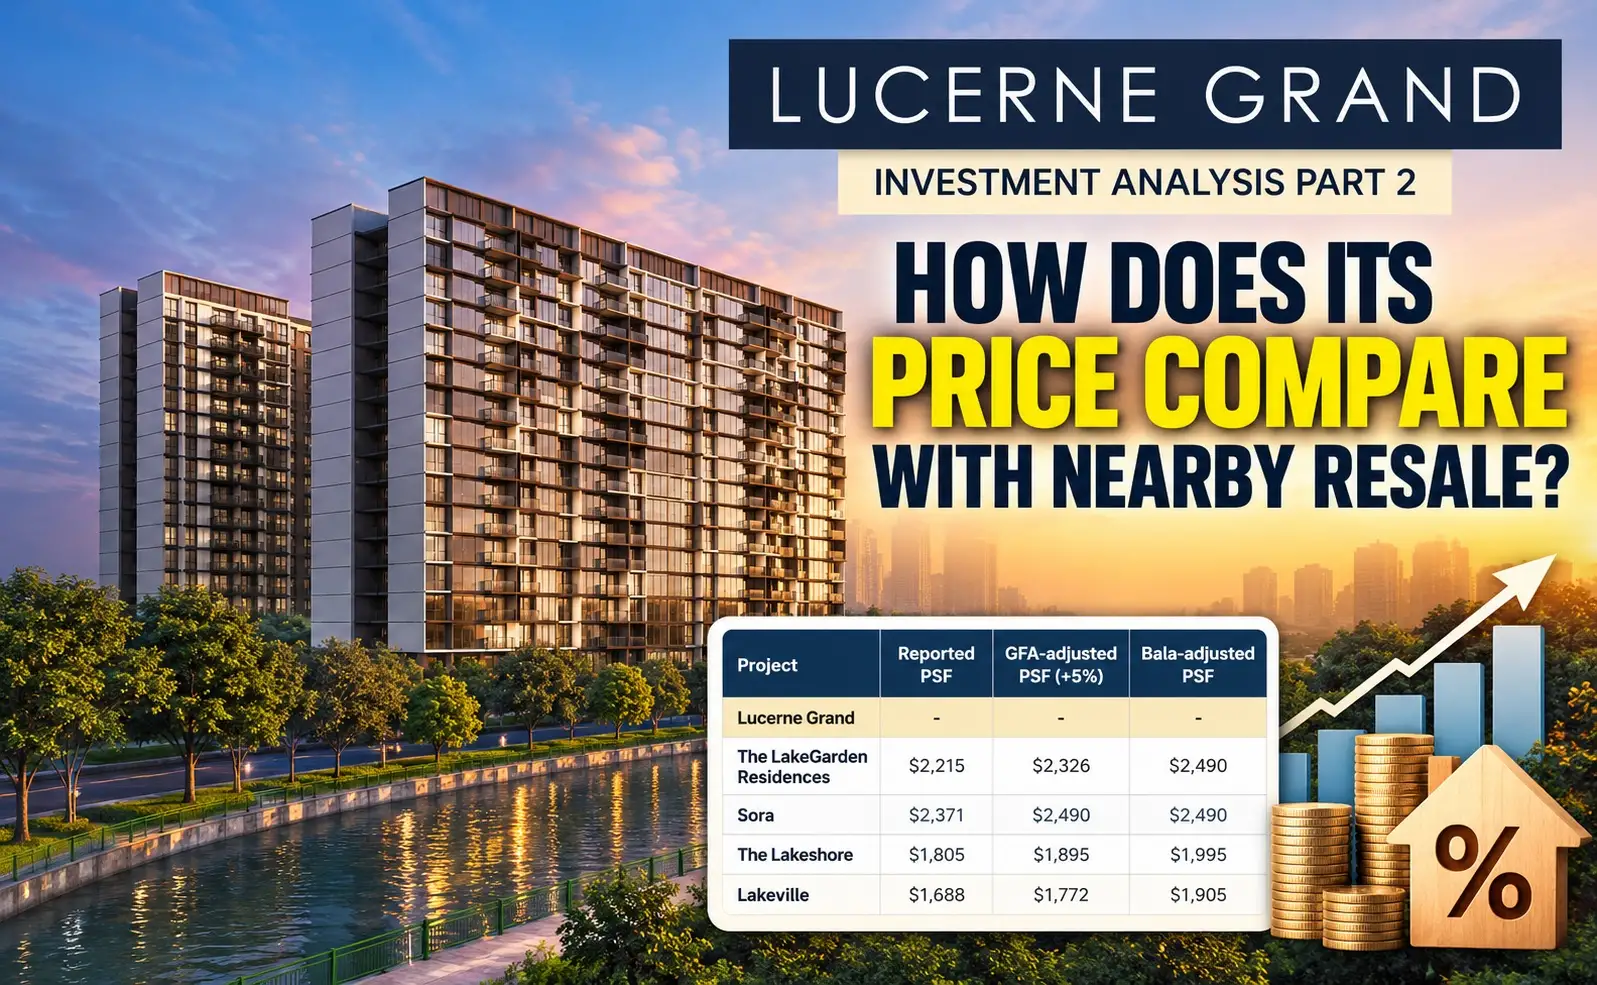
| The LakeGarden Residences | $2,222 | 96 yrs | 95.7% | $2,227 | $2,344 | New sale |
| Sora | $2,361 | 96 yrs | 95.7% | $2,366 | $2,490 | New sale |
Current Cluster 1 market data shows approximately $1,761 psf at The Lakefront Residences, $1,620 psf at Caspian, $1,328 psf at Lakeholmz, and $1,147 psf at Parc Vista. These figures are derived from recent URA caveat data extracted by PropNex Investment Suite.
Within Cluster 2, The Lakeshore is around $1,499 psf, Lake Grande around $1,919 psf and Lakeville around $1,819 psf on recent 12-month transaction evidence.
For Cluster 3, Lake Life’s latest 12-month average is approximately $1,481 psf, while The LakeGarden Residences and Sora are at approximately $2,222 and $2,361 psf, respectively. The latter two are still developer-sale markets rather than established resale markets, so they answer a slightly different question: what buyers are currently prepared to pay for relatively new Jurong Lake-area private housing.
The biggest takeaway from the adjusted table is that lease normalisation matters most for the oldest developments.
Parc Vista’s raw $1,147 psf rises to approximately $1,302 psf purely from normalising its roughly 68-year remaining lease to Lucerne Grand’s approximately 98-year position. Lakeholmz rises from $1,328 to roughly $1,447 psf on the same basis.
By contrast, lease normalisation barely changes The LakeGarden Residences or Sora because their leases are only about two years older than Lucerne Grand’s. Their Bala adjustment is only around 0.2%.
The GFA adjustment then raises all comparable figures further because every competing development in the table is not GFA-harmonised.
This significantly changes how Lucerne Grand’s premium should be interpreted.
Cluster 1 still makes Lucerne Grand look expensive. Even after adjusting for both remaining lease and GFA, The Lakefront Residences—by far the strongest Cluster 1 benchmark—comes to approximately $1,928 psf.
Against that:
| Lucerne Grand unit | Starting PSF | Premium vs adjusted Lakefront |
| 2 Bedroom | $2,401 | +24.5% |
| 3 Bedroom | $2,251 | +16.8% |
| 3 Bedroom Premium + Study | $2,326 | +20.6% |
| 4 Bedroom Premium | $2,420 | +25.5% |
So even after making a generous adjustment for both its older lease and different floor-area treatment, The Lakefront Residences remains considerably cheaper.
That tells us something important: Lucerne Grand’s price premium cannot be explained by GFA harmonisation and lease tenure alone.
The balance represents what the market is being asked to pay for a brand-new product, direct MRT connectivity, contemporary facilities, an integrated commercial component and the absence of physical depreciation associated with an older project. CDL confirms the direct Lakeside MRT connection and the supermarket, retail and F&B component within Lucerne Galleria.
Cluster 2 narrows the gap substantially.
Lake Grande’s $1,919 psf becomes approximately $2,061 psf after both lease and GFA normalisation.
That puts Lucerne Grand at:
| Lucerne Grand unit | Starting PSF | Premium vs adjusted Lake Grande |
| 2 Bedroom | $2,401 | +16.5% |
| 2 Bedroom + Study | $2,396 | +16.3% |
| 3 Bedroom | $2,251 | +9.2% |
| 3 Bedroom Premium + Study | $2,326 | +12.9% |
| 4 Bedroom Premium | $2,420 | +17.4% |
This is one of the most meaningful findings in the analysis.
Once both lease tenure and GFA treatment are considered, the 883 sq ft Lucerne Grand three-bedroom is only around 9% above Lake Grande’s adjusted project-level benchmark.
Lakeville provides another useful reference at approximately $1,968 psf after both adjustments, reinforcing the idea that Lucerne Grand’s three-bedroom carries a much more moderate premium than its raw PSF initially suggests.
Cluster 3 changes the picture again.
Because The LakeGarden Residences and Sora have almost as much lease remaining as Lucerne Grand, their lease adjustments are negligible. But both still require the GFA adjustment because they are non-harmonised.
That produces adjusted benchmarks of approximately:
The LakeGarden Residences: $2,344 psf
Sora: $2,490 psf
Against The LakeGarden Residences’ adjusted benchmark, Lucerne Grand’s entry three-bedroom at $2,251 psf is about 4% lower, while the 1,001 sq ft three-bedroom Premium + Study at $2,326 psf is roughly 1% lower. Even the $2,401 psf two-bedroom is only approximately 2% above this benchmark.
Against Sora’s adjusted benchmark of $2,490 psf, all of Lucerne Grand’s starting prices are lower on a PSF basis.
That does not automatically make Lucerne Grand cheaper or better. Sora and The LakeGarden Residences offer a different proposition, particularly for purchasers who prioritise the Jurong Lake environment and specific lake-facing units. They are also developer-sale markets rather than completed resale projects.
But they establish an important upper reference point: Lucerne Grand is not introducing an unprecedented price level for new private housing around Jurong Lake.
Absolute Purchase Quantum Still Matters More Than PSF Alone
Normalised PSF helps us compare the underlying pricing more fairly, but a future buyer does not purchase a property by paying “PSF.”
The buyer has to finance the total dollar quantum.
That is particularly important when assessing future resale liquidity.
The two-bedroom comparison
Lucerne Grand’s 624 sq ft two-bedroom starts at $1.498 million.
Recent Lake Grande transactions include:
- 624 sq ft at $1.250 million
- 614 sq ft at $1.208 million
- 614 sq ft at $1.183 million.
On headline quantum, Lucerne Grand therefore costs approximately $248,000 to $315,000 more than these recent Lake Grande compact-unit transactions.
Lakeville makes the difference even more obvious. Two 635 sq ft units transacted around $1.080 million and $1.085 million in early 2026.
However, these stated sizes should not be interpreted as exactly equivalent physical living areas because Lake Grande and Lakeville are non-GFA-harmonised whereas Lucerne Grand is harmonised.
That is the central tension of the Lucerne Grand two-bedroom.
It offers the project’s lowest absolute purchase price and should therefore have a relatively accessible future resale quantum. But at $2,401 psf, a meaningful portion of the new-project premium has already been built into the purchase price.
For an investor, this means paying a large stack or floor premium above the $1.498 million starting price deserves careful consideration.
The three-bedroom comparison
The three-bedroom comparison presents a considerably more compelling case.
A 926 sq ft Lake Grande unit transacted at approximately $1.900 million in August 2026. Lucerne Grand’s 883 sq ft three-bedroom starts at $1.988 million, a quantum difference of only around $88,000.
Lakeville also recorded a 936 sq ft transaction at approximately $1.728 million in May 2026 and a 990 sq ft unit at $1.900 million in March 2026.
So depending on the resale comparable selected, the Lucerne Grand entry three-bedroom is roughly $88,000 to $260,000 above a selection of relatively modern completed alternatives.
Again, Lucerne’s stated area is smaller, but its harmonised measurement makes the nominal square-foot difference less meaningful than it first appears.
More importantly, the buyer remains below $2 million at the published starting price.
That combination is difficult to ignore:
$1.988 million total quantum + $2,251 psf + a new lease + harmonised floor area + direct MRT connectivity.
This is why the three-bedroom stands out as one of the more attractive options for future resale within Lucerne Grand.
The four-bedroom comparison
The four-bedroom premium becomes wider again.
Lucerne Grand’s 1,152 sq ft four-bedroom Premium starts at $2.788 million.
A 1,152 sq ft Lake Grande unit sold for about $2.428 million in July 2026, leaving a difference of about $360,000.
At Lakeville, recent 1,141 sq ft transactions (May and June 2026) were approximately $2.189 million to $2.300 million, putting the difference versus Lucerne Grand at roughly $488,000 to $599,000.
The GFA and lease adjustments narrow the underlying value gap, but they cannot eliminate the difference in quantum.
This matters for resale because a $2.8 million future purchase requires a significantly stronger household balance sheet than a $2.0 million purchase.
The same issue becomes more pronounced for Lucerne Grand’s:
1,345 sq ft four-bedroom Premium + Study at $3.228 million, and 1,432 sq ft four-bedroom Premium + Entertainment at $3.398 million.
These units may offer substantial lifestyle value to owner-occupiers, but their resale thesis depends on a smaller pool of future buyers being prepared to commit more than $3 million to a Lakeside home.
Which Lucerne Grand Unit Types Look Strongest for Future Resale?
Looking only at rental yield produced one ranking. Adding resale pricing, GFA normalisation and Bala lease normalisation gives a more complete picture.
The 624 sq ft two-bedroom is still attractive because of its $1.498 million entry quantum, but its $2,401 psf starting rate is one of the highest in the development. Compared with completed resale alternatives, buyers are paying a sizeable premium in absolute dollars. Its investment strength lies primarily in affordability within Lucerne Grand itself and the convenience of having two bedrooms directly connected to an MRT station—not in being cheap compared with surrounding resale stock.
The 667 sq ft two-bedroom + Study at $1.598 million is arguably more flexible. Its $2,396 psf starting rate is virtually identical to the standard two-bedroom, so the additional $100,000 mainly buys more functional space rather than a higher PSF. For future resale, that study could broaden the unit’s usefulness to couples working from home and smaller households needing an additional flexible room.
The 883 sq ft three-bedroom remains the standout for resale value.
At $1.988 million and $2,251 psf, it has:
- the lowest starting PSF in Lucerne Grand;
- a purchase price below $2 million;
- only about a 9% premium over Lake Grande after our combined lease and GFA adjustment;
- an entry price only about $88,000 above one recent 926 sq ft Lake Grande sale; and
- a unit type that can appeal to both owner-occupiers and investors.
This does not guarantee better capital appreciation. It simply means that the buyer is starting from a relatively more favourable pricing position within Lucerne Grand.
The 1,001 sq ft three-bedroom Premium + Study at $2.328 million is also reasonably positioned on PSF. Its $2,326 psf starting rate is actually marginally below our approximately $2,344 psf combined benchmark for The LakeGarden Residences and well below Sora’s approximately $2,490 psf benchmark.
Its weakness is not PSF—it is quantum.
Moving from $1.988 million to $2.328 million requires approximately $340,000 more capital. A future buyer therefore needs to value the larger layout and study sufficiently to justify crossing well above the $2 million mark.
For a long-term owner-occupier, that can be sensible. For an investor prioritising eventual liquidity, the standard three-bedroom is arguably more straightforward.
The 1,152 sq ft four-bedroom Premium looks reasonable on adjusted PSF but less attractive on quantum.
At $2,420 psf, it is only about 3% above the adjusted LakeGarden benchmark and slightly below adjusted Sora. Yet it is still nearly $2.8 million in absolute price.
That distinction highlights why project-level PSF alone can be dangerous.
A property may appear fairly priced per square foot but still face a narrower resale market simply because the total quantum is large.
The 1,345- and 1,432-sq-ft four-bedroom configurations require even greater conviction. Their $2,400 and $2,373 psf entry rates are actually lower than the smaller four-bedroom on a PSF basis, so buyers are not being heavily penalised per square foot for choosing more space.
But with purchase prices of $3.228 million and $3.398 million, the investment thesis becomes increasingly dependent on long-term owner-occupier demand and capital appreciation rather than broad resale affordability.
A useful way to summarise the relative positioning is:
| Lucerne Grand unit | Starting price | Starting PSF | Pricing position | Resale perspective |
| 2BR, 624 sq ft | $1.498M | $2,401 | High PSF, lowest quantum | Good liquidity potential, but substantial resale premium |
| 2BR + Study, 667 sq ft | $1.598M | $2,396 | Similar PSF to 2BR | Added flexibility for modest extra quantum |
| 3BR, 883 sq ft | $1.988M | $2,251 | Lowest PSF | Strongest overall pricing position |
| 3BR Premium + Study, 1,001 sq ft | $2.328M | $2,326 | Competitive vs newer lake projects | Good value per sq ft, smaller buyer pool |
| 4BR Premium, 1,152 sq ft | $2.788M | $2,420 | Fair vs new-project benchmarks | Higher exit quantum |
| 4BR Premium + Study, 1,345 sq ft | $3.228M | $2,400 | More space without PSF penalty | Needs stronger affluent-buyer demand |
| 4BR Premium + Entertainment, 1,432 sq ft | $3.398M | $2,373 | Lower PSF despite largest size | Most dependent on own-stay/capital-growth thesis |
The crucial distinction is that “cheap PSF” and “easy resale” are not the same thing.
Lucerne Grand’s largest homes offer more space at slightly lower PSFs, but the $3 million-plus price tag limits the number of households that can buy them.
The 883 sq ft three-bedroom sits in a particularly useful middle ground: it provides a family-oriented layout while keeping the starting price below $2 million.
Part 2 Conclusion: Does Lucerne Grand’s Launch Price Make Sense?
Once both GFA harmonisation and remaining lease are taken into account, Lucerne Grand’s pricing appears more competitive than the headline PSF figures alone might suggest.
That does not mean every unit is inexpensive.
Against the older MRT cluster, Lucerne Grand still carries a significant premium.
After normalising The Lakefront Residences for both its shorter remaining lease and our illustrative GFA difference, its benchmark rises from around $1,761 psf to approximately $1,928 psf. Lucerne Grand’s units still start roughly 17% to 26% above that level depending on unit type.
The gap therefore cannot be dismissed as a measurement issue. Buyers are genuinely paying more for Lucerne Grand.
But Cluster 2 tells a more encouraging story.
Lake Grande’s raw $1,919 psf becomes approximately $2,061 psf after our two adjustments. That brings Lucerne Grand’s 883 sq ft three-bedroom to only around a 9% premium.
That is a considerably smaller difference for buyers to bridge through the advantages of a newer project, a much newer lease and direct Lakeside MRT connectivity.
Cluster 3 is perhaps the most revealing.
Once The LakeGarden Residences and Sora are correctly treated as non-GFA-harmonised projects and adjusted on the same basis as every other comparable, their indicative benchmarks become approximately $2,344 psf and $2,490 psf respectively.
Their lease adjustment is minimal because both have around 96 years remaining, but their GFA adjustment remains relevant.
On this basis:
- Lucerne Grand’s $2,251 psf three-bedroom is below both benchmarks.
- Its $2,326 psf three-bedroom Premium + Study is slightly below adjusted LakeGarden and comfortably below adjusted Sora.
- Its $2,401 psf two-bedroom sits between the two.
- Even the $2,420 psf four-bedroom Premium remains below adjusted Sora.
The implication is not that Lucerne Grand is objectively cheap.
It is that its pricing sits within a range that the latest generation of Jurong Lake-area projects has already begun to establish, while offering a substantially stronger MRT proposition than the Cluster 3 developments. The LakeGarden Residences and Sora are still new-sale markets, however, and should not be treated as substitutes for an established resale track record.
The Bala adjustment also changes how we should view the much older projects.
Parc Vista at roughly $1,147 psf appears extraordinarily cheap beside Lucerne Grand. But after bringing its approximately 68-year remaining lease to Lucerne Grand’s 98-year basis, it rises to roughly $1,302 psf before GFA adjustment and around $1,370 psf after both adjustments. It remains far cheaper—but the difference is no longer being distorted entirely by lease decay.
That is ultimately what the normalisation exercise is intended to achieve.
We are not trying to turn Parc Vista into a new condominium or pretend Lake Grande has a fresh lease.
We are asking:
How much of Lucerne Grand’s price premium comes from having more lease, how much comes from GFA harmonisation, and how much is the buyer genuinely paying for a newer and better-located product?
After stripping out those first two factors, Lucerne Grand still commands a premium over the completed resale market.
But that premium varies substantially by unit type.
The 624 sq ft two-bedroom remains attractive for its low absolute entry point, although buyers are paying a sizeable premium over completed compact units.
The 883 sq ft three-bedroom stands out most strongly. Its $1.988 million starting quantum remains below $2 million, its $2,251 psf is the lowest in the development, and after adjusting Lake Grande for both remaining lease and GFA treatment, the pricing gap is only around 9%.
The 1,001 sq ft three-bedroom Premium + Study also looks reasonable on a PSF basis, particularly against newer lake-oriented developments, although its $2.328 million quantum reduces the eventual buyer pool.
The four-bedroom configurations are less straightforward. Their PSFs are not excessive relative to the latest new-project benchmarks, but their $2.8 million to $3.4 million purchase prices mean future performance will increasingly depend on affluent family demand and long-term capital appreciation.
So rather than asking:
“Is $2,400 psf at Lakeside expensive?”
A more useful question is:
“After adjusting for usable floor area and remaining lease, how much premium am I actually paying—and will a future buyer still find the total purchase quantum attractive?”
On those measures, the 883 sq ft three-bedroom appears to offer the strongest balance between entry price, adjusted market premium and future resale liquidity within Lucerne Grand.
Disclaimer: The lease-normalised figures in this article use Bala’s Table solely to standardise analysis. Bala’s Table expresses leasehold land value as a percentage of freehold land value and is not a prediction of condominium transaction prices. Actual resale values are also affected by building age, physical condition, floor, orientation, view, layout, renovations, supply, interest rates, financing rules and prevailing buyer demand.
The GFA-adjusted figures assume an illustrative 5% difference in comparable floor-area denominator between Lucerne Grand and the non-harmonised projects. This is not an official URA adjustment factor and will differ across individual floor plans. URA’s harmonised rules treat strata area and A/C ledges differently, but they do not prescribe a universal percentage for comparing old and new condominium layouts.
Market PSFs are recent project-level transaction medians and should not be interpreted as valuations for a particular unit. The LakeGarden Residences and Sora remain developer-sale, not established resale, markets. Starting prices at Lucerne Grand apply to selected units and actual prices may differ according to floor, stack, orientation and availability.
This article is for general information and educational purposes only and does not constitute financial, investment, legal, tax or property advice. Buyers should review the specific unit’s floor plan, strata area, price, financing requirements and prevailing transaction data before making a purchase decision.
Article contributed by Jerry Wong.

Jerry Wong is a realtor at Propnex Realty, bringing a rich background in interior and lighting design to his work. He loves exploring diverse spaces and observing the transformative power of real estate. Beyond his professional role, Jerry finds his greatest fulfillment in connecting people with the right properties, gaining immense satisfaction from helping clients achieve their dreams.