
Singapore’s new private home sales recovered in September 2026, but the improvement should be read alongside a weaker quarterly performance and uneven demand across developments.
Developers sold 296 private homes excluding executive condominiums, up 93.5% from August’s 153 units and 16.1% above September 2025, according to Realion’s analysis of URA figures.
The subsequent launch of The Serra Residences adds useful context. Its early sales show that buyers are willing to commit, including to larger and more expensive homes. However, demand varies considerably between layouts.
Taken together, the results suggest a market in which purchasing activity continues, but developers still need to offer a compelling combination of price, space and functionality.
September’s Rebound Did Not Reverse the Quarterly Slowdown
September’s near-doubling added 143 sales. The increase was meaningful, although the percentage was amplified by August’s low base.
Across Q3, developers sold 1,180 homes, down 44.9% from 2,141 in Q2. The Business Times reported that this was the steepest third-quarter decline in 13 years, citing Mogul.sg chief research officer Nicholas Mak. This refers to the quarterly decline, rather than sales reaching a 13-year low.
A stronger September therefore did not erase the preceding slowdown. Equally, the quarterly contraction should not automatically be interpreted as buyers withdrawing from the market: launch timing and the availability of suitable homes also influence transaction volumes.
Existing Projects Helped Drive the Improvement
Developers released only 158 units in September, while previously launched projects helped support sales. Buyers could purchase stock introduced in earlier months, so sales exceeding fresh releases do not represent a take-up rate above 100%.
This makes performance at existing developments particularly informative. These projects compete against both other unsold homes and upcoming launches, giving buyers time to compare their options.
ERA reported that Terra Hill’s sales rose from four in August to 32 in September, while The Sen’s increased from 12 to 25. Their combined increase of 41 units accounted for approximately 28.7% of the market’s monthly gain.
That does not mean the entire rebound depended on two projects. It does show how individual developments can contribute substantially to an improving headline figure.
The Serra Residences Reveals Uneven Demand Across Unit Types
The Serra Residences provides an October example of variation within a single project. Following its 16 October launch, 25 of 133 homes were sold as at 18 October, or 18.8% of total inventory.
| Standard unit category | Sold / total | Take-up |
|---|---|---|
| Two-bedroom plus study | 9 / 39 | 23.1% |
| Three-bedroom | 2 / 39 | 5.1% |
| Four-bedroom | 7 / 13 | 53.8% |
The standard four-bedroom homes led despite their higher purchase price. At Level 4, the quoted 958 sq ft four-bedroom cost approximately S$3.076 million—S$128,570, or 4.4%, above the 904 sq ft three-bedroom.
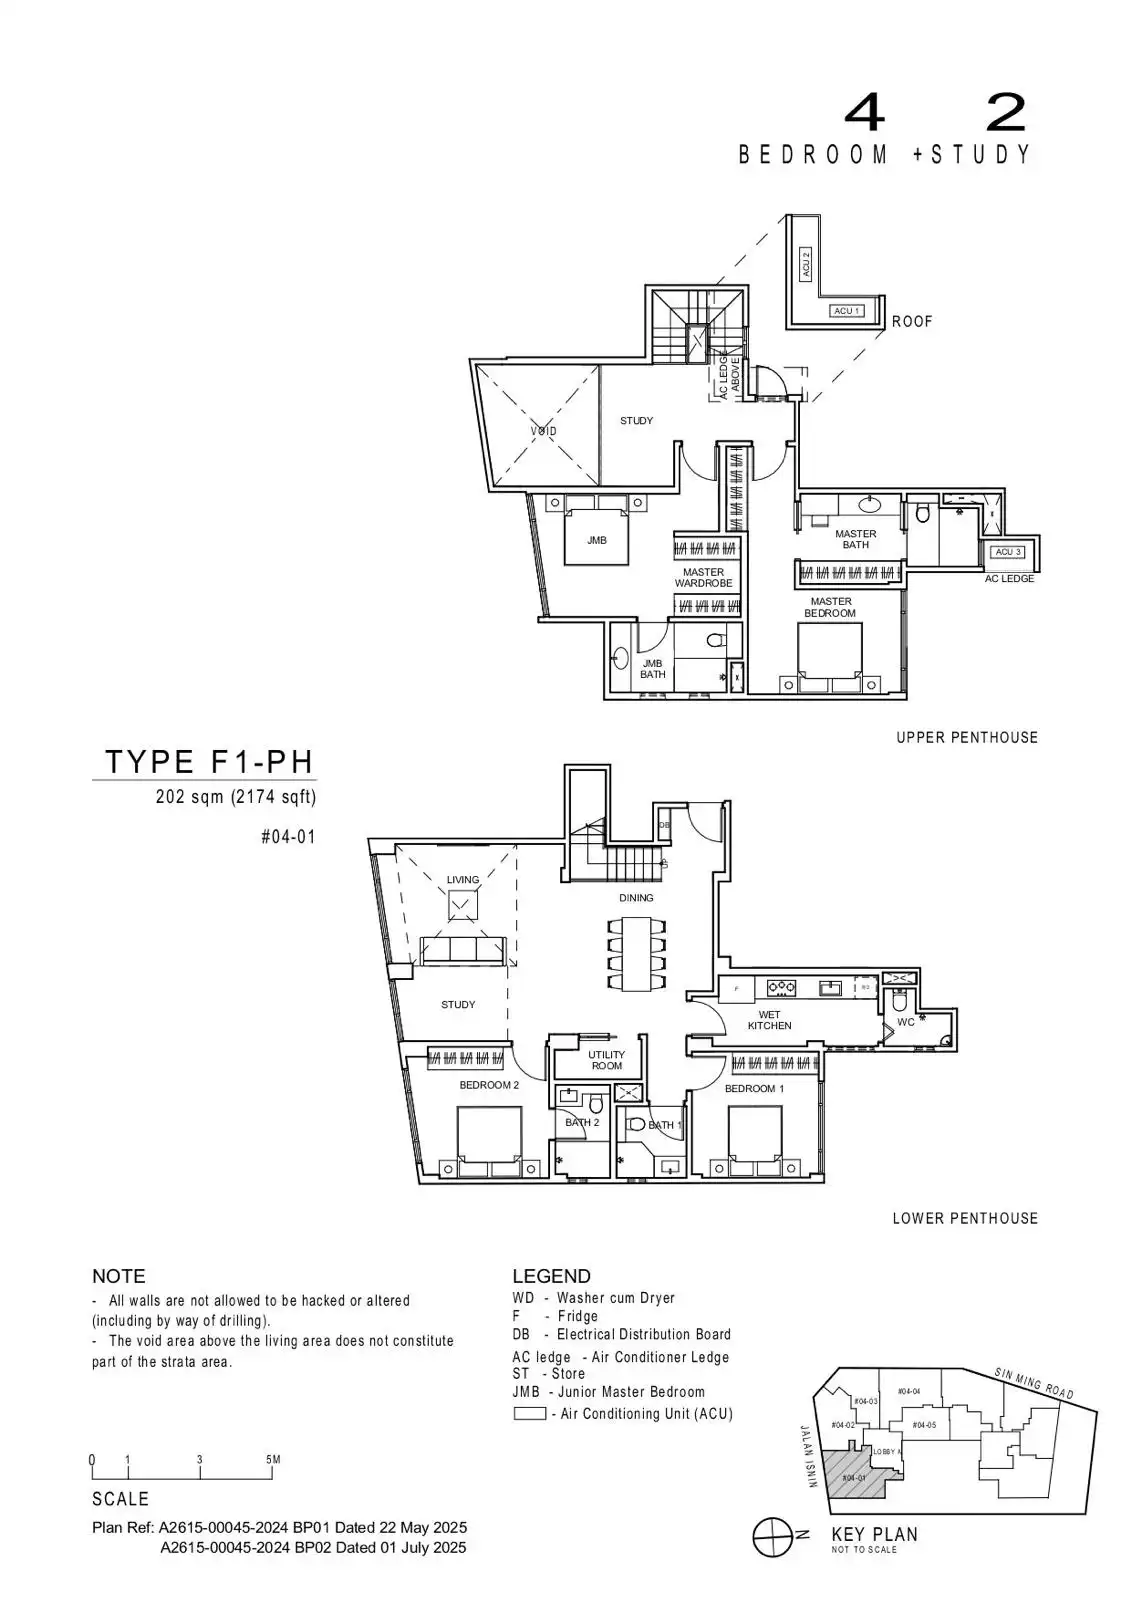
The Summit also recorded seven sales, including four premium four-bedroom homes and one penthouse. These are early inventory figures; the quoted prices are asking prices, not confirmed transaction prices.
The result suggests that some buyers valued the additional room enough to accept a higher budget. It does not establish their motivations, and differences in outlook and positioning also matter.
Crucially, 18.8% overall take-up and 53.8% within one category describe different aspects of the same launch. Neither alone captures its response.
Buyers Are Comparing Value Beyond the Lowest Price
This changes how we should frame the wider recovery question. Selectivity operates at several levels: between locations, between developments and between apartments within the same building.
A buyer may reject one unit while purchasing another at a higher price because the second better meets a household need. Price sensitivity does not necessarily mean choosing the cheapest available home. It can mean demanding a clearer benefit for each additional dollar spent.
September’s transaction mix reinforces the need to separate spending from price inflation. ERA’s caveat analysis found that 38.8% of new non-landed purchases were below S$2.5 million, down from 60.3% in August. It attributed part of the shift to stronger purchases of larger apartments.
A greater proportion of expensive transactions does not prove that comparable homes became more expensive. Larger apartments can raise the overall transaction-value profile without increasing the price of an equivalent unit.
Nor can October’s Serra results explain September’s figures retrospectively. They serve as a subsequent example of how demand can favour particular housing configurations rather than move uniformly across the market.
Regional Sales Totals Tell Only Part of the Story
Geography alone is also insufficient. September sales comprised 131 units in the Rest of Central Region, 125 in the Outside Central Region and 40 in the Core Central Region.
Those totals describe where purchases occurred. Without considering available stock and unit mix, they cannot establish which region had the strongest underlying demand.
Thomson Reserve Will Provide the Next Test
Thomson Reserve remains another important test, with booking scheduled for 31 October. Its much larger 1,268-unit inventory means its eventual sales count should be assessed alongside the proportion sold and the distribution of purchases across layouts.
The useful comparison with Serra will extend beyond freehold versus leasehold or the lowest advertised entry price. It should examine whether purchases spread across several categories, whether buyers accept higher budgets for additional utility, and whether sales continue after the initial launch period.
A stronger market recovery would involve sustained purchases across more projects and unit types. A rise concentrated in selected layouts would still be commercially meaningful, but would offer narrower evidence of improving demand.
What This Means for Buyers
For prospective buyers, the practical lesson is to look beyond both the national growth rate and a development’s overall take-up. Compare the apartment with closely priced alternatives: usable space, room dimensions, bathrooms, storage, outlook, and the added cost of moving to another layout.
September showed that sales could recover from a quiet month. The Serra Residences now adds a more specific observation: buyers remain willing to spend, but their choices can differ sharply—even within the same development.
Disclaimer: This article is for general information and does not constitute financial, investment or legal advice. Market figures reflect September 2026 data, while The Serra Residences’ sales and quoted prices are based on information available as at 18 October 2026. Figures may be revised, and prices and availability are subject to change. Asking prices may differ from actual transaction prices. Observations about buyer preferences are interpretations of early sales patterns, rather than confirmed purchaser motivations. Early take-up and past performance do not guarantee future demand, price appreciation or investment returns. Readers should verify current information with the relevant authorities, developers or appointed marketing agents and seek independent professional advice before making property decisions.

Jerry Wong is a realtor at Propnex Realty, bringing a rich background in interior and lighting design to his work. He loves exploring diverse spaces and observing the transformative power of real estate. Beyond his professional role, Jerry finds his greatest fulfillment in connecting people with the right properties, gaining immense satisfaction from helping clients achieve their dreams.
Let’s Discuss Your Property Plans
Interested in This Property?
Buying, selling or renting? Get a free consultation with realtors with a background in interior and lighting design. We’ll discuss your goals and help you assess your options—from pricing and timelines to layout practicality and space potential.
Share your contact details below, and we will get in touch to understand your needs and suggest the next steps. No pressure. No obligation to proceed.