Chuan Grove GLS: A Benchmark Land Bid That Could Reset Lorong Chuan Pricing
The Chuan Grove GLS parcel won by Sing Holdings Residential Pte. Ltd. and Sunway Developments Pte. Ltd. is, in our view, a high-conviction land buy rather than a routine bid. The tender annex and URA award notice show that a 99-year residential site with 15,831.5 sq m of land area, a maximum permissible GFA of 47,495 sq m, and a winning price of S$703.6 million, or S$14,814.19 per sq m of GFA.

Translated into the market’s language, that works out to about S$1,376.3 psf ppr. Based on public analyst commentary after the tender, the most defensible future launch range for this first parcel is roughly S$2,700 to S$2,800 psf, while CBRE’s view for the combined two Chuan Grove parcels is S$2,750 to S$2,850 psf if the sites are amalgamated. Our working base case is therefore S$2,750 psf, with a realistic range of S$2,700 to S$2,850 psf depending on whether the project is launched as a standalone parcel or as part of the later merged site.
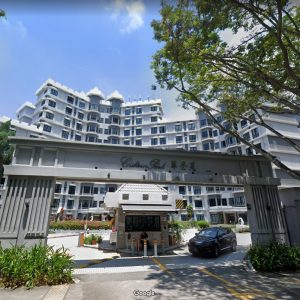
That has a very specific implication for the nearby comparables. It suggests Chuan Grove is not a drastic step change above Chuan Park, which is already trading in the mid-S$2,600 psf range, but it is a major premium over the five resale projects we selected. The premium is likely to be most supportive for Goldenhill Park Condominium and The Chuan, somewhat supportive for The Scala, and more limited for the older 99-year projects Chiltern Park and The Springbloom, which are more likely to act as “value alternatives” than true price peers.
Tender economics
The land math is straightforward. Using the official tender price and maximum permissible GFA, the winning consortium paid:
S$703,600,000 / 47,495 sq m of GFA = S$14,814.19 psm of GFA
Converted into square feet, that becomes:
S$703,600,000 / 511,231 sq ft of GFA = about S$1,376.3 psf ppr.
The same data also implies a gross plot ratio of roughly 3.0, because 47,495 / 15,831.5 = 3.0000. URA notes that the gross plot ratio governs the development potential of a residential site, with the Master Plan GPR serving as the upper limit of allowable intensity. That matters here because URA’s zoning is consistent with a parcel that is more intense than several of its immediate surroundings, which helps explain why the site can support a larger, denser, more mass-market product than the older nearby condos.

The bid was also strong relative to competing developers. The attached annex shows seven bids, with the winner at S$703.6 million versus S$655.5 million from CDL in second place; that is a premium of roughly 7.3% over the next bidder. With this pricing, the land rate sets a benchmark for District 19 and places the site just below the Bayshore Road OCR benchmark, while even exceeding the Toa Payoh Lorong 1 land rate, despite Chuan Grove being in the OCR. That is not what you see when developers are cautious about a micro-market.
At this pricing, the land rate effectively sets a new benchmark for District 19. It sits just below the Bayshore Road OCR benchmark, yet exceeds the Toa Payoh Lorong 1 land rate even though Chuan Grove is located in the OCR. This level of bidding suggests that developers are not taking a cautious view of the Lorong Chuan micro-market; instead, they appear to be underwriting strong confidence in its future demand and pricing power.
Location quality is a key reason behind that confidence. The Chuan Grove parcel is within 400m of Lorong Chuan MRT, with Bishan and Serangoon interchange stations just one stop away. It is also close to lifestyle and retail amenities such as New Tech Park, Junction 8 and NEX, as well as established schools in the surrounding neighbourhood.
Another important point is supply scarcity. This is the first GLS site in the area since The Scala was awarded in 2009. In other words, Lorong Chuan had gone many years without a fresh GLS supply before Chuan Park and the Chuan Grove plots brought new development activity back into the micro-market.

Likely future launch pricing
Because no final unit mix or approved launch price has been published yet, the cleanest way to estimate the future selling price is to triangulate between the land rate, nearby new-launch evidence, and public analyst commentary. The public range that appears most consistently in credible commentary is:
- around S$2,700 psf to start or average above S$2,700 psf for the first Chuan Grove parcel; and
- around S$2,750 psf to S$2,850 psf average if the two Chuan Grove parcels are amalgamated into one larger project.
That range also makes sense in relation to the land rate. A launch at S$2,700 psf implies a land-to-launch multiple of about 1.96x; S$2,750 psf is almost exactly 2.00x the land rate; and S$2,850 psf implies about 2.07x. For a mass-market condo in a tested MRT-adjacent location, that is a believable conversion from land cost to selling psf once one factors in construction, financing, professional fees, marketing, taxes, and target margin.
A second nuance matters here. In September 2025, the same joint venture won the adjacent second Chuan Grove parcel, and Sing Holdings’ SGX filing said the two sites may be amalgamated into around 1,055 units across five blocks of up to 27 storeys, with a blended land cost of about S$1,355 psf of total gross floor area. So if the merger happens, the first parcel’s aggressive land bid is partially diluted by the cheaper second parcel, which is one reason we would use S$2,750 psf as the centre of gravity rather than immediately assuming S$2,900-plus.
Indicative Quantum Table
For practical budgeting, the indicative quantum table below provides a useful way to translate the projected psf range into estimated purchase prices.
We have used 750 sq ft, 850 sq ft, 1,200 sq ft, and 1,500 sq ft as proxy unit sizes for the calculation. These sizes are broadly in line with nearby Chuan Park, where 2-bedroom units range from around 700 to 883 sq ft, 3-bedroom units from about 936 to 1,507 sq ft, and 4-bedroom units from approximately 1,335 to 1,679 sq ft. This makes the examples realistic neighbourhood references rather than abstract assumptions.
As the Chuan Grove GLS site falls under the new Government Land Sales framework and is subject to GFA harmonisation, the quantum calculation should be based on the harmonised unit size. Simply put, the indicative purchase quantum is derived by multiplying the harmonised floor area by the estimated selling price per square foot.
| GFA Harmonised Size | Proxy size (~6% Adjusted) | At S$2,700 psf | At S$2,750 psf | At S$2,850 psf |
| 705 sq ft | 750 sq ft | S$1.904M | S$1.939M | S$2.009M |
| 799 sq ft | 850 sq ft | S$2.157M | S$2.197M | S$2.277M |
| 1,128 sq ft | 1,200 sq ft | S$3.045M | S$3.102M | S$3.214M |
| 1,410 sq ft | 1,500 sq ft | S$3.807M | S$3.878M | S$4.018M |
Those indicative quantums are important because a 3.0 plot-ratio parcel usually gives the developer more flexibility to manage absolute buyer quantum through efficient layouts. In other words, the site can be more expensive on a psf basis without becoming impossible to clear in a family-oriented, upgrader-heavy market. That is one of the reasons a mid-to-high S$2,700s psf launch is plausible here.
Nearby benchmarks
Chuan Park is the immediate benchmark that cannot be ignored. Launched on 10 November 2024, the 99-year leasehold project comprises 916 units and is expected to TOP in 2028. As of 4 May 2026, it is 94% sold, with 55 units remaining. Indicative prices currently range from about S$2,349 to S$2,672 psf, with average sale prices of S$2,596 psf.
EdgeProp also reported that Chuan Park sold 76% of its units during its launch weekend at an average price of S$2,579 psf. In simple terms, Chuan Park has already reset the Lorong Chuan micro-market into the mid-S$2,500 psf range.
For the five selected resale comparables, we use the PropNex Trend quarterly chart as the latest relevant benchmark. For the resale projects, the comparison is based on their average sale psf in Q4 2025 and Q1 2026. For Chuan Park, however, we use the current project average sale price shown on its project page, as it remains an active new-launch benchmark rather than a completed resale development.


| Project | Tenure | TOP | Units | Q4 2025 | Q1 2026 | Average Latest PSF |
| The Chuan | 999-year | 2008 | 106 | – | S$2,130 psf | S$2,130 psf |
| Chiltern Park | 99-year | 1995 | 500 | S$1,514 psf | S$1,602 psf | S$1,558 psf |
| The Springbloom | 99-year | 1999 | 372 | S$1,700 psf | S$,1620 psf | S$1,660 psf |
| Goldenhill Park Condominium | Freehold | 2004 | 390 | S$2,270 psf | S$2,513 psf | S$2,391 psf |
| The Scala | 99-year | 2013 | 468 | S$1,960 psf | S$1,878 psf | S$1,919 psf |
| Chuan Park | 99-year | 2028 | 916 | S$2,681 psf | S$2,642 psf | S$2,661 psf |
This table is the key to the whole exercise. It shows that the area already has a clear price ladder: Chuan Park at mid-S$2,600 psf; Goldenhill above S$2,300; The Chuan around S$2,100; The Scala around S$1,919; and the older 1990s 99-year stock around S$1,600. A future Chuan Grove launch in the S$2,700 to S$2,850 psf zone would therefore extend that price ladder rather than create one from scratch.
Premiums and spillover effects
Using S$2,750 psf as the working base case, Chuan Grove would launch at roughly 3.0% above Chuan Park, 15% above Goldenhill Park, 29.1% above The Chuan, 43.3% above The Scala, 65.7% above The Springbloom, and 76.5% above Chiltern Park. That is the most useful single snapshot of the likely premium structure.
The key conclusion is that Chuan Park remains the real competitive reference point, not the older resale stock.
If Chuan Grove launches around S$2,700 to S$2,850 psf, the headline premium to Chuan Park may appear modest. However, after factoring in GFA harmonisation, the effective pricing becomes even closer to a level that the market has already accepted through Chuan Park’s sales performance.
As such, Chuan Grove is no longer simply a large step-up from existing resale prices; it is more accurately viewed as a continuation of the new pricing benchmark already established in Lorong Chuan.
By contrast, the premium over the older 1990s 99-year leasehold projects remains substantial. Developments such as Chiltern Park and The Springbloom are therefore more likely to serve as affordability alternatives rather than direct price anchors for Chuan Grove.
That also tells you where the spillover benefits are likely to be strongest. Goldenhill Park Condominium should be one of the clearest beneficiaries because it is already trading above the rest of the resale pack, it is freehold, and it sits in the same walkable Lorong Chuan orbit. A new 99-year launch at roughly S$2,750 psf makes a low-to-mid S$2,300s psf freehold condo look relatively defensible. The Chuan should also benefit because a 999-year boutique project at around S$2,100 psf can be repositioned psychologically as an alternative to a much more expensive new 99-year launch, even if its smaller size means price discovery is less smooth. This is our inference based on tenure, price gaps, and location.
The Scala sits in the middle. It is newer than Chiltern and Springbloom, still 99-year, and historically the closest modern benchmark in the area. A future Chuan Grove launch around S$2,750 psf leaves a large but not impossible gap to The Scala’s current sub-S$2,000 psf level. That usually creates some positive spillover, but not enough for full convergence, because buyers still know they are comparing a 2013 project with a brand-new scheme.
Chiltern Park and The Springbloom should benefit the least on a pure psf convergence basis. Their current levels around S$1,590 to S$1,621 psf are simply too far below a high-S$2,700s launch for them to re-price one-for-one. What they are more likely to gain is demand overflow from buyers who want this micro-location but cannot accept Chuan Grove or Chuan Park quantum. In other words, they benefit more from being the area’s “budget entry points” than from becoming true peers of the new launch.
There is, however, an important cap on upside. Because the same JV later won the second adjacent Chuan Grove GLS parcel and told SGX it may amalgamate the two sites into a 1,055-unit scheme, the area is not just getting a new benchmark; it is also getting substantial future supply. That future supply supports valuation by proving developer confidence, but it also limits how far surrounding resale projects can run before buyers simply switch to the new inventory.
A final caution is policy-driven. IRAS states that for residential property acquired on or after 4 July 2025, the Seller’s Stamp Duty holding period increased from three to four years and SSD rates were raised. Notably, the Chuan Grove tender still drew strong bids immediately after those anti-speculative changes, which suggests demand is likely to be fundamentally owner-occupier and upgrader-led rather than purely flip-driven. For surrounding resale projects, that usually means slower but more durable spillover support.
If we had to anchor the analysis to one headline figure, we would use about S$2,750 psf as the most balanced estimate for the future Chuan Grove project. A realistic pricing range would be S$2,700 to S$2,850 psf, depending on launch timing, whether the two Chuan Grove GLS parcels are eventually amalgamated, and how much remaining Chuan Park inventory is still available when Chuan Grove enters the market.
This estimate sits comfortably within public analyst expectations, aligns with the roughly 2.0x land-to-launch price multiple implied by the winning land rate, and represents only a measured premium over the pricing benchmark that Chuan Park has already established.
For the nearby projects selected in this study, the pricing impact is likely to be selective rather than uniform. Chuan Park remains the most important immediate comparison and likely ceiling reference. Goldenhill Park Condominium and The Chuan should receive the strongest narrative support, as their freehold and 999-year tenure profiles set them apart from a new 99-year launch. The Scala should see moderate support as the newer resale alternative in the area. Meanwhile, The Springbloom and Chiltern Park are more likely to benefit as affordable entry options rather than projects that will fully close the price gap with the new benchmark.
The simpler way to understand Chuan Grove is this: it reinforces Lorong Chuan as a mid-to-high S$2,000 psf new-launch market, but it does not mean every nearby resale project should trade at the same level immediately. Instead, it strengthens a tiered micro-market, with Chuan Grove likely at the top, Chuan Park just below, tenure-advantaged resale projects forming the next layer, and older 99-year projects remaining as value plays.
Disclaimer: This blog post is for general information only and does not constitute financial, investment, legal, tax, or property advice. Pricing estimates and market views are based on available information and assumptions at the time of writing, and may change.
Article contributed by Jerry Wong.

Jerry Wong is a realtor at Propnex Realty, bringing a rich background in interior and lighting design to his work. He loves exploring diverse spaces and observing the transformative power of real estate. Beyond his professional role, Jerry finds his greatest fulfillment in connecting people with the right properties, gaining immense satisfaction from helping clients achieve their dreams.