
Lucerne Grand’s sales launch on 3 October 2026 provides a useful test of what buyers will pay for a new home beside Lakeside MRT.
A total of 353 of Lucerne Grand’s 570 homes—61.9%—were sold. This points to a strong initial response, but the sales breakdown by unit type, facing and floor reveals where buyer demand was strongest.
Buyers strongly preferred stacks facing Lakeside Drive, with nearly all units along this frontage sold. Two-bedroom homes also performed strongly on the track-facing side, while standard four-bedroom units achieved the highest category selection rate. The larger two-bedroom-plus-study layouts and biggest four-bedroom configurations attracted some purchases, but their response remained considerably lesser.
Overall, demand was meaningful across several buyer budgets, with clear limits on what purchasers were willing to pay for extra space or a preferred position.
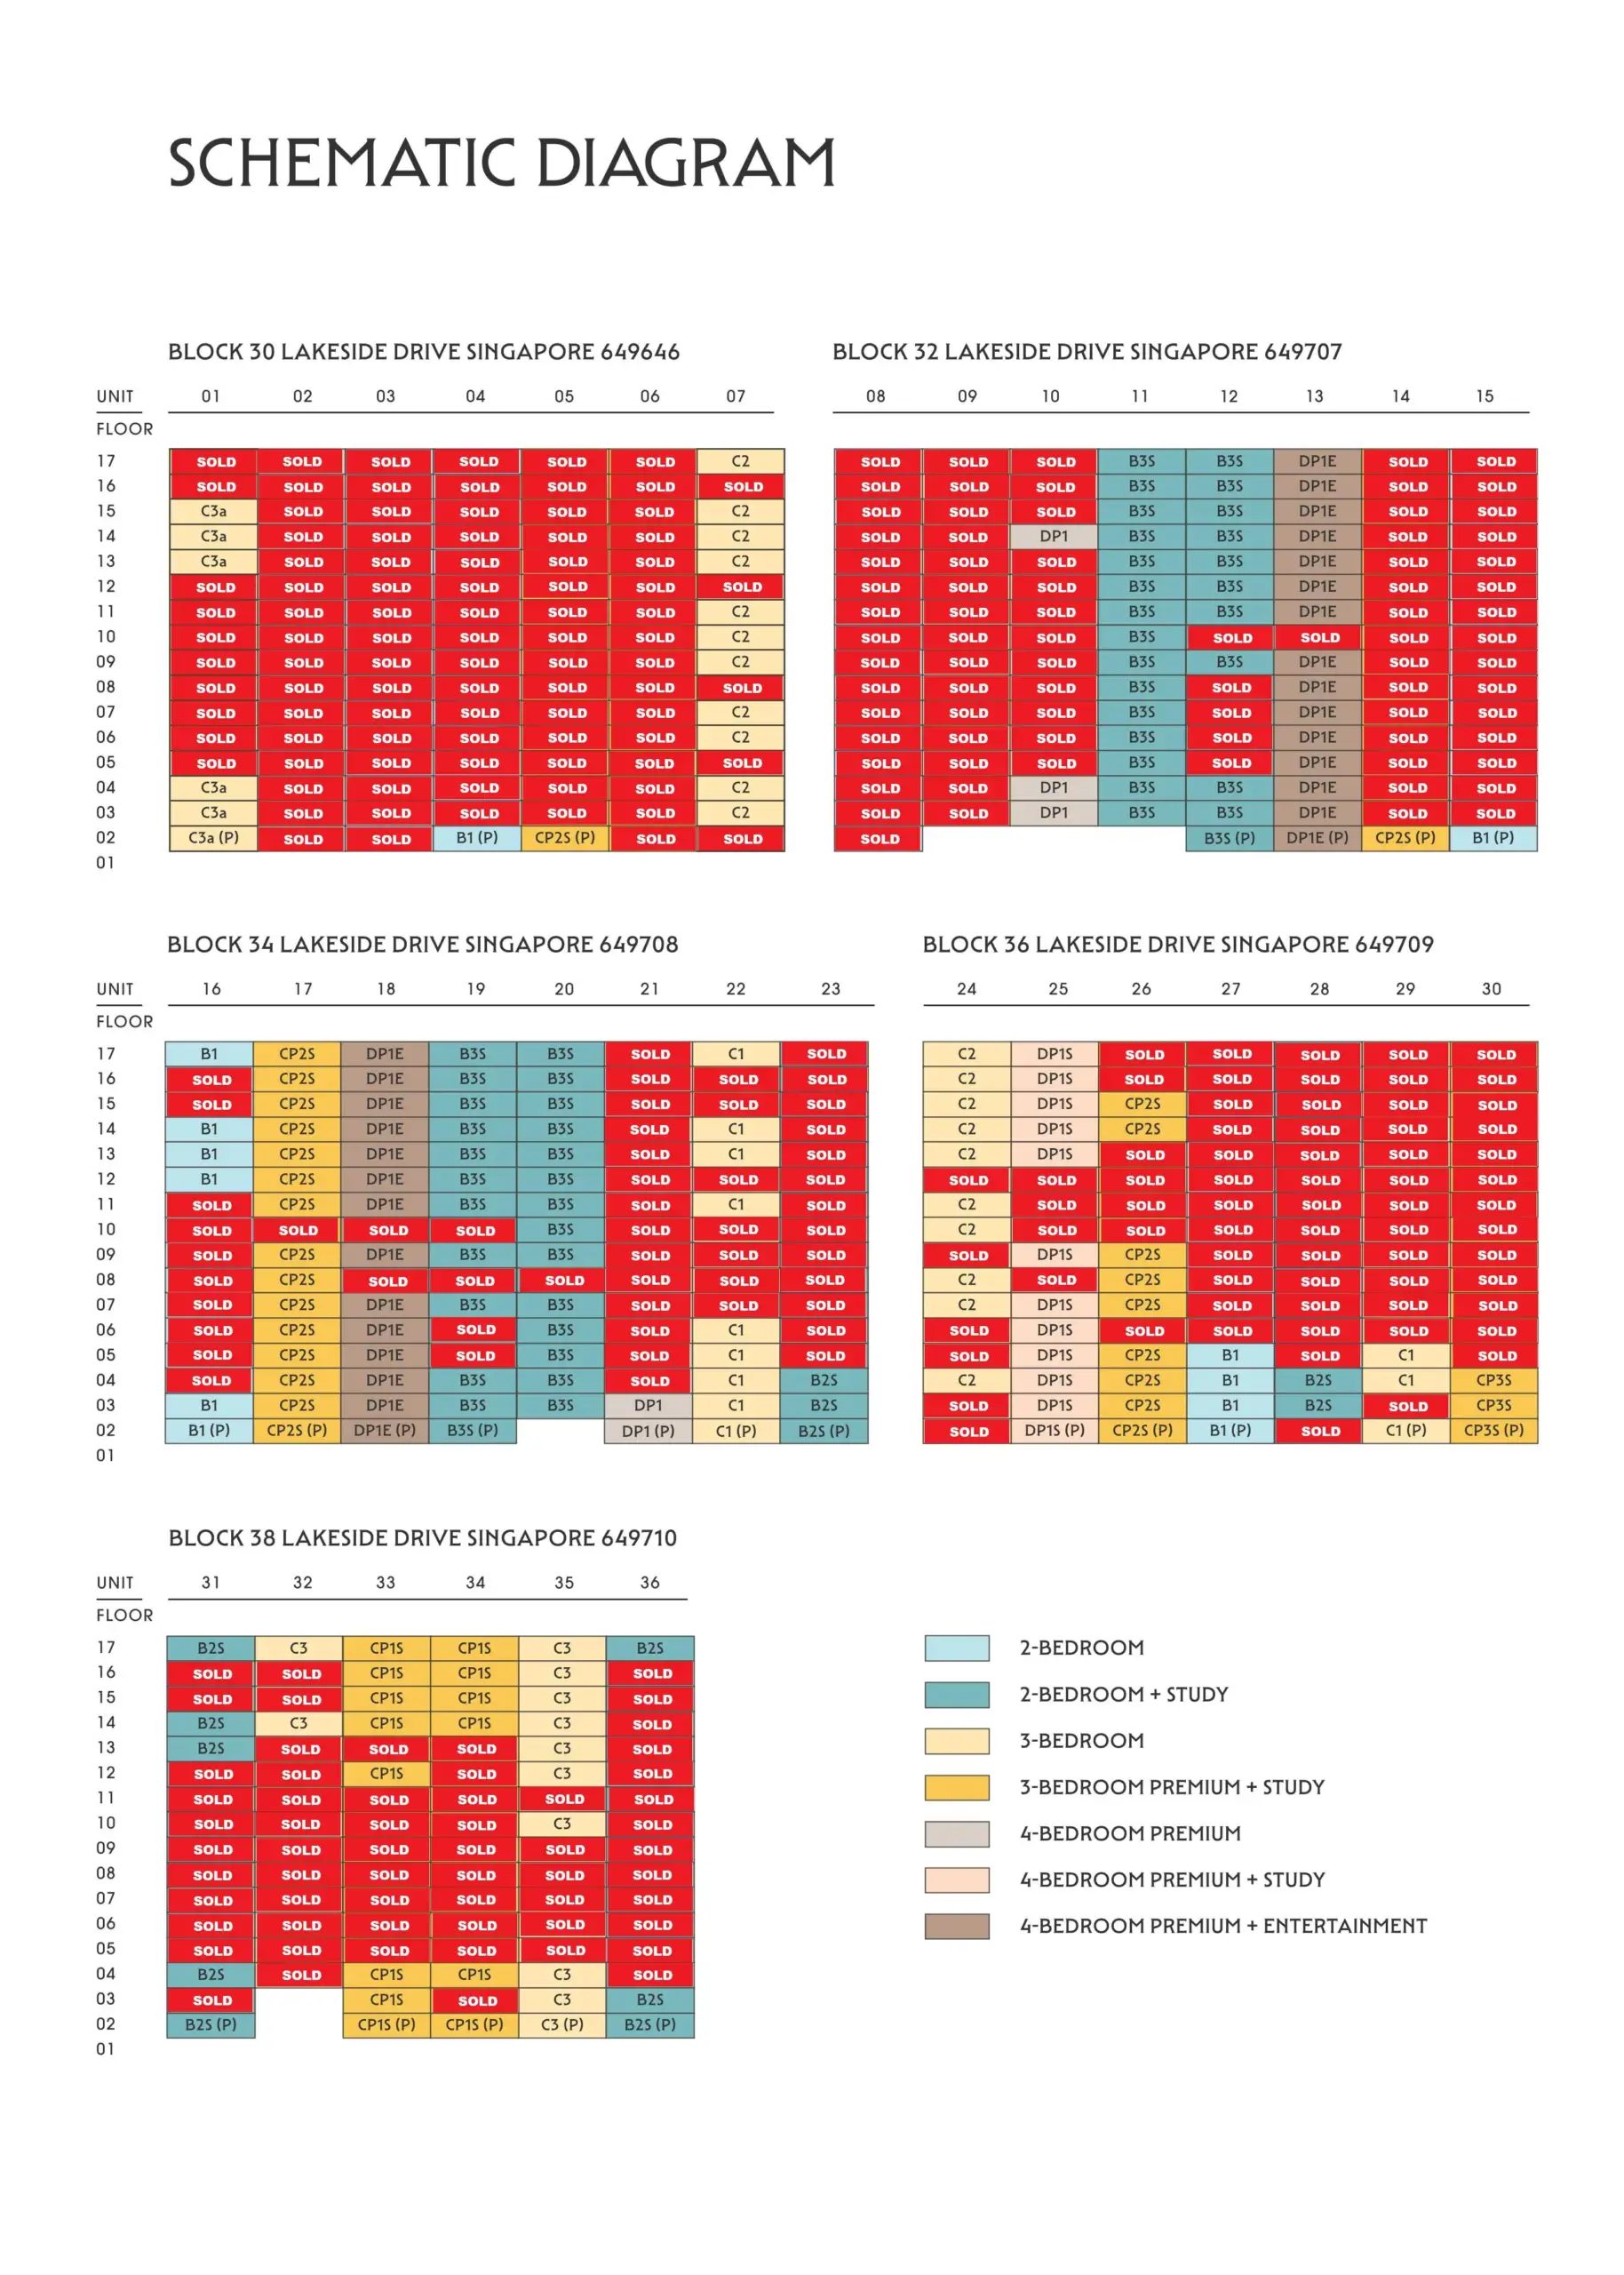
Where the 353 selections were concentrated
| Bedroom Type | Total units | Sold | Available | Selection rate |
|---|---|---|---|---|
| 2-bedroom | 96 | 84 | 12 | 87.5% |
| 2-bedroom + study | 126 | 61 | 65 | 48.4% |
| 3-bedroom | 125 | 74 | 51 | 59.2% |
| 3-bedroom Premium + Study | 128 | 85 | 43 | 66.4% |
| 4-bedroom Premium | 47 | 42 | 5 | 89.4% |
| 4-bedroom Premium + Study | 16 | 4 | 12 | 25.0% |
| 4-bedroom Premium + Entertainment | 32 | 3 | 29 | 9.4% |
| Total | 570 | 353 | 217 | 61.9% |
*Chart accurate as of 4th October 2026
The best category responses came from opposite ends of the units offered: standard four-bedroom Premium homes at 89.4%, and two-bedroom homes at 87.5%. Buyers were not confined to the cheapest offered units.
Both compact homes and conventional family-sized homes saw strong initial acceptance. The market demand weakened sharply for the largest four-bedroom variants, whose remaining asking prices start above S$3.2 million.
We also examined the demand for the different two-bedroom-plus-study sizes. Grouping them together hides one of the launch’s clearest signs of how price influenced buyer choices.
The Lakeside Drive frontage holds the strongest concentration of sales
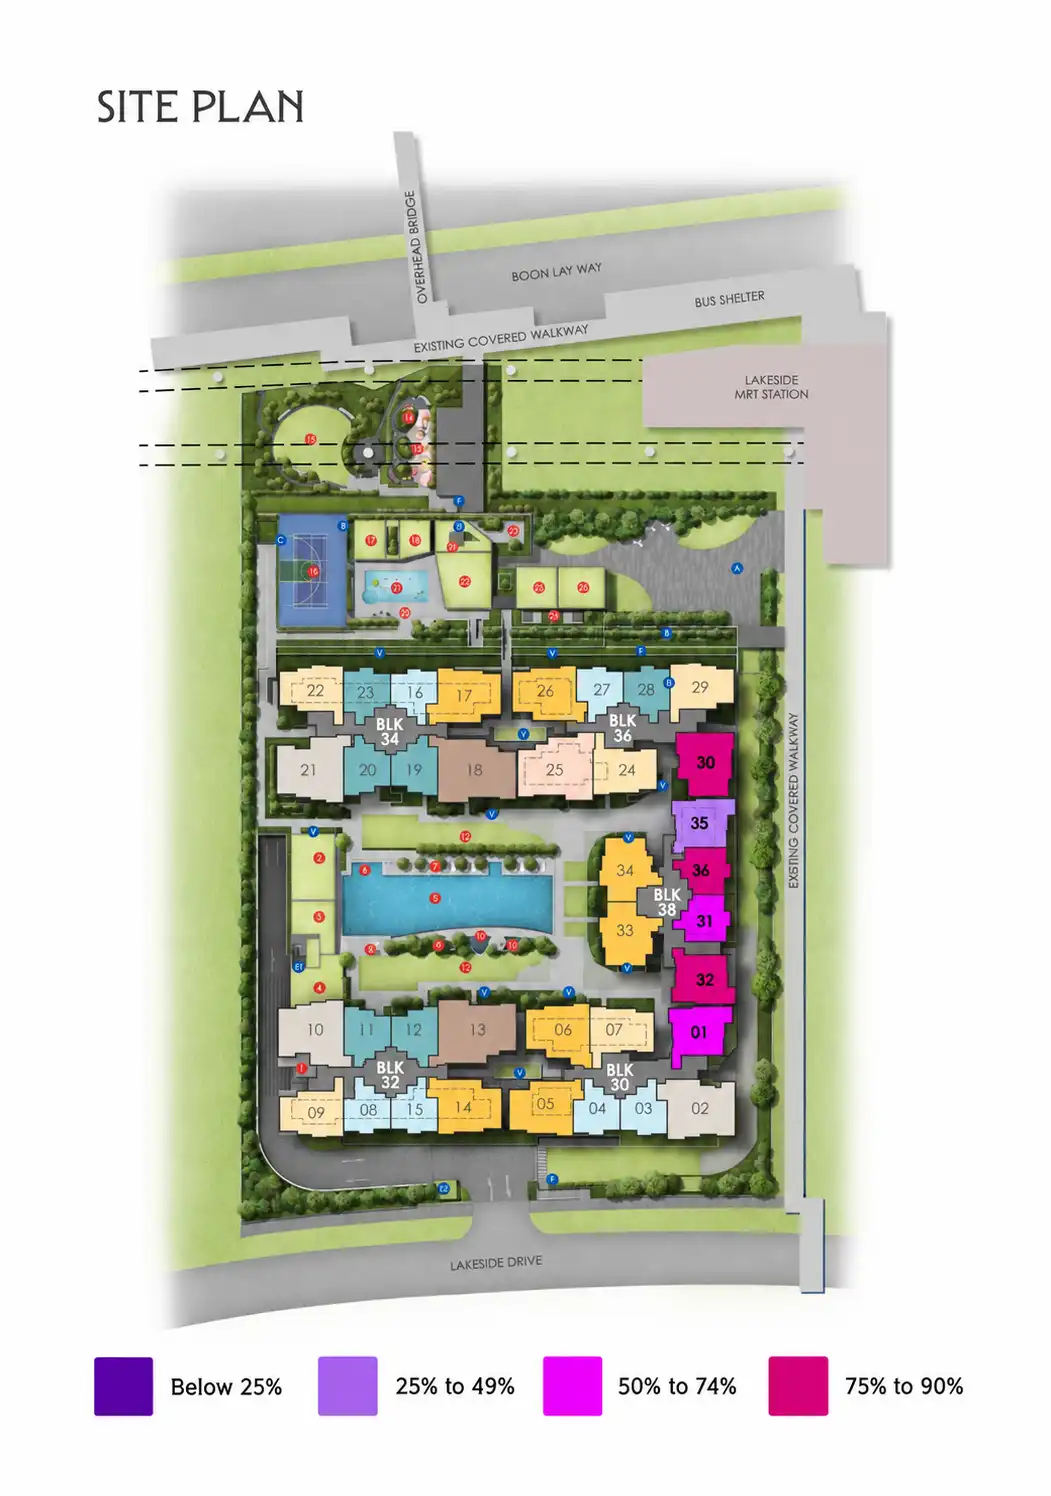
Stacks 09, 08, 15, 14, 05, 04, 03 and 02 face Lakeside Drive towards Sungei Lanchar.
Together, these stacks contain 127 homes. 123 were sold, equivalent to 96.9% of their original inventory.
Stacks 02, 03, 08 and 09 were fully sold. The only homes not sold across this frontage were the low floor units at #02-04, #02-05, #02-14 and #02-15.
This concentration spans different unit categories: two-bedroom, three-bedroom, three-bedroom Premium + Study, and four-bedroom Premium homes. Buyers could retain the project’s MRT convenience while choosing an orientation away from the track-facing side of the development.
However, facing towards Sungei Lanchar should not be presented as a guarantee of an unobstructed water view. Actual outlook depends on level, landscaping, nearby structures and the individual unit.
What it does establish is that purchases were heavily concentrated here.
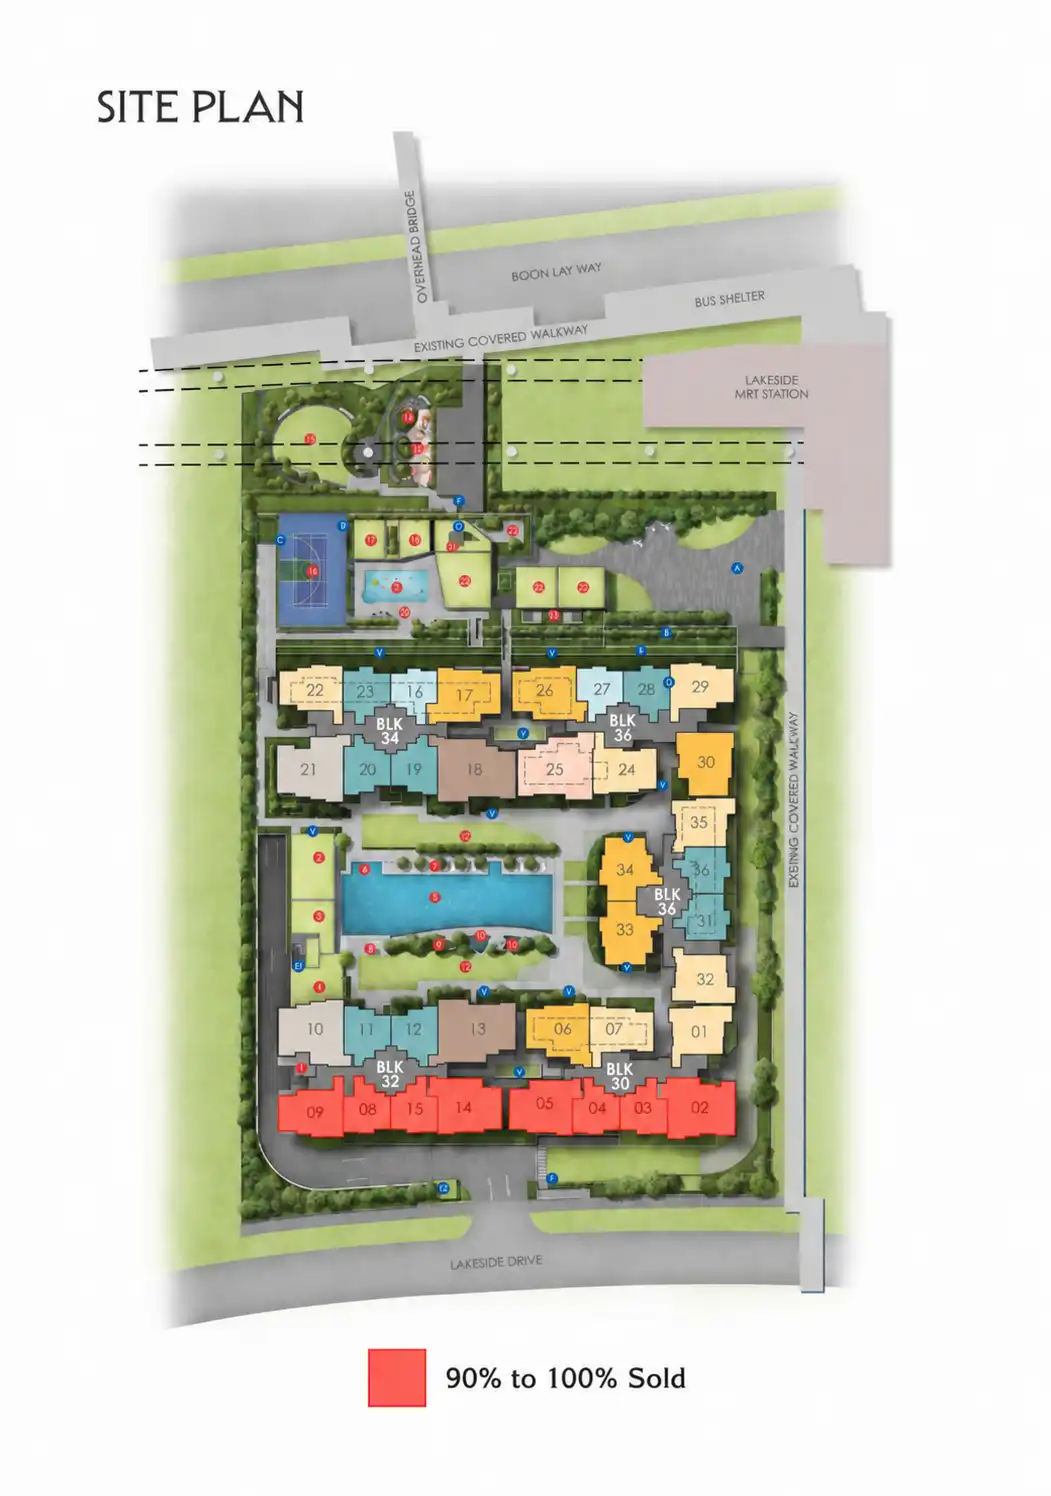
Track-facing homes sold, but buyers distinguished between stacks
The track-facing group comprises of Stacks 22, 23, 16, 17, 26, 27, 28 and 29.
| Track-facing stack | Unit Type | Sold / Total units | % Sold |
|---|---|---|---|
| 16 | 2-bedroom | 10 / 16 | 62.5% |
| 17 | 3-bedroom Premium + Study | 1 / 16 | 6.3% |
| 22 | 3-bedroom | 7 / 16 | 43.8% |
| 23 | 2-bedroom + study | 13 / 16 | 81.3% |
| 26 | 3-bedroom Premium + Study | 7 / 16 | 43.8% |
| 27 | 2-bedroom | 12 / 16 | 75.0% |
| 28 | 2-bedroom + study | 14 / 16 | 87.5% |
| 29 | 3-bedroom | 13 / 16 | 81.3% |
| Total | 77 / 128 | 60.2% |
Across the track-facing stacks, 77 of 128 homes were sold, a percetange of 60.2%. That is close to Lucerne Grand’s overall rate of 61.9%, although the different unit mixes mean this is not a direct comparison of buyer preferences by facing.
Demand was strong for the more compact layouts. Stacks 16 and 27, both B1 two-bedroom stacks, recorded 22 sales out of 32 homes: 10 in Stack 16 and 12 in Stack 27. Stacks 23 and 28, which contain 667 sq ft B2S two-bedroom-plus-study units, recorded 27 of 32 sales. These results suggest that many buyers were willing to accept track exposure in exchange for a compact layout and its price point.
The prices were identical across the two B1 stacks (i.e. #02-16 and #02-27 were both S$1.498 million, while #03-16 and #03-27 were both S$1.504 million)
The larger track-facing CP2S stacks had a more unbalanced take up rate. Stack 17 recorded one sale, compared with seven in Stack 26. Both are three-bedroom Premium + Study stacks, and offered at the same price (i.e #03-17 and #03-26 at $2,342,000). The identical prices reflect the similar, mirrored layouts and adjacent positions.
Overall, compact track-facing homes attracted strong demand, while larger track-facing homes showed more variation between stacks.
The floor pattern of these sold units also varies by stack. In Stack 27, all homes from Levels 6 to 17 were sold, while Levels 2 to 5 remained. Stack 16 recorded sales on Levels 4 to 11 and Levels 15 and 16, while Levels 2, 3 and 12 to 14 are left. Stack 23 recorded sales from Levels 5 to 17. Buyers often selected higher floors, but the pattern does not show a consistent rush to the top. Higher floors may improve the overall view, but buyers should not assume they eliminate railway noise.
Release timing, unit availability during booking and buyer preferences may have contributed to the different sales results between Stacks 16 and 27, and Stacks 17 and 26. Each pair has broadly mirrored layouts, although Stacks 16 and 17 are closer to the children’s splash pool and multipurpose court, which may have some effect on buyers’ choices.
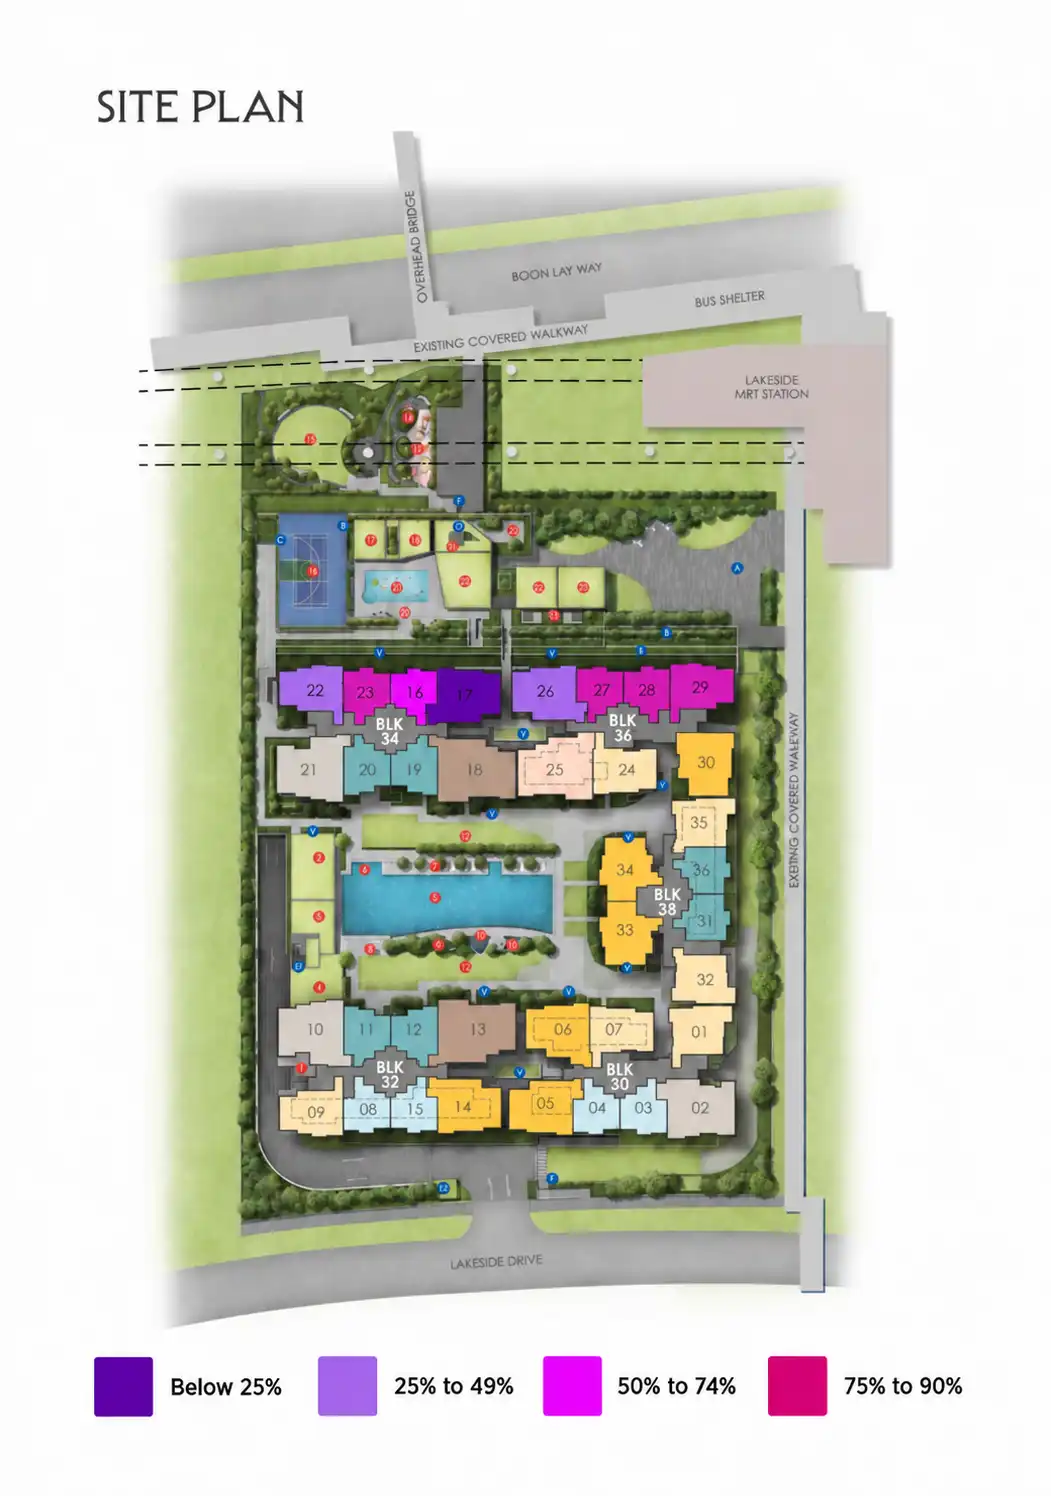
Buyers accepted the future residential plot, but the current outlook is temporary
Stacks 01, 32, 31, 36, 35 and 30 face the currently empty future residential plot that is subject to detailed planning.
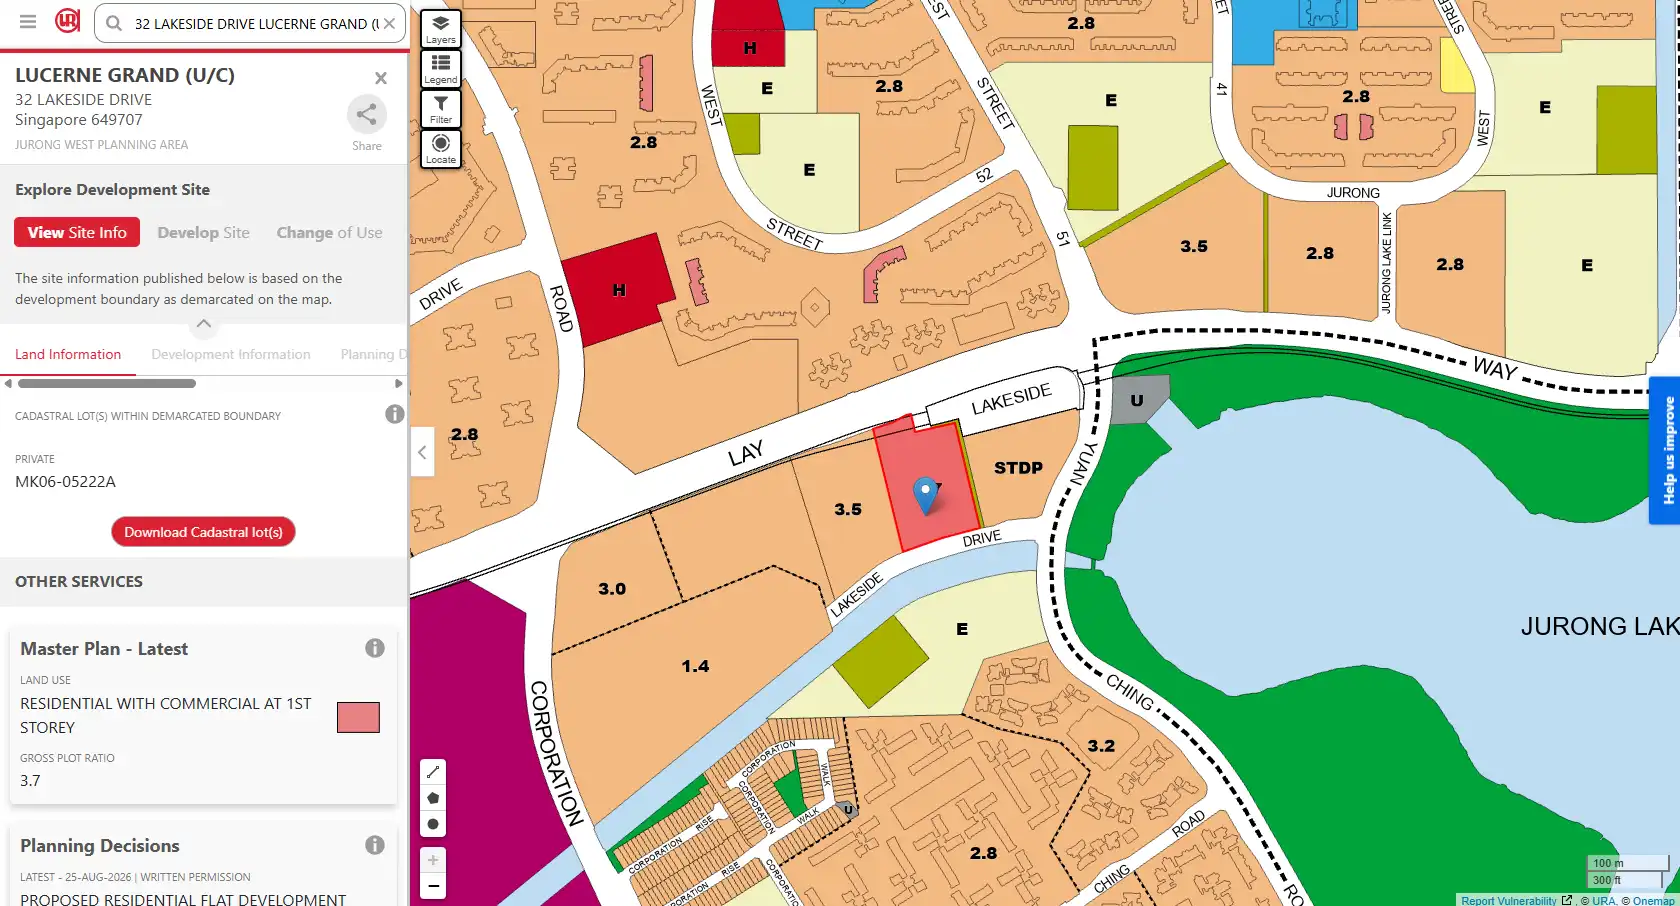
Across these stacks, 65 of 94 homes were sold (69.14%).
| Future-plot-facing stack | Unit Type | Sold / Total units | % Sold |
|---|---|---|---|
| 01 | 3-bedroom | 10 / 16 | 62.5% |
| 32 | 3-bedroom | 12 / 14 | 85.71% |
| 31 | 2-bedroom + study | 11 / 16 | 68.75% |
| 36 | 2-bedroom + study | 13 / 16 | 81.3% |
| 35 | 3-bedroom | 6 / 16 | 37.5% |
| 30 | 3-bedroom Premium + Study | 13 / 16 | 81.25% |
| Total | 65 / 94 | 69.14% |
These selections suggest that uncertainty over future development was not a significant deterrent for all buyers, with Stacks 30, 32 and 36 recording relatively strong take-up.
However, buyers should treat the current views towards Jurong Lake as an interim outlook rather than a permanent one. The neighbouring plot has been designated for future residential use, and its eventual development could affect views, privacy and construction exposure. As no plot ratio has been indicated, the scale and height of any future development remain uncertain.
The difference in buyer response between Stacks 32 and 35 is also worth examining. Both are C3 three-bedroom stacks facing the future residential plot, yet Stack 32 recorded 12 sales out of 14 homes, compared with just six out of 16 for Stack 35. This is particularly notable given that the price difference between comparable units in the two stacks is only about S$4,000, suggesting that price alone is unlikely to explain the substantial difference in take-up.
Instead, factors such as their exact positioning, floor availability and the specific units available during booking may have influenced buyer preferences. It also shows that broadly similar layouts and facings do not necessarily translate into similar demand.
For buyers considering the remaining units, the more relevant question is therefore not whether today’s open outlook towards Jurong Lake is attractive, but whether the unit would remain appealing if the neighbouring site is eventually developed and the outlook becomes more built up.
The 667 sq ft homes may reveal the importance of purchase quantum
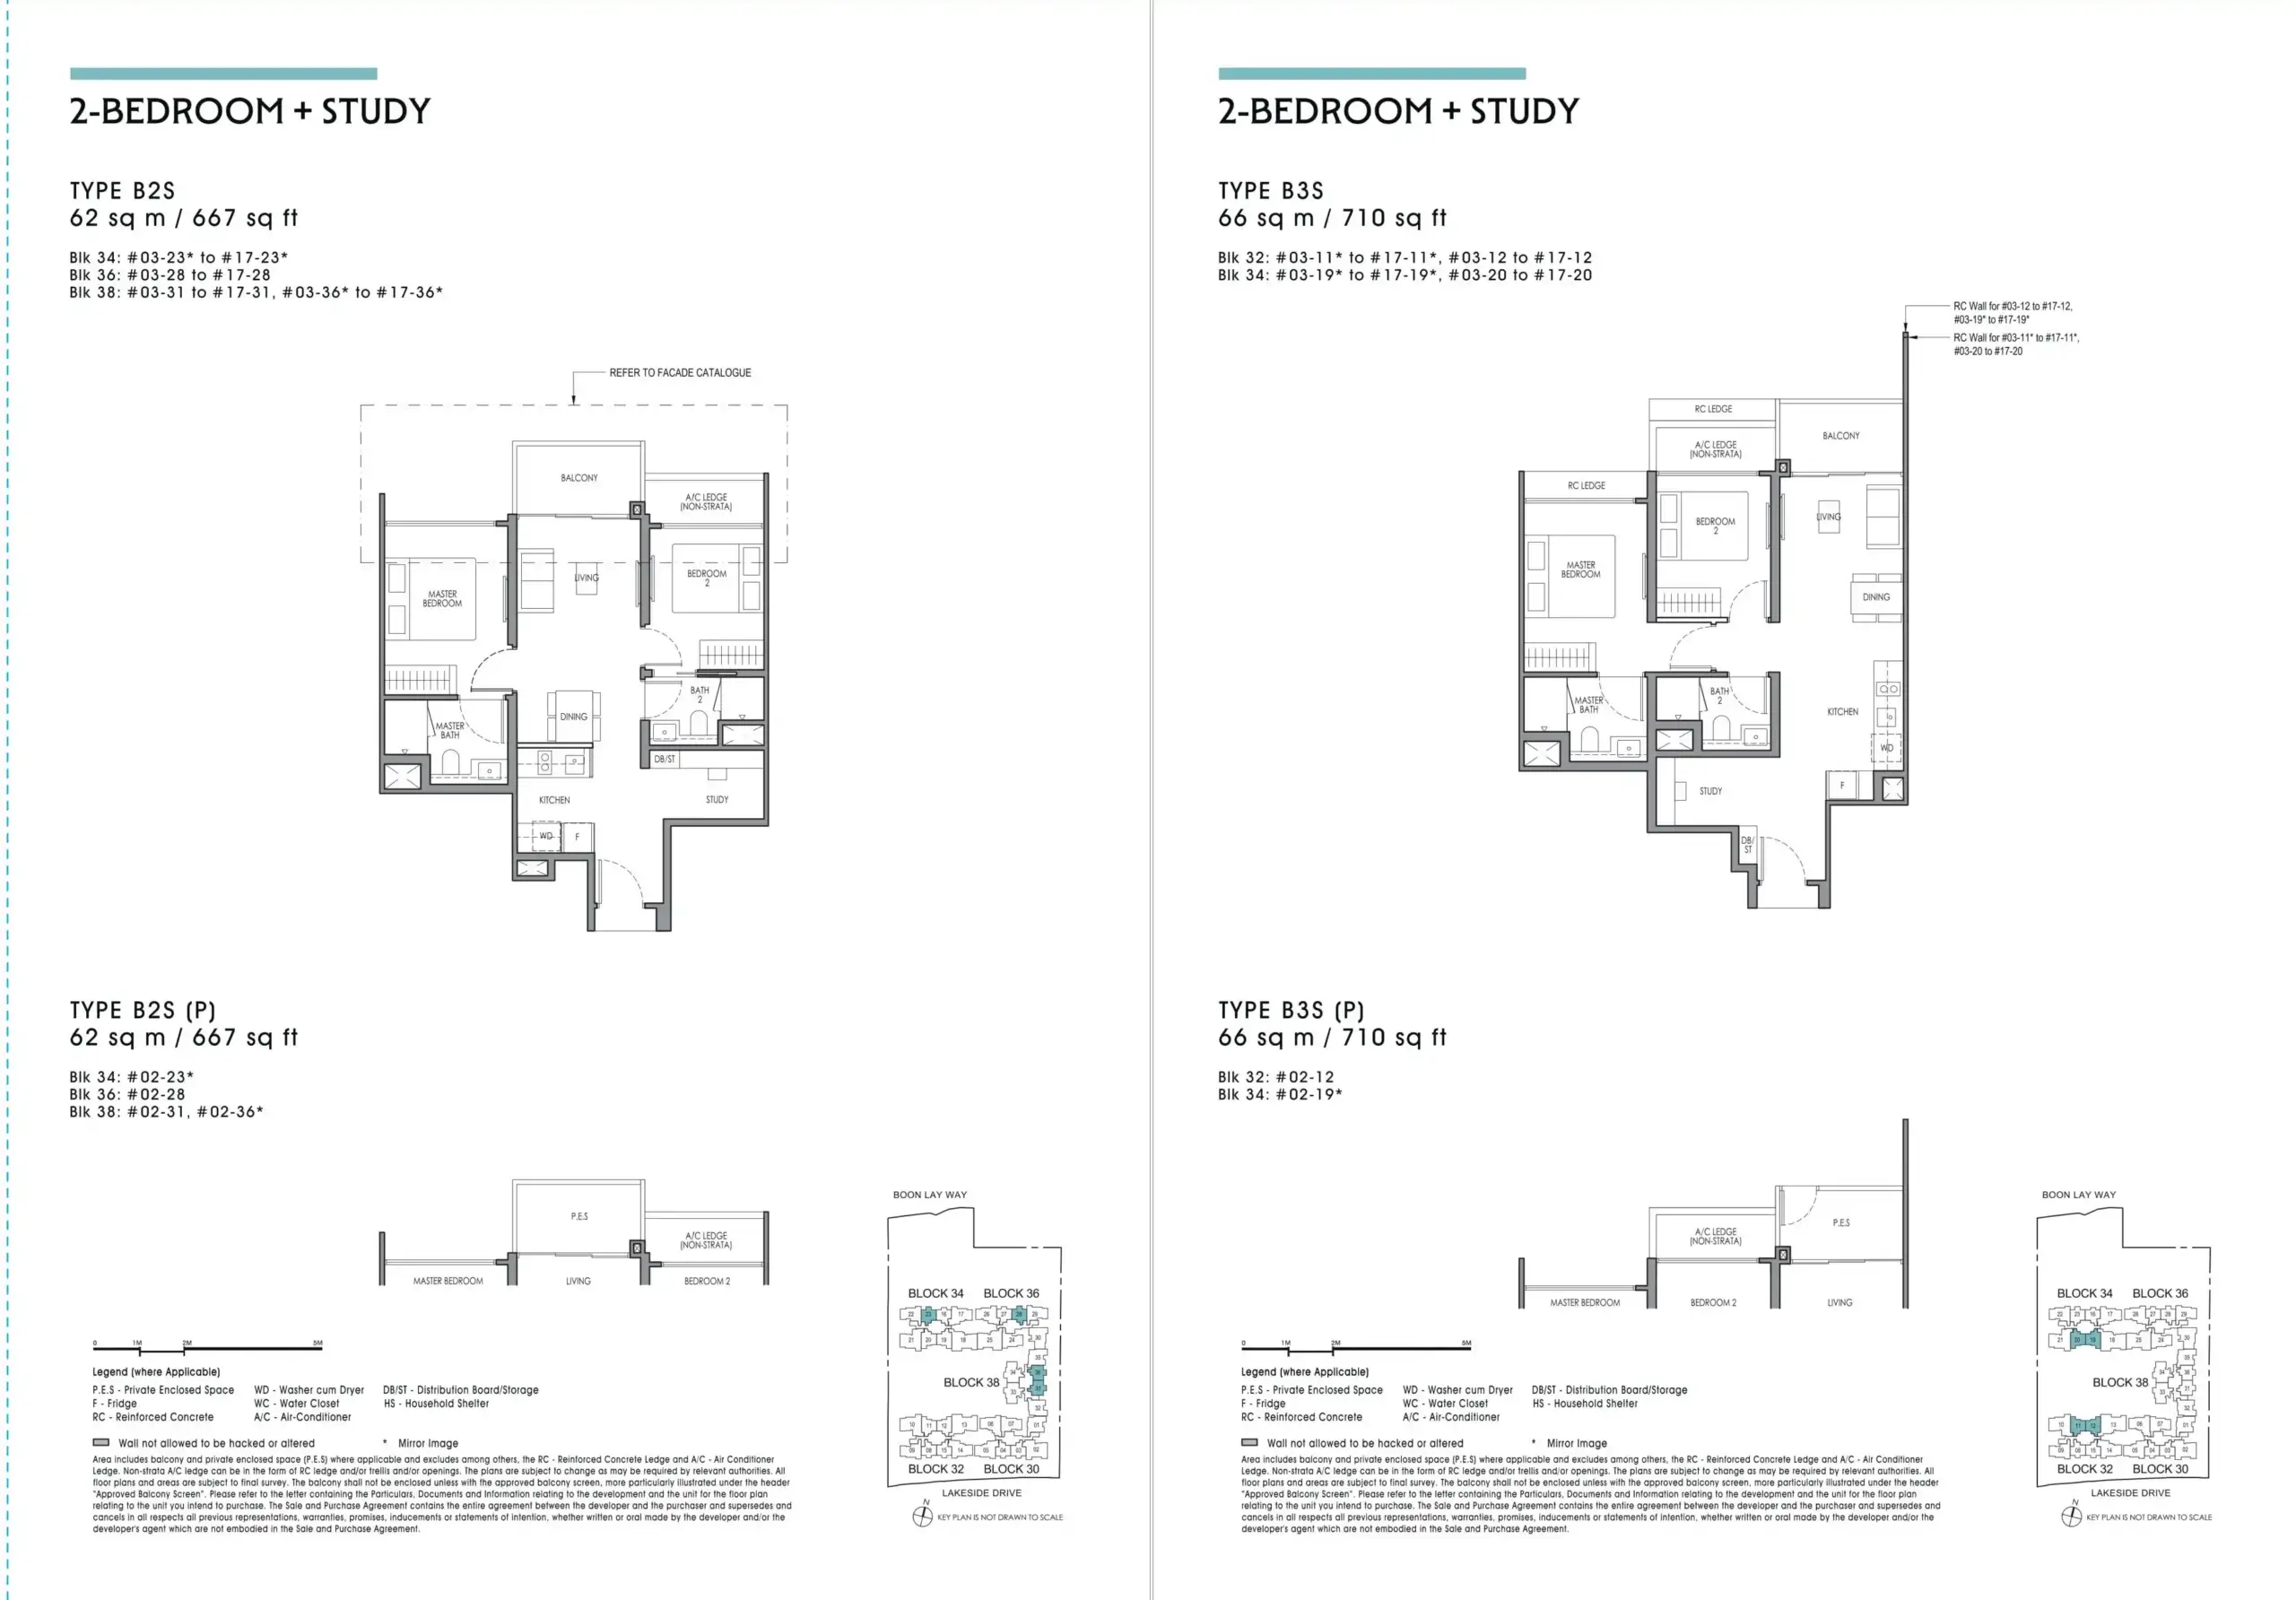
The two-bedroom-plus-study category splits into two distinctly different results.
| Configuration | Stacks | Total units | % sold | % Sold |
|---|---|---|---|---|
| 667 sq ft B2S | 23, 28, 31, 36 | 64 | 51 | 79.7% |
| 710 sq ft B3S | 11, 12, 19, 20 | 62 | 10 | 16.1% |
This is one of the greatest contrasts in the launch.
The 667 sq ft configuration performed well despite track exposure in Stacks 23 and 28, and future-plot exposure in Stacks 31 and 36. The internal-facing 710 sq ft homes recorded only 10 sales: five in Stack 12, four in Stack 19 and one in Stack 20. Stack 11 did not sell any units. Demand was higher for the larger layout, but the buyer’s acceptance rate was substantially lower than for the 667 sq ft version.
The prices may be the rationale behind this difference: the extra space and internal position came with a meaningful increase in purchase quantum.
At Level 3, #03-23 is asking at S$1.604 million for 667 sq ft while #03-19 is priced at S$1.764 million for 710 sq ft.
That is S$160,000 more for an additional 43 sq ft: approximately a 10.0% increase in price for 6.4% more stated area. Converted to psf, they are S$2,405 psf and S$2,485 psf, respectively.
From these results, we can understand that the market demand is consistent with buyers favouring a lower total price over extra space and an internal orientation. Moving into the S$1.76 million range may have reduced the appeal of the larger two-bedroom-plus-study option when other choices existed within the development.
“Two bedrooms plus a study” was not enough to create equal demand across both products. Buyers appeared much more receptive to the version that kept the purchase quantum lower.
Standard four-bedroom demand was best among the larger-home layouts
The standard four-bedroom Premium homes recorded 42 out of 47 units sold, or 89.4%.
Stack 02 was fully sold. Stack 10 recorded 12 of 15 sales while Stack 21 recorded 14 of 16.
Stacks 10 and 21 are internal-facing facility units. Their strong response is a useful counterpoint to the weaker internal-facing two-bedroom-plus-study stacks.
The internal orientation was therefore not inherently unpopular. Across all internal-facing stacks, 88 of 221 homes were sold, or 39.8%, but that aggregate combines products with very different responses.
Stack 06 was fully sold, while standard four-bedroom Stacks 10 and 21 recorded 26 of 31 sales. In contrast, the internal C2 three-bedroom Stacks 07 and 24 recorded just 11 of 32 sales, and the 710 sq ft two-bedroom-plus-study group recorded 10 of 62. Buyers were evaluating particular homes, rather than uniformly favouring or rejecting internal facings.
Here are some of the prices of the internal facing units:
| Remaining unit | Configuration | Size | Asking price | Listed PSF |
|---|---|---|---|---|
| #03-10 | 4-bedroom Premium | 1,163 sq ft | S$2.828 million | S$2,432 |
| #02-21 | 4-bedroom Premium | 1,163 sq ft | S$2.818 million | S$2,423 |
| #02-25 | 4-bedroom Premium + Study | 1,345 sq ft | S$3.228 million | S$2,400 |
| #02-13 | 4-bedroom Premium + Entertainment | 1,432 sq ft | S$3.398 million | S$2,373 |
| #02-18 | 4-bedroom Premium + Entertainment | 1,432 sq ft | S$3.407 million | S$2,379 |
The larger units can look attractive on a per-square-foot basis. But the buyer must commit substantially more money.
For example, the remaining #02-25 asks S$410,000 more than #02-21. Its additional 182 sq ft represents approximately 15.6% more area, with a roughly 14.5% higher purchase price. The extra space is not disproportionately expensive, but crossing from about S$2.8 million to above S$3.2 million still changes the financial commitment.
The results show a prominent divide: four of 16 Premium + Study homes were sold, while three of 32 Premium + Entertainment homes were taken. The latter comprised of units #10-13, #10-18 and #08-18. There were purchasers for the largest format, but 29 homes remained unsold in that category.
This suggests a much lower initial market for Lucerne Grand’s largest configurations. It does not establish a universal S$3 million ceiling, but we can clearly see that there is some resistance when prices cross $3mil.
It shows that strong demand for four bedrooms did not automatically extend to every larger four-bedroom product.
How the launch qualifies our earlier investment analysis
In our Lucerne Grand Investment Analysis Part 2, the entry three-bedroom stood out for its pricing, while the larger homes raised concerns about the affordability of a future resale purchase.
The launch results reinforce the importance of total purchase price, while showing that relative value and initial popularity can produce different rankings.
Standard four-bedroom homes achieved the highest sales percentage despite their higher prices. By comparison, the internal-facing C2 three-bedroom Stacks 07 and 24 recorded just 11 sales out of 32 homes. A price close to S$2 million was therefore not enough to generate equally strong demand across every three-bedroom stack.
For example, the 883 sq ft #03-07 remained listed at S$1.998 million, or S$2,263 psf. Its competitive pricing suggests that buyers were also weighing the stack’s position, facing and layout.
The Bala’s Table and illustrative GFA adjustments used in our earlier analysis help compare pricing across developments; they do not establish a unit’s market value or predict its future returns. The launch adds another consideration: a home’s relative value should be assessed alongside its individual appeal, while strong initial sales do not guarantee better long-term investment performance.
What the remaining prices say about buyer choice
The remaining inventory offers very different ways to spend a similar budget.
| Remaining unit | Facing classification | Size | Asking price | Listed PSF |
|---|---|---|---|---|
| #03-07 | Internal | 883 sq ft | S$1.998 million | S$2,263 |
| #04-24 | Internal | 883 sq ft | S$2.004 million | S$2,270 |
| #02-29 | Tracks and future plot | 872 sq ft | S$2.050 million | S$2,351 |
| #02-35 | Future plot | 893 sq ft | S$2.128 million | S$2,383 |
| #02-01 | Future plot | 904 sq ft | S$2.158 million | S$2,387 |
| #02-17 | Tracks | 1,001 sq ft | S$2.328 million | S$2,326 |
| #02-26 | Tracks | 1,001 sq ft | S$2.328 million | S$2,326 |
| #02-34 | Internal | 947 sq ft | S$2.396 million | S$2,530 |
*Selected prices dated 4 October. These are not recorded sale prices and do not represent the complete remaining price list.
Comparing #02-26 with #02-34 highlights the trade-off between facing, space and price. The internal-facing #02-34 is S$68,000 more expensive despite having 54 sq ft less stated area. The buyer is weighing an internal position and a different layout against a larger track-facing home at a lower price.
This helps explain why neither the cheapest PSF nor the preferred facing can answer the purchase question alone.
The internal Premium + Study Stacks 33 and 34 recorded eight and ten sales respectively. That is meaningful demand, but their remaining higher-floor homes also show that buyers did not automatically choose every available floor.
Across the development, the sales figures show the strongest take-up on the middle floors. Levels 5 to 12 recorded 220 sales out of 288 homes, or 76.4%, compared with 33 of 102 homes on Levels 2 to 4 (32.4%) and 100 of 180 homes on Levels 13 to 17 (55.6%).
These bands are descriptive, not matched comparisons: unit mix and release status may differ. Still, the middle floors’ stronger response is consistent with buyers balancing elevation against the additional price of upper floors.
Overall demand was substantial but highly selective
With 353 of 570 homes sold, Lucerne Grand’s launch signals strong demand for new private housing at Lakeside. The breadth of purchases is as important as the overall 61.9% selection rate.
The Lakeside Drive frontage was almost entirely taken. Two-bedroom homes achieved an 87.5% selection rate overall, with meaningful purchases on both track-facing B1 stacks. The 667 sq ft two-bedroom-plus-study homes also performed strongly despite railway or future-development exposure. Standard four-bedroom homes achieved 89.4%, showing that demand extended to larger family accommodation.
These results point to at least two well-received propositions: a compact home with a relatively manageable purchase quantum, and a standard four-bedroom home offering family space without moving into the largest configurations. We do no have the percentages of the purchaser profiles , so these outcomes should not be converted into claims about the proportion of investors or owner-occupiers.
Demand became thinner when buyers were asked to pay more for the 710 sq ft two-bedroom-plus-study layout or the largest four-bedroom configurations. Those units attracted purchases, but their take up rates were significantly lower. More space, an internal orientation, or a lower PSF did not automatically offset the higher total cost.
The clearest conclusion is that Lucerne Grand found substantial demand across compact and family-sized homes, with buyers remaining selective about the price of additional space and the individual stack. The market accepted the project’s core proposition; it did not endorse every configuration equally.
For the wider suburban market, this is encouraging evidence that buyers remain willing to commit to a new development offering direct MRT connectivity and everyday conveniences. One project’s launch cannot establish a market-wide recovery or justify higher pricing elsewhere. The stronger conclusion concerns demand at Lakeside for homes offering a particular balance of convenience, configuration and total cost.
The next test is whether the abosrbing rates of the 217 homes. Continued purchases across the larger and slower-moving categories would demonstrate demand beyond the initial launch pool. If those categories remain slow, the contrast would reinforce the importance of total purchase quantum and unit-specific appeal.
For buyers, the lesson is equally clear: the launch validates Lucerne Grand‘s appeal, but it does not make every remaining unit equally attractive. The best purchase still depends on what the particular home offers at its actual price, and how that proposition will look to a future buyer.
Disclaimer: Prices and availability may change and only accurate at the time of publishing. Explanations of buyer preferences are interpretations, not proven motivations. Future-plot outlook and railway exposure require unit-specific assessment. The article is for general information and does not constitute a valuation or a recommendation to purchase a particular unit.
Article contributed by Jerry Wong.

Jerry Wong is a realtor at Propnex Realty, bringing a rich background in interior and lighting design to his work. He loves exploring diverse spaces and observing the transformative power of real estate. Beyond his professional role, Jerry finds his greatest fulfillment in connecting people with the right properties, gaining immense satisfaction from helping clients achieve their dreams.


