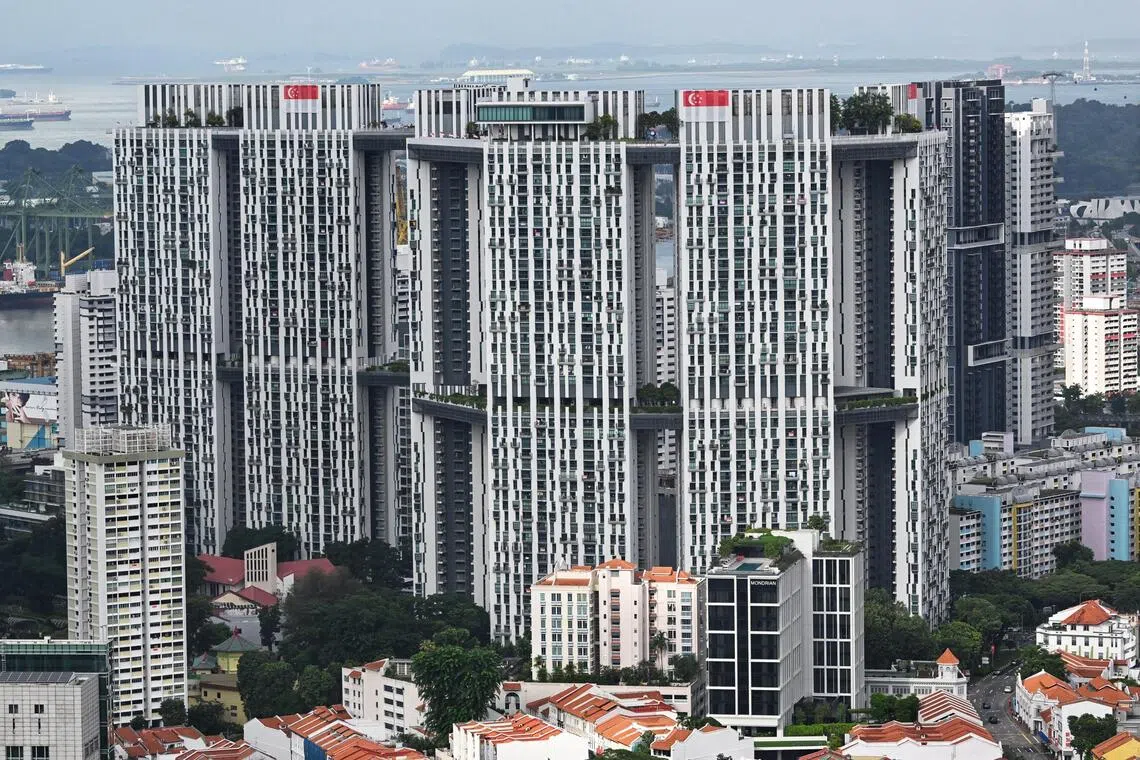
SINGAPORE – The tried-and-tested courtship ritual of booking a brand-new HDB flat before getting married paid off handsomely for one Singaporean couple, who will reap a cool $1 million in profit after selling their 15-year-old flat.
Such a huge gain was possible because they were lucky to be among the 1,848 buyers who successfully balloted for the coveted units at the Pinnacle@Duxton estate at the Central Business District.
The couple paid $305,600 for their unit in 2005 when it was still being built, and they lived there when they got married in 2011.
But they broke up, and the High Court ordered the flat to be sold and the proceeds divided along with their other assets.
The flat was worth $1.24 million, according to a valuation report in July 2025 accepted by the court.
But such a flat could well fetch a higher price now, as the asking prices for four-room flats at Pinnacle@Duxton are between $1.15 million and $1.5 million, while those who own five-room flats are asking for $1.35 million to $1.65 million.
The couple, who have no kids, must have liked living in their flat because they did not move to a condominium or a house, even when the husband’s career took off. He was the sole breadwinner.
While he earned under $8,000 when they bought the flat, his monthly salary shot up to $70,000 by 2020 when he was in an international consulting firm.
Even when the estranged wife moved out of the flat, he continued to live in the flat.
But during their almost decade-long marriage, the man did not buy a second home in Singapore. Instead, he invested in a shophouse here with his father and bought three overseas properties in the United Kingdom and Indonesia.
Here are three financial lessons from their case that all property owners should know.
Valuation report of your home
It is befuddling that many owners fighting over properties rely on free online transaction records instead of paying a small fee for a proper valuation.
This is a classic example of being penny-wise, pound-foolish, as you stand to lose a lot more if the court rejects your free report.
In this case, the wife produced a proper home valuation report dated July 29, 2025, which valued the flat at $1.24 million.
But the husband argued that the flat should be valued at $920,888, based on the actual sale price of a similar flat in May 2021 published on the HDB website.
He said that his valuation should be preferred because the wife’s valuation report was “not independently verified”. He fought for a lower valuation so that he did not have to share the money during the divorce.
But the court accepted the wife’s report, which was done just two months before the court hearing. It rejected the husband’s argument as his preferred valuation was based on a single transaction that took place about four years ago.
Financial contributions to properties
If you are buying a property jointly with another co-owner, you should not mind paying more because you will be entitled to a larger share of the real estate, especially if its value appreciates in the future.
If you foot all direct purchase costs, such as the stamp duty and legal fees, you will likely get a larger share proportionate to your payment. This is because when payments are deducted from the buyers’ CPF accounts to fund the transaction, it is hard to determine whose money is being used to pay the purchase price, stamp duty, or the legal expenses.
The rationale is the same for mortgage payments because it is tedious to calculate the portions that go to paying only for the property and not the bank interest.
So, to determine the owners’ shares, the court usually looks at each buyer’s total contribution.
In this case, the court found that the wife contributed $147,362, or 47 per cent, while the husband paid $166,189, or 53 per cent from their CPF accounts to buy the flat.
As the flat was valued at $1,240,000, the court took note of the couple’s contributions and found that the wife’s share of the flat value was $582,800 while the husband would be entitled to a 53 per cent share, or $657,200.
But these sums would only be used to determine their overall share of family assets which totalled about $7.6 million, including the HDB flat.
Investing in overseas properties
The husband’s accounting and consulting background helped him devise a unique way to invest in two overseas properties with his colleagues’ help.
When employees are posted overseas, they usually receive living allowances that would allow them to rent a place to stay.
The husband came up with a scheme to get his colleagues to co-invest in local properties to stay in, instead of renting. He did this with two colleagues when they were posted in the United Kingdom and Indonesia.
The colleagues could apply for local bank loans to buy the apartments and use their overseas allowance to pay the monthly mortgage payments.
To sweeten the deal, the husband paid the down payment and topped up any shortfall in the monthly repayments.
Based on his agreements with his co-workers, if the units were eventually sold, he would share half the profits with them. But if the units were sold at a loss, the husband would absorb the losses himself.
The arrangements seemed to work well, as the colleagues gave evidence that although the homes were bought in their names, the husband bore full financial responsibility for the properties.
For instance, the colleague stationed in the UK had lived in the unit purchased in her name and used her rental allowance to pay the monthly mortgage instalments, utility bills and local taxes.
Even after she left the country for another posting, the unit was leased out to other tenants. The rental proceeds were paid into her bank account and then used to repay the mortgage.
If there was any shortfall, the husband would remit money to her to top up the difference.
The court found that the husband was the owner of both the overseas properties and the net values of the real estate were added to the pool for sharing. In doing so, the court noted that its ruling would not affect the rights of the colleagues, who can still pursue their claims separately against the husband, if they feel they are entitled to a bigger share of the properties.
What this means is that if you buy a property but let another person become the legal owner, there is always a risk of a dispute if the owner disregards your interest in the home.
As the sole breadwinner, the husband was in the end given 65 per cent of all the assets, or about $4.9 million, while the wife was given about $2.7 million, or 35 per cent. Their flat would be sold and the proceeds would be divided according to this ratio after the money that was used from the couple’s CPF accounts had been refunded.
“Source:[Property valuation reports: Why it pays to pay for one] © Singapore Press Holdings Limited. Permission required for reproduction”