A Sellout That Reset the Local B1 Benchmark
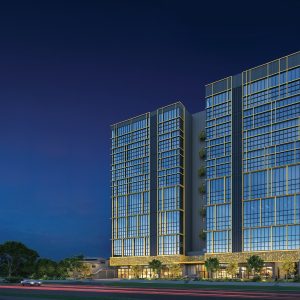
CT Gold @ Macpherson was not just another strata industrial launch that sold reasonably well. It was fully sold out as of 1 May 2026, with all 63 production units and three industrial canteens taken up within two days. That matters because the project did not clear in a vacuum: in the 1km comparison map, the nearby B1 market shows 11 projects with 290 past-sale transactions averaging $797 psf, 57 active resale listings averaging $999 psf, and zero other new B1 projects or new-project listings within the same radius. Against that backdrop, EdgeProp’s reported CT Gold transacted band of roughly $1,500 to $1,600 psf implies a premium of about 88% to 101% over the local historic transaction benchmark and about 50% to 60% over the current resale asking benchmark.

The most important analytical point is that this was not just a tenure story. The comparison sheet is already dominated by freehold stock, including Tong Lee Building, Golden Wheel Building, Lipo Building, Valiant Industrial Building, Mactech Building, Biztech Centre, Cititech Industrial Building, Noble Logistics, Aljunied Industrial Complex, HH @ Kallang, and Tannery House. In other words, buyers were not simply paying extra because CT Gold was freehold while everything else was leasehold. They were paying for a brand-new freehold product in a micro-market where the available alternatives are overwhelmingly resale stock and where there are no other new B1 launches nearby.
What Actually Sold On 1st May
The sales timeline helps explain why the “sellout on 1 May” headline is directionally right, even though the article describes a two-day clearance. EdgeProp reported that CT Gold was previewed from 15 April to 29 April; bookings began on 30 April, with priority given to buyers taking 5 to 10 units; and when sales opened on 1 May at 10am, the remaining units were quickly absorbed by buyers taking 2 to 4 units each. The first three-level canteen units were also snapped up by separate buyers, and the project was fully sold out as of 1 May 2026.
The distribution chart reinforces this. It shows a broad-based sellout across the full-stack mix, rather than demand concentrated in lower-floor units or a few obvious “best buy” stacks. This distinction matters. When both production and canteen units are cleared across the development, it signals confidence in the overall project fundamentals, not merely opportunistic buying of selected units.

Why Did Buyers Move So Quickly?
The first reason is that the launch structure concentrated demand. The second is that the buyer profile was more practical than speculative. EdgeProp says the take-up was driven largely by bulk buyers, but that the majority of buyers were end-users. Those two statements are not contradictory in this case. The production units were reported to be around 1,615 to 1,959 sq ft, so buying two, three, or four units is a realistic way for an SME to assemble a meaningful operational footprint while still owning strata space. The same article also indicates that most production units transacted at an average of $1,500 to $1,600 psf, translating to an average absolute quantum of $2.5 million to $2.6 million. That is a premium psf, but still a digestible ticket size for owner-occupiers and corporate buyers.
The second reason is the unusually clean fit between what B1 zoning allows and who actually wanted the project. URA’s B1 guidelines allow predominant uses such as light manufacturing, food industry packing, e-business, core media and industrial training, while ancillary uses can include offices, meeting rooms and industrial canteens. EdgeProp says actual demand at CT Gold came mainly from owner-occupiers in light manufacturing, e-commerce, logistics and creative industries. That overlap is a big deal. It means the project was not pushed into a narrow regulatory niche; it sat squarely within the permitted-use sweet spot for several real demand pools.
The third reason is that the product solved real operational problems that older stock often does not solve as neatly. With ceiling heights up to 7.35m, 10 kN/sqm floor loading, 100A three-phase power, partial ramp-up access, and an integrated provision of three industrial canteens. URA’s guidelines note that industrial canteens are an allowable ancillary use in B1 developments, serving workers in the industrial estate and, in some cases, members of the public. In practical terms, CT Gold was being marketed not just as “space,” but as a ready-made operating environment.
The fourth reason is timing. According to JTC’s 1Q 2026 Quarterly Market Report, Singapore’s industrial rental index was still rising, up 2.3% year on year, while the industrial price index was up 4.6% year on year. EdgeProp also quotes market participants saying more businesses are rethinking their long-term space strategy and shifting from leasing toward ownership where possible. In that setting, a city-fringe freehold B1 launch with no nearby new-project competition arrived at exactly the right moment.
A fifth supporting factor was execution credibility. Chiu Teng Group’s earlier project, CT Pemimpin, also fully sold shortly after its March 2025 launch, and the CT Gold take-up was described as even stronger because of its more central location. Repeated sellouts do not guarantee future performance, but they do lower buyer hesitation at the decision point.
Why The Premium Stand Up Against Nearby B1 Comparables
The raw spread looks dramatic, but the premium becomes more understandable once the benchmarks are separated properly. On the broadest measure, CT Gold’s average $1,500 to $1,600 psf sits around 88% to 101% above the historic transaction average of $797 psf, and around 50% to 60% above the active resale asking average of $999 psf. Those numbers are very large, but they are comparing a brand-new developer sale against a surrounding pool of mostly older resale stock.
A more relevant comparison is with the better-dated freehold stock nearby. HH @ Kallang, which obtained TOP in 2015, records an average past transaction price of $1,050 psf and an average active resale asking price of $1,373 psf. On that basis, CT Gold’s typical sold price is still about 43% to 52% higher than HH @ Kallang’s historical transaction level, but only around 9% to 17% above its current asking benchmark.
The same pattern appears when compared with Biztech Centre, a freehold B1 development completed in 2001. Its average past transaction price is $1,033 psf, while current resale asking prices average $1,300 psf. This places CT Gold at a premium of roughly 45% to 55% over Biztech Centre’s historical trades, but a more modest 15% to 23% above its current asking prices.
This narrowing premium is important: CT Gold looks expensive when measured against older historical transactions, but much more defensible when benchmarked against today’s asking prices for the better freehold alternatives nearby.
That narrowing is the key insight. If CT Gold is compared against the entire surrounding resale universe, the scheme looks like a huge re-pricing event. If it is compared against the best nearby freehold resale alternatives, the premium is still meaningful but no longer looks irrational. This suggests that buyers were not blindly overpaying. They were paying an incremental premium for newness, current specifications, layout efficiency, remaining economic life, and lower near-term capital expenditure risk, on top of already-re-rated freehold resale stock. That is an inference from the absence of other new launches within 1km, and CT Gold’s published product specifications.
There is another subtle point that supports this analysis. The nearby resale market is already pricing in optimism: with overall active asking average of $999 psf is about 25% above the historic transacted average of $797 psf. In other words, sellers of older stock have already been trying to re-rate values upward. CT Gold nonetheless sold at levels materially above even those asking expectations. That is how a new benchmark typically behaves when it is genuinely scarce and functionally better than the surrounding stock.

How The Planning Context Supports Value
The land story reinforces the sellout story. Before CT Gold existed as a strata-launch product, the former MacPherson Industrial Complex at 5 Lorong Bakar Batu had already shown strong market appeal. The previous site was an eight-storey freehold industrial property on a 49,410 sq ft parcel, zoned Business 1 with a plot ratio of 2.5, and with a 98-metre frontage. ETC later announced that the collective sale closed at $103.888 million in May 2025, which was 17% above the earlier asking price and attracted 12 competitive bids. That is not a weak land-basis story. It is evidence that serious buyers had already identified the site itself as valuable before the strata sellout ever happened.
The location and connectivity are equally important. EdgeProp and ETC both describe the site as being within the established MacPherson industrial estate, within walking distance of Potong Pasir MRT, and connected by the PIE, CTE and KPE. For industrial occupiers, that combination matters more than marketing language. It improves supplier access, last-mile movement, employee commute convenience and brand visibility. For investors, it reduces the risk that the asset becomes geographically irrelevant even as industrial stock ages.
The attached master plan screenshot places CT Gold in the middle of a mature industrial corridor running around MacPherson Road, Aljunied Road and the PIE rather than on the fringe of the industrial market. Combined with the site’s B1 zoning and strong frontage, that planning context helps explain why buyers were willing to treat CT Gold as a location-led product, not just a building-led one.

What This Means For Investors And End Users
For investors, CT Gold is better understood as a scarcity-driven, benchmark-reset opportunity rather than a pure day-one yield play. With TOP expected around November 2030, purchasers are effectively positioning for a future completed asset, not immediate rental income. The entry profile also remains relatively accessible compared with residential property: ABSD applies to residential purchases, while foreign buyers are generally able to purchase industrial and commercial properties without approval under the Residential Property Act. That said, investors need to factor in the Seller’s Stamp Duty regime for industrial properties, which applies if the asset is sold within three years: 15% in the first year, 10% in the second year, and 5% in the third year. The takeaway is clear: CT Gold is better suited to a medium-term holding strategy than a short-term flip.
For end users, the investment case is arguably even more compelling. The buyer profile appears to be heavily weighted toward owner-occupiers, and the project’s B1 zoning aligns well with practical operating uses such as light manufacturing, e-commerce, logistics support and creative production. The unit sizes also keep the absolute quantum manageable for smaller occupiers, while still giving larger users the flexibility to combine multiple units for a bigger operational footprint. From that perspective, paying a premium over older resale stock nearby can be rational. An owner-occupier is not just buying space; they are potentially hedging against future rental escalation, reducing retrofit risk, and consolidating operations in a newer, better-specified, city-fringe industrial building.
The broader story is straightforward: CT Gold sold out because it was not really competing with another new B1 launch nearby. It was competing with older resale stock in a mature industrial precinct. Buyers were prepared to pay a meaningful premium for a rare combination of brand-new freehold tenure, modern specifications, flexible unit sizing, B1-compatible usage, and city-fringe accessibility. That is why the project moved so quickly, and why the headline premium looks more defensible once the surrounding supply context is properly understood.
Article contributed by Jerry Wong.

Jerry Wong is a realtor at Propnex Realty, bringing a rich background in interior and lighting design to his work. He loves exploring diverse spaces and observing the transformative power of real estate. Beyond his professional role, Jerry finds his greatest fulfillment in connecting people with the right properties, gaining immense satisfaction from helping clients achieve their dreams.