The Benchmark Framework: How We Chose Our Comparables
If you bought Thomson Impressions at launch, you were not buying the cheapest condo in the micro-market. You were buying a 288-unit, 99-year leasehold project on Lorong Puntong, launched in late October 2015, with a product mix that leaned heavily into compact, efficient apartments and family-sized homes, and with the promise of future rail connectivity near Bright Hill and Upper Thomson. That rail thesis later materialised when Bright Hill MRT opened as part of TEL2 on 28 August 2021, and the station is slated to become an interchange with the Cross Island Line.
For this analysis, we use two groups of comparables to benchmark Thomson Impressions against the surrounding resale market.

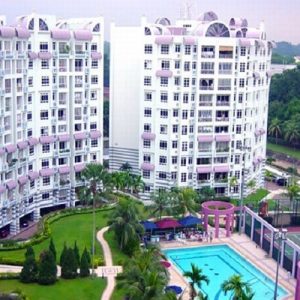
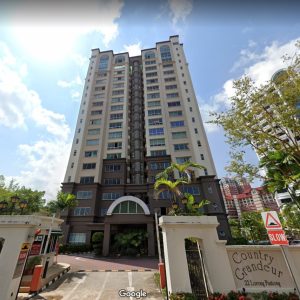
Cluster 1 represents the immediate “next-door boutique freehold” market. This group consists of Flame Tree Park, a 160-unit freehold development completed in 1989; Country Esquire, a 60-unit freehold development completed in 1992; and Country Grandeur, a 68-unit freehold development completed in 1996. These projects are older, smaller in scale, freehold, and located close to Thomson Impressions.
Cluster 2 represents a different type of comparison. These are larger developments closer to Bright Hill MRT and Bishan. The group includes The Gardens at Bishan, a 756-unit 99-year leasehold project from 1997; Bishan Park Condominium, a 320-unit 99-year leasehold project from 1991; Thomson Grand, a 99-year leasehold project from 2010; and Faber Garden Condominium, which is the freehold outlier within this larger-estate basket.
We have deliberately excluded certain Thomson-area projects from the comparison. Thomson View, for example, is not used as a benchmark because it was sold en bloc for S$810 million in November 2024. Once a project enters the en bloc cycle, transaction behaviour can become less representative of normal resale market pricing, as buyers and sellers may be influenced by redevelopment expectations rather than typical owner-occupier or investor demand.
A methodological note matters here. The historical numbers discussed below are taken from the attached PropNex ProTrend charts dated 3 May 2026. The yield analysis is therefore a gross yield estimate.
That means the yield discussion is not a net, after-expense, after-vacancy or financed return. It is still useful because it compares rentability versus capital value on a consistent basis across the same benchmark set. Thin samples, especially for the 4-bedroom sales/rentals, should be analysed directionally rather than as precision-grade trend lines.
The Sale Story
At launch, buyers were already underwriting a premium. EdgeProp reported that when Thomson Impressions launched in late October 2015, it achieved an average price of about S$1,400 psf, with 113 of 150 released units sold shortly after launch. In other words, the market did not treat it as a bargain-bin leasehold; it treated it as a new-product, location-led proposition.
The attached sales charts suggest that this premium was largely defended, not destroyed.
1 Bedroom Units
For 1-bedroom units, Thomson Impressions averaged about S$1,499 psf in 2015 and rose to around S$1,871 psf by 2025, while the only benchmark, The Gardens at Bishan, sat far lower, around S$834 psf to S$950 psf over the observed years. What is striking is that Thomson Impressions still did this while posting an average transacted price of about S$766,307, below The Gardens at Bishan’s S$842,000 average. That is not a contradiction but a result of much smaller unit sizes.

2 Bedroom Units
For 2-bedroom units, the outperformance is clearer and spans the full decade. Thomson Impressions rose from roughly S$1,411 psf in 2015 to S$2,033 psf in 2025, finishing ahead of both The Gardens at Bishan at about S$1,680 psf and Thomson Grand at about S$1,761 psf. That is not a trivial result. It means the project’s launch premium did not merely survive completion and resale seasoning; it widened again by the end of the period.

3 Bedroom Units
The 3-bedroom segment is where the asset makes its strongest case. Thomson Impressions moved from about S$1,361 psf in 2015 to S$2,197 psf in 2025, leaving it at the highest end of 2025 psf in both benchmark clusters. That does not mean it had the best percentage growth in every case. Some older comparables, especially from much lower starting bases, staged larger percentage catch-up moves. Country Grandeur climbed from roughly S$1,091 psf to S$2,063 psf, and Flame Tree Park from about S$984 psf to S$1,830 psf. So the fairest reading is this: Thomson Impressions did not always win on percentage catch-up, but it started richer and still finished richest. That is a more important sign of pricing power.

This distinction is important because much of the older resale stock in the area was built with larger unit sizes, making it less capital-efficient for buyers. Thomson Impressions offered a more compact and efficient layout mix, with 1-bedroom units of about 463 sq ft, 2-bedroom units of about 732 to 764 sq ft, and core 3-bedroom units of about 1,055 to 1,195 sq ft.
By comparison, The Gardens at Bishan has much larger layouts, including 1-bedroom units of around 947 sq ft and 2-bedroom units ranging from about 861 to 1,410 sq ft. Thomson Grand’s 2-bedroom units are also larger, typically between 904 and 1,044 sq ft, while the freehold 3-bedroom units in Cluster 1 generally range from about 1,259 to 1,829 sq ft.

This explains why Thomson Impressions could command a higher price psf square foot while still producing a lower average transaction quantum in several key segments. In other words, buyers may have paid more per square foot, but the smaller, more efficient unit sizes helped keep the overall purchase price more affordable.
The 3-bedroom sale comparison shows the premium persistence visually: Thomson Impressions begins above most nearby older stock and still ends on top.
4 Bedroom Units
For 4-bedroom sale transactions in Cluster 2, Thomson Impressions had very limited resale activity. This is expected because there are only five 4-bedroom + study penthouse units in the entire development, so the transaction sample is very small and should be read directionally rather than as a broad market trend.
Based on the available data, Thomson Impressions recorded only 6 transactions over the period. Its average price of $2.815 million was the highest among the selected Cluster 2 comparables, while its average psf of $1,378 sat below Thomson Grand’s $1,515 psf, but above The Gardens at Bishan, Faber Garden Condominium, and Bishan Park Condominium. This suggests that Thomson Impressions’ 4-bedroom + study units achieved a strong resale quantum, likely helped by the project’s newer age and limited supply, although the small sample size means the results should not be over-interpreted.

The Rental Story
The rental charts tell an equally important story and align well with broader market timing. URA reported that private residential rents surged 29.7% in 2022, then grew a more moderate 8.7% in 2023, fell 1.9% for the full-year 2024, and edged up 1.9% in 2025. Thomson Impressions also had its own micro catalyst, as Bright Hill station opened in August 2021, right during the period when the project shifted from “new launch story” to “fully operating, rail-served asset.”
1 Bedroom Rentals
For 1-bedroom rentals, the demand is especially strong. Thomson Impressions moved from about S$4.25 psf in 2018 to roughly S$6.73 psf in 2025, after peaking around S$6.76 psf in 2023. The Gardens at Bishan never got close. That is a major result because it shows that Thomson Impressions has become a genuinely monetizable landlord product, not just a high-psf resale asset.

2 Bedroom Rentals
For 2-bedroom rentals, Thomson Impressions rose from roughly S$3.47 psf in 2018 to about S$5.21 psf in 2025, versus around S$4.47 psf for The Gardens at Bishan and S$4.23 psf for Thomson Grand in 2025. Again, the pattern is consistent: Thomson Impressions did not just sell higher; it also rented higher.

3 Bedroom Rentals
The 3-bedroom rental picture is even more decisive. Thomson Impressions went from about S$3.32 psf in 2018 to S$4.66 psf in 2025, and by 2023–2025, it was sitting above both the adjacent freehold cluster and the larger Bright Hill/Bishan cluster. That matters because 3-bedroom tenants are usually the hardest segment to dominate: they compare schools, layout practicality, station access, and family livability, not just novelty. The attached chart suggests Thomson Impressions won that comparison.


4 Bedroom Rentals
By contrast, the 4-bedroom segment is much less conclusive. Thomson Impressions’ chart-derived average rental psf of 3.06 is still above the cluster’s simple benchmark average, but its sample size is tiny, and peers like Thomson Grand posted higher peak rent psf at times. This is the one part of the study where the data say: be careful, not categorical.

The Yield Story
Once price and rent are viewed together, the picture becomes much clearer. Using the chart tables and estimating gross yield from average sale psf and average rental psf, Thomson Impressions looks like this:
| Segment | Benchmark set | TI avg sale psf | Benchmark avg sale psf | TI avg rent psf | Benchmark avg rent psf | TI est. gross yield | Benchmark est. gross yield | TI avg transacted price |
| 1BR | Cluster 2 | 1,656 | 889 | 5.44 | 2.77 | 3.94% | 3.74% | S$747k |
| 2BR | Cluster 2 | 1,521 | 1,382 | 4.16 | 3.09 | 3.28% | 2.72% | S$1.14m |
| 3BR | Cluster 1 | 1,483 | 1,383 | 3.92 | 2.29 | 3.17% | 1.98% | S$1.63m |
| 3BR | Cluster 2 | 1,483 | 1,337 | 3.92 | 2.54 | 3.17% | 2.30% | S$1.63m |
| 4BR | Cluster 2 | 1,378 | 1,259 | 3.06 | 2.47 | 2.66% | 2.37% | S$2.81m |
Benchmark figures above are simple arithmetic averages of the comparator projects in the relevant cluster. Yields are gross estimates from the attached charts and should be read before expenses.
This table is the heart of the investment conclusion.
For 1-bedroom units, Thomson Impressions looks like a very strong investor product. It had a sharply higher sale psf than The Gardens at Bishan, but an even stronger rental psf, and it still came in with a lower average transaction quantum because the unit was so much smaller and more efficient.
For 2-bedroom units, the project arguably hit the sweet spot best. It produced a higher average rent psf than both leasehold peers, an estimated gross yield of around 3.28%, and an average entry quantum of about S$1.14 million, which is lower than the simple benchmark average of the two comparables.
For 3-bedroom units, the case is strongest of all. Against Cluster 1, Thomson Impressions’ estimated gross yield of 3.17% is about 1.19 percentage points higher than the freehold benchmark average. Against Cluster 2, it is about 0.87 percentage points higher. That is a very meaningful gap in a mature Singapore condo market. And it achieved that while carrying an average transaction value of about S$1.63 million, which is lower than the average of the larger nearby freeholds and also lower than the larger-estate Cluster 2 benchmark average.
For 4-bedroom units, the estimated gross yield is still respectable, but we would not overstate the result. The chart tables show only six sales and six rental transactions for Thomson Impressions in this bucket, which is too thin to support a hard-edged investment verdict.
What makes this conclusion more credible is that the same relative ordering still appears in current project-level yield snapshots. EdgeProp’s recent project pages show roughly 3.5% rental yield for Thomson Impressions, versus about 1.8% for Flame Tree Park, 1.9% for Country Esquire, 1.9% for Country Grandeur, and 1.9% for Faber Garden Condominium.
The larger leasehold comparables also sit below Thomson Impressions in those current snapshots: EdgeProp lists around 2.8% at The Gardens at Bishan, 2.8% at Bishan Park Condominium, and 2.7% at Thomson Grand. That does not prove the entire backtest on its own, but it does validate the direction of the chart-derived conclusion: Thomson Impressions has been a better rent-to-value machine than most of the surrounding resale set.
The Trade-Offs
A fair investment review should also say what Thomson Impressions did not do.
It did not beat every older comparator on raw percentage capital appreciation from the lowest possible base. Some of the older freehold neighbours had more room to re-rate because they started the period at materially lower psf levels. That means anyone trying to prove Thomson Impressions was the single best capital gainer in every cohort would be overstating the case. The stronger and more defensible claim is different: it preserved a launch premium, reached the highest end-period psf in the key family segment, and did so while renting materially better.
It also remains a 99-year leasehold asset, while some of its competitors are freehold. Over a much longer holding horizon, lease decay will matter. The first ten years, though, are usually driven more by completion, transport delivery, product freshness, and rental monetisation than by long-run tenure math. In that first-decade window, Thomson Impressions looks strong.
Some segments are also less statistically reliable than others. The 4-bedroom category, in particular, has a very small transaction sample. This should not be read as a weakness of the project itself, but rather as a limitation of what the available data can meaningfully support.
There is also one more structural tailwind worth noting. Bright Hill is not just an open TEL station; LTA says it is also a future Cross Island Line interchange. That means the project’s transport story has not been fully exhausted by the first decade of price and rent history.
The verdict
So, was buying Thomson Impressions in 2015 a good decision?
Based on the evidence, the answer is yes, and the most convincing yes is in the 2- and 3-bedroom segments.
The 1-bedroom units look like a very good investment call: they carried a high psf, delivered a very strong rent psf, had a lower average cash outlay than the one benchmark available, and an estimated gross yield above that benchmark.
The 2-bedroom units may be the cleanest all-around success case. They finished the period with the highest sale psf among the direct Cluster 2 peers, the highest rental psf, and a better chart-derived gross yield than the benchmark average, while staying at a reasonable transaction quantum.
The 3-bedroom units are the strongest strategic buy in the whole study. They ended at the highest psf among both comparator clusters, commanded the strongest rental premium, and produced chart-derived gross yields that were materially better than both the nearby freehold boutique projects and the larger Bright Hill/Bishan estates. Just as importantly, they did this at an average transaction quantum lower than many of the larger resale alternatives, which is exactly what you want from a new launch that was once accused of looking “expensive” on psf.
The 4-bedroom result is the only qualified verdict we would call acceptable but not conclusive, because the sample is too small and the relative advantage is weaker.
In other words: Thomson Impressions proved to be a good buy because it converted its initial launch premium into sustained rental demand, resilient resale values, and gross yields that generally outperformed its benchmark set — particularly in the 2-bedroom and 3-bedroom segments, which are the most relevant unit types for this location.
Article contributed by Jerry Wong.

Jerry Wong is a realtor at Propnex Realty, bringing a rich background in interior and lighting design to his work. He loves exploring diverse spaces and observing the transformative power of real estate. Beyond his professional role, Jerry finds his greatest fulfillment in connecting people with the right properties, gaining immense satisfaction from helping clients achieve their dreams.