Woodlands Drive 17 EC: CDL’s S$782 psf ppr Land Bet Points to a High-S$1,700s to Mid-S$1,800s Launch
CDL Divine Pte. Ltd. was awarded the Woodlands Drive 17 executive condominium site, identified on HDB’s sold-site schedule as Woodlands E8, for S$360.899 million. HDB data show a 25,207.2 sq m site, a 99-year lease, a gross plot ratio of 1.7, a maximum GFA of 42,853 sq m, and an estimated yield of about 420 homes. The tender was launched on 8 April 2025, closed on 5 August 2025, and awarded on 26 August 2025. Using the official maximum GFA, the land rate works out to about S$782.4 psf ppr.
Our base case is that this future CDL launch should open in the high-S$1,700s psf and settle at an average of roughly S$1,800-S$1,860 psf, with an upside case nearer S$1,900 psf only if demand behaves more like Rivelle Tampines than a typical northern EC. That range sits inside the analyst spread already circulating for the two Woodlands parcels: around S$1,750-S$1,850 psf on the lower end, above S$1,850 psf on the firmer end, and even S$1,900-S$2,000 psf on more bullish calls.

Tender Facts And Site Positioning
What makes the CDL parcel stand out from a generic suburban EC site is its unusually strong transit connectivity. The site is less than 300m from Woodlands South MRT, putting it one stop from Woodlands interchange and two stops from Woodlands North on the Thomson-East Coast Line. That matters because Woodlands North is also the Singapore terminus for the RTS Link to Johor Bahru, which is targeted to begin passenger service by the end of 2026.
The site is also beside Woodlands Health Campus, which officially opened in 2024 and is planned as a major healthcare hub for the north, integrated with the Woodlands Healing Garden. At the broader planning scale, URA’s North Region plan states that the Northern Gateway will be anchored by the growth of Woodlands Regional Centre as its commercial hub. Those are not automatic launch-price guarantees, but they materially strengthen the long-run liveability and employment story around the parcel.
Supply scarcity in the immediate Woodlands EC market should provide an additional demand cushion. This would be Woodlands’ first new EC launch in nearly a decade, after Northwave in 2016. EdgeProp also cited ERA’s estimate that around 1,411 four-room and larger flats in Woodlands are expected to reach MOP between 2022 and 2026, creating a ready pool of HDB upgraders who may naturally look to the next nearby EC launch.

Low-density Profile And North-Side Demand
The density profile is one of the clearest reasons the parcel stands out. Official HDB data shows Woodlands E8 at a plot ratio of 1.7, compared with 2.1 for the second Woodlands parcel, 2.5 for the Tampines Street 95 site that became Rivelle Tampines, and 3.0 for Senja Close. The URA plot-ratio screenshot also visually shows the Woodlands E8 parcel among plots that are generally more intense. So even if 1.7 is not the single lowest EC plot ratio on record, it is clearly at the lower-density end of the recent EC spectrum.
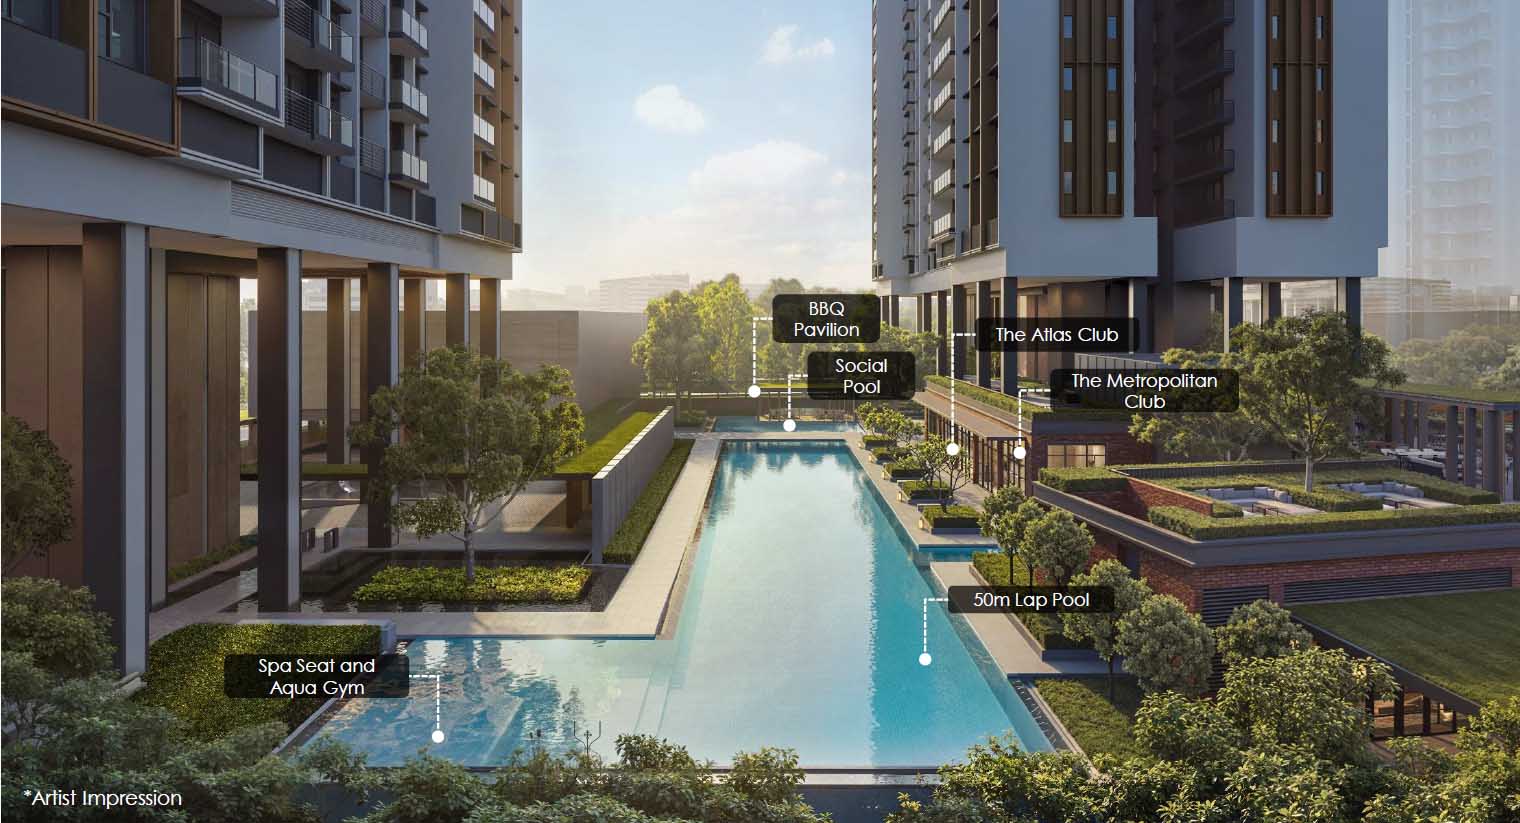
That lower density matters because it changes product positioning. A 1.7 site generally allows a development to feel less compressed than many recent ECs, which have often sat on plot ratios well above 2.0. In market terms, that can support a more spacious site plan, fewer units competing for the same facilities, and a less mass-market identity. That should be especially relevant in Woodlands, where the project will already be marketing itself around MRT convenience and a “north-region growth hub” story rather than just pure affordability.
Bid intensity was also extraordinary. The official bid list shows CDL’s winning offer beat Sim Lian’s by only S$619,000, or about 0.17%. Spread across an implied 420 homes, the land bill alone is about S$859,000 per unit before construction, financing, marketing, professional fees and developer margin. This is why Woodlands E8 can still be good value relative to private condos without being a “cheap” EC in absolute quantum terms.

Pricing Translation From Land Cost
The cleanest real-world benchmark is Rivelle Tampines. Based on official HDB site data, the Tampines Street 95 parcel was acquired at about S$768.4 psf ppr, before Rivelle launched at an average of S$1,893 psf and sold out within a month.
Another useful comparison is the Sembawang Road EC site, which has a lower official land rate of about S$691.9 psf ppr. Even with that softer land cost, our estimate is that the future launch there could still average above S$1,700 psf, especially given its low-density profile and grandfathered old-rule EC appeal.
If we applied Rivelle’s exact land-to-launch multiple to Woodlands E8, it would point to roughly S$1,928 psf. We think that is too aggressive for opening prices. Rivelle had a stronger, more mature Tampines pull, tighter east-region EC supply, and a more established proof point for buyers already comfortable paying near S$1,900 psf for an EC. Woodlands E8 also has a direct internal competitor in the nearby Sim Lian parcel. A more balanced underwriting range is about 2.30x to 2.38x land rate, which translates to roughly S$1,800-S$1,862 psf and sits comfortably within the analyst band already being discussed for Woodlands. That is why our practical base case remains closer to S$1,800-S$1,860 psf than to a full Tampines-style S$1,900-plus opening.
In quantum terms, that would imply something like S$1.62 million-S$1.67 million for an illustrative 900 sq ft unit and about S$1.89 million-S$1.94 million for an illustrative 1,050 sq ft unit. These are scenario calculations, not developer guidance, because CDL has not released its unit mix or pricing grid.
Regulatory Shift and Grandfathered Demand
MND’s 8 May 2026 move meaningfully changed the EC equation. The ministry said the new measures apply to EC GLS sites with tender closing dates on or after 8 May 2026. The new framework extends the MOP to 10 years, pushes full privatisation to 15 years, removes the Deferred Payment Scheme, and raises the first-timer quota from 70% to 90%, while extending the priority window from 1 month to 2 years.
CNA also reported that analysts expect near-term demand to rotate toward five grandfathered projects not subject to the new rules: Senja Close, Sembawang Road, Miltonia Close, and the two Woodlands Drive 17 projects. That is the key tailwind for CDL’s parcel. It should appeal to households that still want the old five-year MOP, broader second-timer access, and DPS flexibility. But because that policy-sensitive demand will be spread across five sites, the boost is real without being exclusive.
The likely market effect is stronger absorption, more than runaway psf inflation. Analysts told CNA that over half of EC buyers use DPS, with some projects reaching 60% to 70%, so removing DPS meaningfully narrows future upgrader demand. Even so, the same report stresses that the S$16,000 household income ceiling and 30% mortgage servicing ratio still cap how far EC prices can run. CNA also reported that analysts expect developers to bid up to about 10% lower for future new-rule EC sites, which should re-anchor affordability later on.
What Rivelle and Sembawang Suggest
Rivelle Tampines is the clearest real-world stress test for old-rule EC demand. According to EdgeProp,
The key lesson is not that every grandfathered EC can now price at Tampines levels. Rather, Rivelle shows that buyers are still willing to absorb record EC pricing when a project combines strong locational attributes, a meaningful value gap relative to private condos, and the more flexible old-rule EC structure. For Woodlands E8, this is encouraging because it supports a firm pricing strategy. However, Woodlands should not be benchmarked mechanically against Rivelle, given that Tampines has a deeper and more established east-region buyer base.
This is where the Sembawang Road EC site becomes especially interesting. Official site details show an 18,967.2 sq m parcel with a 1.4 plot ratio, a maximum GFA of 26,555 sq m, and a land rate of about S$691.9 psf ppr — meaningfully below Woodlands E8’s S$782.4 psf ppr. Market expectations were already constructive, with EdgeProp and PropNex viewing an average selling price above S$1,700 psf as feasible. Huttons also noted that more than 4,000 Sembawang BTO owners have reached MOP since 2023, creating a sizeable local upgrader base.
Against that backdrop, Sembawang Road could be the strongest relative beneficiary of the May 2026 EC policy shift. It offers lower land costs, potentially more accessible entry quantum, only around 265 homes, a boutique, low-density profile, and the full set of grandfathered old-rule advantages, including shorter MOP, better second-timer accessibility, and continued Deferred Payment Scheme appeal. Woodlands E8 may still command a stronger headline psf due to its MRT proximity and Woodlands Regional Centre narrative, but Sembawang Road may enjoy faster sell-through from affordability-sensitive buyers.
The final Woodlands nuance is that the second Woodlands Drive 17 parcel awarded to Sim Lian should not be treated as a new-rule competitor. Since it was awarded on 20 January 2026 for S$484 million, or about S$793.6 psf ppr, after its tender closed on 13 January 2026. We expect both Woodlands projects to launch in late 2026 or early 2027, with pricing ranging from around S$1,750-S$1,850 psf to above S$1,850 psf, and, in more bullish views, closer to S$1,900-S$2,000 psf. In other words, the Sim Lian site is better understood as a grandfathered substitute that reduces CDL’s exclusivity in the Woodlands micro-market, rather than as a policy-disadvantaged rival.

Conclusion: Woodlands E8 Is Strong, but Sembawang Road May Benefit More from the Old-Rule EC Window
Overall, CDL’s Woodlands E8 remains a strong EC land sale: low-density, unusually close to an MRT station, supported by Woodlands Health and the broader Regional Centre story, and protected by the old-rule cutoff. However, if the question is which exempt project receives the largest relative demand uplift from the May 2026 changes, Sembawang Road may arguably have the sharpest setup. It offers the same grandfathered advantages at a lower land-cost base, with fewer units to clear and a more affordability-led demand profile. The real test of the new EC regime will come from future GLS sites such as Canberra Drive and Sembawang Drive, which fall under the updated rules and will show how buyers respond once the shorter MOP, broader second-timer access, and Deferred Payment Scheme advantages are no longer available.
Disclaimer: This article is for general information only and does not constitute financial, investment, legal, tax, or property advice. Figures, projections, and market views are based on publicly available information and estimates at the time of writing, and may change. Readers should conduct their own due diligence and consult qualified professionals before making any property decision.
Article contributed by Jerry Wong.

Jerry Wong is a realtor at Propnex Realty, bringing a rich background in interior and lighting design to his work. He loves exploring diverse spaces and observing the transformative power of real estate. Beyond his professional role, Jerry finds his greatest fulfillment in connecting people with the right properties, gaining immense satisfaction from helping clients achieve their dreams.