As of 8 September 2026, The Continuum is approaching the end of its developer sales cycle. Only 14 homes remain out of 816 units: two 1,690 sq ft four-bedroom premium units and twelve 1,905 sq ft five-bedroom Type E units. The latest discount introduces a particularly aggressive final-phase promotion on five of those five-bedroom homes, taking their net prices down to $4.787 million to $4.947 million, or just $2,513 to $2,597 psf.
Our conclusion after comparing the promotion with launch pricing, very recent same-stack transactions, the actual location of the remaining stacks, competing District 15 developments and Tembusu Grand rents is:
Yes — the five units receiving the full $780,000 headline promotion are genuinely attractive buys at their net prices, particularly for an own-stay buyer or a long-term investor who values freehold tenure. But the strongest reason to buy is not the “$780,000 discount” itself. The real evidence is that these units are now roughly 6%–9% below extremely recent same-stack transactions and 7.5%–10.5% below the original five-bedroom launch starting price.
There is one important distinction. This is not a high-yield investment. Using actual Tembusu Grand five-bedroom rents as the benchmark suggests only about 2.4%–2.6% gross rental yield at the discounted Continuum prices. The proposition is therefore much stronger as a value-entry, freehold, large-family-home thesis than as a pure rental-income play.
For a buyer choosing among the five deeply discounted units, we would separate the decision this way:
| Buyer priority | Our pick | Why |
| Lowest entry price / maximum value | Blk 2 #03-25 | $4.787m, only $2,513 psf; one floor above recently sold for $5.105m |
| Best balance of price and elevation | Blk 5 #06-19 | Highest floor still receiving $780k promotion; only $56k more than #03-19 |
| Cheapest entry into stack 19 | Blk 5 #03-19 | $4.891m / $2,567 psf and roughly $424k below the recent #08-19 transaction |
| Middle-ground own-stay choice | #04-19 or #05-19 | Only about $18k per additional floor within the promotional band |
The rest of this analysis explains why.

What the $780,000 promotion really means
The five units receiving the massive $780k full promotion are:
| Unit | Area | List price | Promotion | Net price | Net PSF | Discount vs list |
| Blk 2 #03-25 | 1,905 sq ft | $5.567m | $780k | $4.787m | $2,513 | 14.0% |
| Blk 5 #03-19 | 1,905 sq ft | $5.671m | $780k | $4.891m | $2,567 | 13.8% |
| Blk 5 #04-19 | 1,905 sq ft | $5.689m | $780k | $4.909m | $2,577 | 13.7% |
| Blk 5 #05-19 | 1,905 sq ft | $5.707m | $780k | $4.927m | $2,586 | 13.7% |
| Blk 5 #06-19 | 1,905 sq ft | $5.727m | $780k | $4.947m | $2,597 | 13.6% |
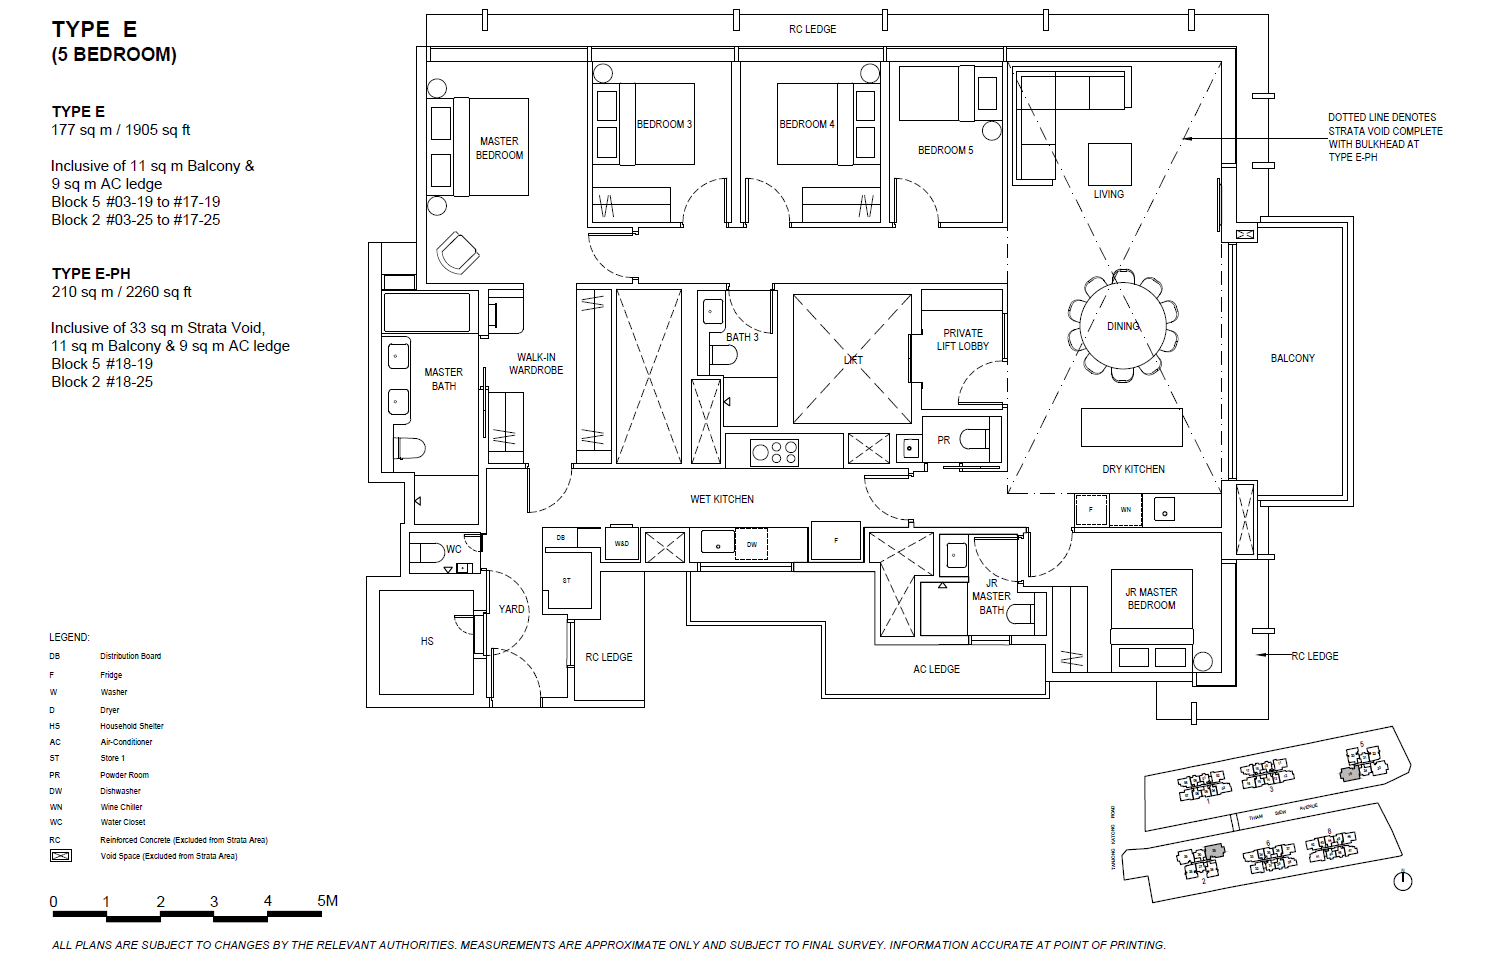
These are all Type E five-bedroom residences, each spanning 177 sq m (1,905 sq ft). The layout includes a private lift lobby, separate wet and dry kitchens, a yard, household shelter and an 11 sq m balcony. The five bedrooms comprise a master suite, a junior master bedroom and three additional bedrooms.
These units are located in Stack 25 of Block 2 and Stack 19 of Block 5. The Continuum is a freehold development comprising 816 units, with vacant possession estimated for Q2 2027.
What buyers paid recently — and what they paid at launch
The most convincing argument for these five discounted units is not a theoretical project-average PSF comparison. It is the existence of very recent transactions for the same 1,905 sq ft layout and, in several cases, the same exact stack.
Recent caveats include:
| Date | Unit | Size | Transaction price | PSF |
| 22 Aug 2026 | #xx-19 | 1,905 sq ft | $5.389m | $2,829 |
| 12 Aug 2026 | #xx-25 | 1,905 sq ft | $5.445m | $2,858 |
| 1 Aug 2026 | #xx-25 | 1,905 sq ft | $5.105m | $2,679 |
| 25 Jul 2026 | #xx-19 | 1,905 sq ft | $5.315m | $2,790 |
| 22 Jul 2026 | #xx-25 | 1,905 sq ft | $5.463m | $2,868 |
| 22 Jul 2026 | #xx-25 | 1,905 sq ft | $5.320m | $2,793 |
| 18 Jul 2026 | #xx-25 | 1,905 sq ft | $5.351m | $2,809 |
*Source: PropNex Protrend/URA. Unit Masked for privacy purposes
The cleanest comparison: #0x-25 versus #04-25
This is about as close to an apples-to-apples comparison as one can obtain in a new launch.
#0x-25 sold on 1 August 2026 for $5.105 million, or $2,679 psf, but 03-25 is now offered at $4.787 million, or $2,513 psf.
The new unit is on the same stack and is now
$318,000 cheaper, or 6.2% lower in both quantum and PSF.
A small-floor difference clearly explains only a small fraction of a $318,000 gap. Indeed, the previous public price for #0x-25 was $5.087 million, only $18,000 below the $5.105 million #04-25 transaction — exactly the kind of ordinary floor premium one would expect to see reflected in a developer price ladder.
That makes the new $4.787 million net price unusually compelling.
Stack 19 tells the same story
0x-19 sold for $5.315 million / $2,790 psf on 25 July. The current promotional units directly below it are:
#03-19: $4.891m / $2,567 psf — $424k, or 8.0%, below #0x-19.
#06-19: $4.947m / $2,597 psf — $368k, or 6.9%, below #0x-19, despite being only a few floors lower.
Then #xx-19 sold on 22 August for $5.389 million / $2,829 psf. Compared with that transaction, even #06-19 is $442,000, or 8.2%, cheaper, while #03-19 is almost half a million dollars cheaper.
That is much stronger evidence of value than the $780,000 marketing figure.
The comparison with launch day is equally interesting
When The Continuum launched over 6–7 May 2023, the developers sold 216 of 816 units, or 26.5%, at an average $2,732 psf.
More importantly for this exercise, the original launch price guide put the 1,905 sq ft five-bedroom private-lift units from $5.35 million, equivalent to about $2,808 psf.
That makes today’s deep-discount homes:
| Current unit | Net price | Difference from original $5.35m 5BR “from” price | PSF vs $2,808 launch guide |
| #03-25 | $4.787m | -$563k / -10.5% | -10.5% |
| #03-19 | $4.891m | -$459k / -8.6% | -8.6% |
| #04-19 | $4.909m | -$441k / -8.2% | -8.2% |
| #05-19 | $4.927m | -$423k / -7.9% | -7.9% |
| #06-19 | $4.947m | -$403k / -7.5% | -7.5% |
There is an important methodological caveat. The $5.35 million figure was an indicative launch starting price, not a transaction for the same current stack. The available first-day caveat series does not show a 1,905 sq ft Type E among the transactions recorded on 6 May; one of the highest-end actual first-day transactions was the 1,690 sq ft #06-23 at $4.774 million or $2,825 psf.
So we would not claim that the present units are “10% below what exactly the same apartment sold for on launch day.” That would be too strong.
What we can say is more interesting: a buyer can now acquire one of the project’s remaining 1,905 sq ft freehold five-bedroom homes for 7.5%–10.5% below the price at which five-bedroom inventory was originally marketed to begin in 2023 — despite The Continuum’s broader transaction market having subsequently moved up. Recent project-wide transactions averaged around $2,792 psf over the six months to late August 2026.
The PropNex ProTrend report tells a similar story. Across its Q2 2023–Q3 2026 comparison cohort, The Continuum averaged $2,813 psf, with quarterly readings reaching as high as $2,908 psf.
A $2,513–$2,597 entry is therefore not merely “cheap versus list.” It sits approximately 7.7%–10.7% below the supplied Continuum comparison average.

Where the remaining units actually sit and what they face
A common concern with final developer inventory is that “the leftovers must be the bad stacks.”
The site plan suggests a more nuanced answer here.
The Continuum comprises a North and South Continuum on opposite sides of Thiam Siew Avenue. The overall site plan shows Blocks 1, 3 and 5 on the North plot, and Blocks 2, 6 and 8 on the South plot, connected across the avenue by the Continuum Bridge.
The Type E layout is located at stack 19 in Block 5 and stack 25 in Block 2 as the standard 1,905 sq ft five-bedroom configuration.
Stack 25: #03-25
Stack 25 occupies the northeastern side of Block 2. Importantly, although Block 2 is the westernmost residential block on the South Continuum and therefore geographically closer to Tanjong Katong Road, Stack 25 itself is on the opposite side of that block — facing inward toward the central Thiam Siew Avenue / water-and-landscape zone rather than sitting on the Tanjong Katong Road edge.
The unit’s principal outward and balcony-facing orientation is approximately northeast. Immediately around this side of Block 2 are the South Continuum’s landscaped “River Pool”/“Lake Pool” environment and the bridge connection across Thiam Siew Avenue.
For #03-25, we see two sides to this:
The positive: it is not a unit whose principal exposure is directly onto Tanjong Katong Road. It has an inward, landscaped orientation and is priced at only $2,513 psf.
The compromise: third-floor elevation means the buyer should inspect the exact sightline toward nearby landscaping, bridge circulation and other communal areas. Greater activity around the central amenity spine may matter more on a low floor than it would on #14-25.
Financially, however, that compromise is being very well compensated.

Stack 19: #03-19 through #06-19
Stack 19 is positioned on the southwestern corner of Block 5, at the eastern end of the North Continuum. Although Block 5 is the closest block to Haig Road, Stack 19 is not located on the development’s easternmost frontage. Stacks 22 and 23 occupy the side closer to Haig Road, while Stack 19 sits on the opposite southwestern corner.
Its principal exposure is approximately southwest, towards Thiam Siew Avenue and the development’s landscaped central portion. The Heritage Zone, which includes Thiam Siew House and its surrounding landscaped spaces, lies immediately west of Block 5, while Thiam Siew Avenue runs along the southern side.
This makes the discounted units particularly interesting because Stack 19 is not simply a leftover stack positioned directly against Haig Road. The more significant compromise is the remaining floor selection: the largest discounts are concentrated on Levels 3 to 6, with the higher-floor units largely sold.
Among these, #06-19 arguably offers the strongest value for an owner-occupier buyer.
At $4.947 million, #06-19 costs only $20,000 more than #05-19, $38,000 more than #04-19 and $56,000 more than #03-19. Pricing changes substantially from the next floor: #07-19 is offered at $5.314 million under the regular promotion, while #0x-19 sold for $5.315 million.
In other words, a buyer can secure the sixth-floor unit immediately below a price point of approximately $5.315 million for $368,000 less.
That price relationship is arguably more meaningful than comparing the promotional price to the original list price and stating that the unit has received a $780,000 discount.

How the discounted PSF compares with Grand Dunman, Emerald of Katong, Tembusu Grand and Waterbank
The latest PropNex ProTrend comparison is particularly useful because it places The Continuum alongside Grand Dunman, Emerald of Katong, Waterbank at Dakota and Tembusu Grand on the same dataset, covering transactions from Q2 2023 through Q3 2026.
The reported average PSFs are:
| Development | Tenure/positioning | Average PSF | Continuum at $2,513 | Continuum at $2,597 |
|---|---|---|---|---|
| The Continuum | Freehold | $2,813 | 10.7% below | 7.7% below |
| Grand Dunman | 99-year leasehold | $2,478 | 1.4% above | 4.8% above |
| Emerald of Katong | 99-year leasehold | $2,551 | 1.5% below | 1.8% above |
| Waterbank at Dakota | 99-year, completed development | $2,050 | 22.6% above | 26.7% above |
| Tembusu Grand | 99-year leasehold | $2,418 | 3.9% above | 7.4% above |
The comparison becomes particularly interesting at the discounted Continuum prices. At $2,513 psf, the unit would be priced approximately 10.7% below The Continuum’s overall $2,813 psf average and even slightly below Emerald of Katong’s $2,551 psf average. It would sit only 1.4% above Grand Dunman and 3.9% above Tembusu Grand.
Even at $2,597 psf, the unit remains about 7.7% below The Continuum’s overall average. It would trade at a modest premium of approximately 1.8% to Emerald of Katong, 4.8% to Grand Dunman and 7.4% to Tembusu Grand.
This is significant because The Continuum is the freehold development in this comparison, whereas Grand Dunman, Emerald of Katong and Tembusu Grand are 99-year leasehold projects. Waterbank at Dakota is also leasehold and serves more appropriately as an older resale benchmark rather than a direct new-launch comparison.
The discounted pricing therefore materially compresses the usual price gap between The Continuum and its leasehold competitors. At around $2,513 to $2,597 psf, buyers are effectively entering a freehold development at pricing much closer to the prevailing averages of nearby 99-year projects than The Continuum’s own historical average would suggest.

Grand Dunman: the freehold premium has nearly disappeared
Against Grand Dunman’s $2,478 average, the special Continuum units are only $35–$119 psf more expensive, or about 1.4%–4.8%.
That is a surprisingly small PSF premium for The Continuum’s freehold tenure.
This does not automatically make The Continuum superior. Grand Dunman’s proximity to Dakota MRT, plus its scale and facilities, add value, and different unit mixes can distort a project-level PSF comparison. Grand Dunman is a 1,008-unit 99-year development on Dunman Road.
But from a long-hold perspective, paying only a low-single-digit PSF premium for freehold rather than 99-year tenure is much easier to defend than paying the much larger premium The Continuum appeared to demand at various earlier points in its sales cycle.
Emerald of Katong: essentially PSF parity
Emerald’s supplied average of $2,551 psf is almost exactly in the middle of the Continuum promotional range.
03-25 at $2,513 is actually 1.5% below it. 03-19 at $2,567 is only 0.6% above it.
Even #06-19 at $2,597 is just 1.8% higher.
Emerald of Katong is a 99-year leasehold, 846-unit project along Jalan Tembusu.
For a buyer with a long holding period, Continuum trading around PSF parity with Emerald while offering freehold tenure is one of the strongest arguments for the promotion.
The caveat is quantum: the Continuum units are 1,905 sq ft five-bedders and therefore require almost $5 million of capital. A lower-PSF large unit isn’t interchangeable with a smaller, lower-quantum unit, even when both sit in District 15. The buyer pool at eventual resale will naturally be narrower at a $5 million ticket size.
Waterbank at Dakota: useful, but not really a direct competitor
At first glance, Waterbank’s $2,050 average makes The Continuum look 23%–27% more expensive.
But that comparison needs context.
Waterbank at Dakota is a 99-year leasehold project completed in 2013, with 616 units. UOL’s own project archive confirms its 99-year tenure and 2013 completion.
Recent individual Waterbank transactions in 2026 have ranged widely by unit type — for example, $2,410 psf for a 1,141 sq ft high-floor sale and around $2,130–$2,170 psf for several other units — illustrating the significant unit- and floor-specific dispersion in a mature resale development.
We would therefore use Waterbank as a downside/resale-market anchor, not as the benchmark that The Continuum needs to match. A brand-new freehold 1,905 sq ft private-lift unit should command a material premium over a 2013 99-year development.

Tembusu Grand: the most important five-bedroom comparison
Tembusu Grand provides one of the most relevant comparisons because it is nearby, and its recent transactions include multiple five-bedroom units with a consistent 1,711 sq ft layout.
The latest transaction data shows that these five-bedroom units have traded between $2,354 and $2,466 psf, with prices ranging from approximately $4.028 million to $4.220 million. Notably, the transactions cover units from Levels 1 to 17, giving a useful indication of how pricing varies across different floors.
Using the 15 five-bedroom transactions shown, the average works out to approximately $2,397 psf.
That is a much more appropriate benchmark than comparing The Continuum’s five-bedroom units against Tembusu Grand’s overall project PSF, which is influenced by transactions involving smaller four-bedroom and other unit types.
Against the approximately $2,397 psf five-bedroom average, The Continuum’s discounted five-bedroom units at $2,513 to $2,597 psf carry a premium of approximately:
4.8% at $2,513 psf or 8.3% at $2,597 psf
That premium is arguably reasonable given the differences between the two products.
The Continuum’s Type E provides 1,905 sq ft, compared with 1,711 sq ft for these Tembusu Grand five-bedroom units. That’s an additional 194 sq ft, or about 11.3% more floor area. The Continuum also provides a private lift lobby and is freehold, whereas Tembusu Grand has a 99-year leasehold tenure.
The absolute-price comparison is equally important. The Tembusu Grand five-bedroom transactions shown range from about $4.03 million to $4.22 million. The Continuum therefore still requires a significantly larger overall capital commitment, even after the discount, because buyers are purchasing a substantially larger home at a somewhat higher PSF.
This frames the promotion more accurately. The Continuum is not cheaper than Tembusu Grand on a like-for-like five-bedroom PSF basis. Instead, buyers are paying approximately a 5% to 8% PSF premium for a larger 1,905 sq ft home, private-lift configuration and freehold tenure.
That relatively modest PSF premium may ultimately be a more compelling argument than comparing The Continuum against Tembusu Grand’s overall project average, particularly for buyers specifically evaluating large five-bedroom homes.
What Tembusu Grand rents imply for Continuum rental yield — and the final verdict
Tembusu Grand provides a useful rental proxy because it now has actual five-bedroom leasing evidence from the same District 15 market.
The latest rental records show four five-bedroom contracts between May and July 2026, all within the 1,700–1,800 sq ft size band:
| Contract period | Unit type | Monthly rent | Rental PSF |
|---|---|---|---|
| Jul 2026 | 5BR | $9,900 | $5.66 |
| Jul 2026 | 5BR | $9,700 | $5.54 |
| Jun 2026 | 5BR | $10,000 | $5.71 |
| May 2026 | 5BR | $9,500 | $5.43 |
The evidence therefore establishes an actual rental range of approximately $9,500 to $10,000 per month, averaging $9,775 per month. This is more useful for underwriting than asking rents, as these figures reflect recorded rental contracts.
It would still be overly optimistic to take Tembusu Grand’s rental PSF and simply multiply it by The Continuum’s larger 1,905 sq ft floor area. Larger apartments do not necessarily command the same rent per square foot, and doing so could overstate the achievable monthly rent.
A more conservative approach is therefore to use $9,500 per month as the lower case and $10,000 per month as the upper case, without assigning any additional rental premium to The Continuum for its larger floor area, private lift or freehold tenure.
| Discounted Continuum unit | Purchase price | Gross yield at $9,500/mo | Gross yield at $10,000/mo |
|---|---|---|---|
| #03-25 | $4.787m | 2.38% | 2.51% |
| #03-19 | $4.891m | 2.33% | 2.45% |
| #04-19 | $4.909m | 2.32% | 2.44% |
| #05-19 | $4.927m | 2.31% | 2.44% |
| #06-19 | $4.947m | 2.30% | 2.43% |
Using the $9,775 monthly average would place the estimated gross yields roughly in the middle of these ranges, at about 2.37% to 2.45%, depending on the Continuum unit selected.
These are gross yields before maintenance fees, property tax, vacancy periods, leasing commissions, repairs, financing costs and any buyer-specific acquisition taxes. They should therefore not be interpreted as net investment returns.
More importantly, these are forward-looking estimates. Current Tembusu Grand rental transactions show what tenants are prepared to pay for a recently completed large five-bedroom condominium in this part of District 15, but they do not guarantee what The Continuum will achieve when its units become available for occupation. Rental conditions can change materially in the meantime.
The investment case for these discounted Continuum units therefore does not rest on unusually high rental yield. At current comparable rents, gross yields are likely to sit in the low-to-mid 2% range. The stronger argument is that the promotion reduces the acquisition price of a 1,905 sq ft freehold five-bedroom home while comparable 1,700–1,800 sq ft five-bedroom units at Tembusu Grand are already demonstrating actual rents of around $9,500 to $10,000 per month.
So, is it a good buy?
For an owner-occupier family buying a large freehold home in District 15: we think the answer is yes, and unusually clearly so at these five promotional prices.
The strongest evidence is #03-25. A virtually identical home was sold for $5.105 million in August. Buying the third floor at $4.787 million means entering $318,000, or 6.2%, below that same-stack transaction.
The strongest quality-adjusted choice may be #06-19 instead. It is the highest unit still receiving the $780,000 promotion, costs only $56,000 more than #03-19, and remains $368,000 below #08-19, which sold at $5.315 million.
For an investor focused primarily on rental income, we would be more cautious. A 2.4%–2.6% gross yield is respectable for a new large-format freehold home, but it is not compelling enough by itself to justify almost $5 million of capital. Net yield will be lower.
The investment argument has to be instead:
buying a scarce 1,905 sq ft freehold family unit at a PSF close to 99-year Emerald of Katong, only a low-single-digit premium to Grand Dunman, and only a roughly 5%–8% PSF premium over genuinely comparable Tembusu Grand five-bedroom transactions.
That is the key reason the present pricing looks attractive.
Our ranking of the five $780,000 discount units
Best pure value: #03-25 at $4.787m / $2,513 psf.
It has the lowest entry price, the highest modelled yield and, most importantly, an extraordinarily clean same-stack comparison: #0x-25 just sold at $5.105 million. Its third-floor inward-facing position is the trade-off.
Best overall own-stay buy: #06-19 at $4.947m / $2,597 psf.
You give up $160,000 versus #03-25, but secure the sixth floor and remain below $2,600 psf. More importantly, it costs only $56,000 more than #03-19 yet sits three floors higher. The price then jumps by roughly $367,000 to #07-19 under the ordinary promotion.
Best lower-quantum stack-19 option: #03-19 at $4.891m / $2,567 psf.
It is the lowest entry into the same stack where #0x-19 and #xx-19 have recently demonstrated market values of $5.315 million and $5.389 million, respectively.
The central finding is therefore not that a developer has generously “given away $780,000.”
It is that the final-phase incentive has pushed a handful of low-to-mid-floor five-bedroom homes below both The Continuum’s recent price curve and the broader new-launch District 15 PSF hierarchy. The true extra promotion versus recent advertised pricing is closer to $300,000–$330,000, but direct transactions show that this is enough to create a genuine market-value gap.
At $2,513–$2,597 psf, a buyer is no longer being asked to pay the large freehold premium that made The Continuum a harder call at launch. The buyer is now paying roughly Emerald-of-Katong money, only modestly above Grand Dunman, and a fairly rational 5%–8% PSF premium to Tembusu Grand’s comparable five-bedroom transactions—while getting a 1,905 sq ft private-lift freehold home.
That makes the $780,000 promotional units a good buy on relative value — especially #03-25 for the investor/value buyer and #06-19 for the owner-occupier — provided the purchaser is comfortable with the approximately $4.8–$5.0 million quantum and is buying primarily for long-term capital preservation, family use and freehold scarcity rather than chasing rental yield.
Disclaimer: This article is provided for general information and discussion purposes only and does not constitute financial, investment, legal, tax or property advice, nor an offer or recommendation to purchase any property. Prices, discounts, unit availability, transaction data, rental information, yields, promotional terms and other figures are based on information available at the time of writing and may change without notice. Historical transactions, comparable developments and rental records do not guarantee future prices, rental income, capital appreciation or investment performance. Rental yields stated are estimates and are generally calculated on a gross basis before expenses such as maintenance fees, property tax, vacancy, commissions, financing costs and applicable taxes. Comparisons between developments may also be affected by differences in tenure, unit size, floor level, orientation, layout, age, location and other property-specific factors. Buyers should independently verify all information with the developer, relevant authorities and their professional advisers, and assess their own financial circumstances and objectives before making any purchase or investment decision. The author may be involved in the marketing or sale of properties discussed in this article.
Article contributed by Jerry Wong.

Jerry Wong is a realtor at Propnex Realty, bringing a rich background in interior and lighting design to his work. He loves exploring diverse spaces and observing the transformative power of real estate. Beyond his professional role, Jerry finds his greatest fulfillment in connecting people with the right properties, gaining immense satisfaction from helping clients achieve their dreams.