Context of the asset and why comparisons are inherently imperfect
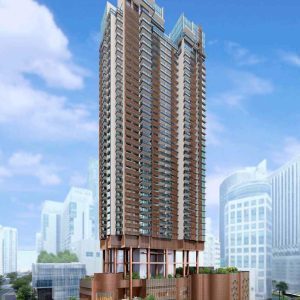
Altez is a 99‑year leasehold condominium at 16 Enggor Street in Singapore’s District 2 (Downtown Core / Tanjong Pagar area), completed in 2014, with 280 units in a single 62‑storey tower. In other words, it is a “tall, central, CBD-fringe” leasehold product, where pricing tends to be driven heavily by views/facing, floor heights, unit mix scarcity, and tenant profile (expat singles/couples and corporate leases), rather than classic family-owner-occupier dynamics.
The discounted 3-bedroom loft/duplex configuration is a distinctly niche offering. Our recent walkthrough of the 3-Bedroom Duplex Loft (Type CL6), measuring approximately 1,561 sq ft, highlights its unconventional layout: the entry level accommodates the living, dining, and kitchen areas, while the bedrooms are located on the lower level—reversing the more typical duplex arrangement where bedrooms sit above the living spaces. This atypical configuration is important, as it directly impacts:
Tenant pool: some tenants love the separation; others dislike internal stairs (young kids, elderly parents, pets, moving furniture, cleaning, etc.).
Resale pool: the buyer universe is smaller than for a “normal” single-level 3‑bedroom and smaller than for a “normal” duplex with bedrooms above (a more familiar typology).
Benchmarking: There are fewer directly comparable 3‑bedroom loft transactions nearby; most nearby projects have very different unit sizing and/or are positioned differently (integrated developments vs standalone, luxury vs mainstream, etc.).
Because of that, the right way to evaluate “good buy” is to combine (a) hard numbers (rent and sale/rent psf, yields) with (b) a candid assessment of liquidity risk (how hard it is to rent out and resell) and (c) what the discount is compensating you for.

What data is used and how yields are computed
This analysis will be using two PropNex Investment Suite ProTrend charts covering 3-bedroom transactions for the selected developments:
Sales data includes yearly trends alongside an “Overall” summary table showing minimum, average, and maximum PSF, corresponding price quantums, and transaction volumes (2015–2026).

Rental data presents yearly trends with an “Overall” table detailing minimum, average, and maximum rental PSF and monthly rents, together with transaction volumes (2015–2025).

The “Overall” figures are used to derive gross rental yield, calculated as:
Gross yield ≈ (Monthly rent × 12) ÷ Purchase price
To account for differences in unit sizes across developments, a normalised metric is also applied:
PSF-based gross yield ≈ (Monthly rent PSF × 12) ÷ Sale PSF
Both metrics represent gross yields, meaning they exclude vacancy, maintenance costs, property tax, insurance, agency fees, and financing expenses. These exclusions are significant in the Singapore context, where stamp duties—particularly ABSD and BSD—can materially impact actual investor returns depending on the buyer profile.
The broader macro environment is also relevant. Following the implementation of tighter property cooling measures (including higher ABSD rates) on 27 April 2023, investment demand has moderated. In line with this, URA flash estimates indicate that private residential price growth slowed to approximately 3.4% in 2025, suggesting a more price-sensitive and measured market environment.
How big is the Altez price drop, and what does it imply?
The Altez 3‑bedroom loft was previously marketed at $5,141,228, and current offers are $3,194,404 to $3,499,663 (levels 55–58; variation by facing/view).
That implies a very large headline repricing:
From $5,141,228 → $3,194,404: drop of about 37.9%
From $5,141,228 → $3,499,663: drop of about 31.9%
A ~32%–38% reduction is big enough that it usually indicates one (or more) of the following is true (these are interpretive possibilities, not certainties):
The earlier price was an “aspirational” marketing anchor rather than a price supported by recent comparables and realistic exit liquidity.
The seller’s constraint changed (urgent timeline, portfolio rebalancing, financing constraints).
The market for large-quantum CBD leasehold units tightened (ABSD constraints on investors, fewer foreign buyers willing/able to pay large ABSD, and narrower owner-occupier demand in the core area).
Translating the current offers into psf
Based on the available unit sizes ranging from 1,507 to 1,658 sq ft, the current asking prices translate to an approximate range of $2,089 to $2,304 psf (as of 31st March 2026).
The key consideration, therefore, is whether this $2,089–$2,304 psf range represents a discount, fair value, or premium relative to recent transaction levels for comparable 3-bedroom units within the immediate micro-market.
Rental yield benchmarking versus nearby 3‑bedroom stock
What the attached transaction tables imply about unit size comparability
The use of long-term averages for sale prices is deliberate. Pricing across these developments has remained relatively stable over the past decade, while limited transaction volumes—particularly at Eon Shenton and in recent Wallich Residence deals—can introduce volatility and skew short-term observations. A 10-year average helps smooth these fluctuations and provides a more reliable benchmark. For rentals, however, 2025 data is referenced to better capture current market conditions, as rents appear to be on an upward trend.
The average sale price data also indicates that Altez’s 3-bedroom units are larger than their peers, which aligns with the 1,561 sq ft duplex loft configuration being significantly larger than a typical CBD 3-bedroom unit.
Sale and rental benchmarks from the attachments
The figures below are extracts from the PropNex ProTrend “Overall” chart/tables (sale + rental), with computed yields.
| Development | Avg Sale PSF (S$) | 2025 PSF (S$/sf/mth) | Avg Sale Price (S$) | Approx. gross yield (2025 PSF/Avg Sale PSF) | Notes from the dataset |
| Skysuites @ Anson | 2,388 | 7.57 | 2,368,635 | 3.8% | Sale vol 41; rental vol 180 |
| One Bernam | 2,486 | — | 3,519,636 | — | Sale vol 34; rental shows 0 in the Protrend table |
| Wallich Residence | 3,122 | 10.51 | 4,202,638 | 4.0% | Sale vol 59; rental vol 120 |
| Eon Shenton | 2,123 | 6.57 | 1,957,553 | 3.7% | Sale vol 10; rental vol 58 |
| Altez | — | 6.22 | — | — | Rental vol 131; sale table shows no 3‑bed sale data |
What Altez yields look like at today’s offer prices
Using the tabulated data of Altez’s 2025 rentals and the offered purchase prices:

If rent is around the average $10,200/month:
At $3,194,404: ~3.83% gross yield
At $3,499,663: ~3.49% gross yield
If rent is closer to the min $9,200/month:
At $3,194,404: ~3.45%
At $3,499,663: ~3.15%
If rent is closer to the max $11,200/month:
At $3,194,404: ~4.2%
At $3,499,663: ~3.84%
To frame the result: at the new price range, Altez’s gross yield is broadly in the same band as Skysuites @ Anson and Eon Shenton, and not far from Wallich Residence, assuming Altez can consistently sustain rents near its historical averages.
Interpreting the One Bernam “missing” rental data
There are currently no available rental statistics for One Bernam (with a recorded volume of 0), likely due to its recent completion and the absence of meaningful leasing activity at this stage. In the immediate post-TOP phase, rental data is typically limited as the leasing market stabilises and transaction volume builds.
Furthermore, One Bernam has a relatively small supply of just 29 three-bedroom units, many of which may be held for owner-occupation, thereby further limiting the availability of observable rental transactions.
So, the lack of One Bernam rental benchmarking is a real limitation: it removes what would otherwise be a very direct, “next-generation CBD integrated” comparator for tenant willingness-to-pay.
Qualitative adjustments that matter more than the math for this case
The loft layout is a double-edged sword
The CL6-type duplex loft design and 1,561 sq ft size can be a strong differentiator for a niche renter or owner-occupier who values volume, separation, and “trophy high-floor” living.
But it also creates structural risks:
Liquidity risk: fewer buyers than a standard 3‑bedroom, especially because the quantum is high even after the discount (>$3.1M).
Tenant friction: Some corporate tenants prefer “hotel-like simplicity” (single level, no stairs), particularly for shorter leases or frequent relocation.
Family suitability: bedrooms downstairs can feel less intuitive for families (especially with young children), reducing the “family expat” segment.
In practice, this means the discount needs to compensate not only for market conditions, but also for a narrower buyer/tenant pool.
Micro-positioning versus the comparables
Wallich Residence, as part of the integrated Guoco Tower development in Tanjong Pagar, is positioned within a more premium segment of the market. This is reflected in both its higher rental PSF and sale PSF, placing it firmly within a distinct “luxury band” compared to the other developments in the ProTrend dataset.
Eon Shenton and One Bernam differ in both development timeline and lease commencement. Eon Shenton carries a 99-year lease starting from 6 October 2011, while One Bernam’s lease commences from 10 December 2019. This distinction is relevant, as a newer lease tenure combined with a newer building typically appeals to a different buyer segment, even though both projects are technically 99-year leasehold.
Skysuites @ Anson, being directly adjacent to Altez, serves as the most comparable benchmark from a location standpoint. Notably, its average sale PSF remains higher than Altez’s implied PSF at its current asking range, indicating that the repricing at Altez is significant—not just relative to its previous asking price, but also compared to its closest market equivalent.
Is the repriced Altez 3‑bedroom loft a good buy?
What looks compelling
The price reset is extremely large in headline terms (roughly 32%–38% below the prior marketed figure), and when expressed on an approximate psf basis (using 1,561 sq ft), the offer range of ~$2,046–$2,242 psf sits:
Below Skysuites @ Anson’s average sale psf ($2,388 psf)
Below One Bernam’s average sale psf ($2,486 psf)
Far below Wallich Residence’s average sale psf ($3,122 psf)
Around the vicinity of Eon Shenton’s average sale psf ($2,123 psf)
At the new price range, gross rental yields based on the rental averages are roughly 3.5%–3.8%, which is competitive with nearby benchmarks (particularly Skysuites @ Anson and Eon Shenton) and not dramatically behind Wallich Residence. The yield comparison is important because it suggests the price cut didn’t just “feel big”—it moved the unit into a band where the income return is no longer obviously inferior to nearby substitutes.
What you should be cautious about
The yield is “good enough,” but it is not an obvious outlier. In other words, if you buy this, the return case has to be supported by one of these:
You can reliably achieve rents closer to the upper half of Altez’s observed range in your table (closer to ~$10k–$11k), not the lower end.
You value the uniqueness and are comfortable holding longer (because resale liquidity may be slower).
You believe the new price is now below the level required to clear the “loft layout liquidity discount,” and you have a clear target tenant profile (e.g., a corporate lease, a dual-income expat couple seeking a prestige high-floor home office + separation of sleeping quarters).
Also, macro constraints on investor demand remain relevant. ABSD has been tightened (notably in Apr 2023), and stamp duties are computed on the higher of price or market value, directly impacting investor math. This is one reason high-quantum CCR leases can see sharper “marketing-to-reality” repricing: a smaller investor pool is able/willing to transact after ABSD and rising holding costs.
Decision framework
Based on our attachment-derived yield benchmarking and the relative psf positioning, the repriced Altez 3‑bedroom loft can be a reasonably attractive buy if your buying thesis is aligned with what the product is:
A niche, high-floor, CBD lifestyle home with acceptable (not extraordinary) income carry.
A longer-hold asset where the discount compensates for both (a) leasehold nature and (b) duplex/loft liquidity.
It is less compelling if your thesis requires:
Fast resale liquidity (because niche layout + large quantum can slow buyer matching).
Family-tenant “mass demand” leasing (because internal stairs and bedroom-on-lower-floor layout reduce universality).
Disclosure: This post is for educational and analytical purposes. It is not financial advice. Estimates are based on the provided ProTrend graph values, our inferred prices and comparability assumption, and indicative prices (accurate as of 31st March 2026). Actual rents and yields can vary by floor level, views, furnishings, etc.
Article contributed by Jerry Wong.

Jerry Wong is a realtor at Propnex Realty, bringing a rich background in interior and lighting design to his work. He loves exploring diverse spaces and observing the transformative power of real estate. Beyond his professional role, Jerry finds his greatest fulfillment in connecting people with the right properties, gaining immense satisfaction from helping clients achieve their dreams.